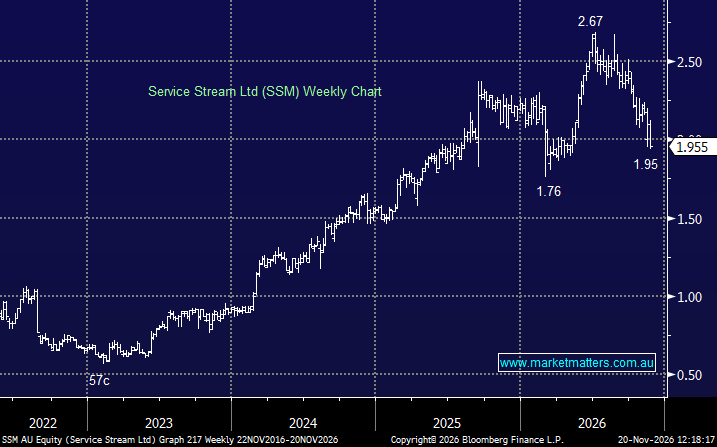
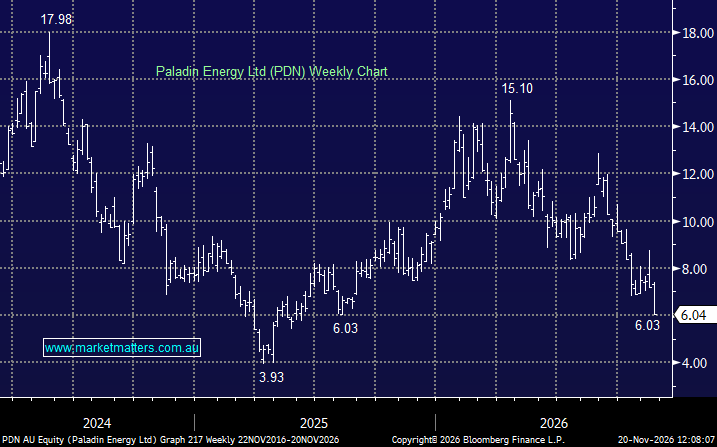
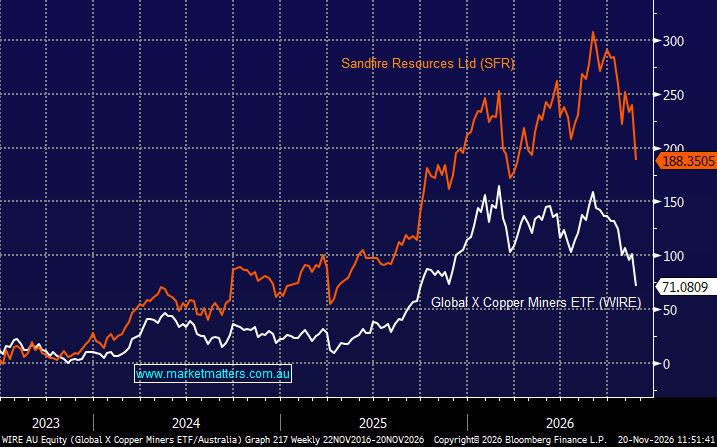
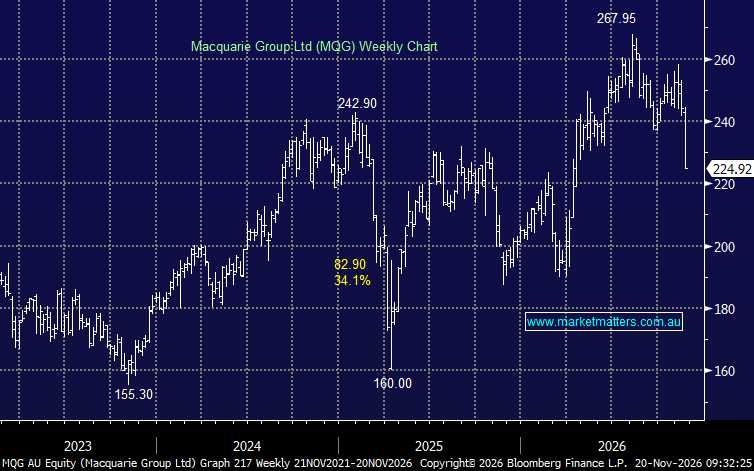
We are reducing exposure to primarily domestic facing banks, and increasing exposure to $US earners, buying Macquarie (MQG) into its recent ~15% pullback.
MM is buying MQG in the Active Growth Portfolio, allocating 4% around $220
Add To Hit List

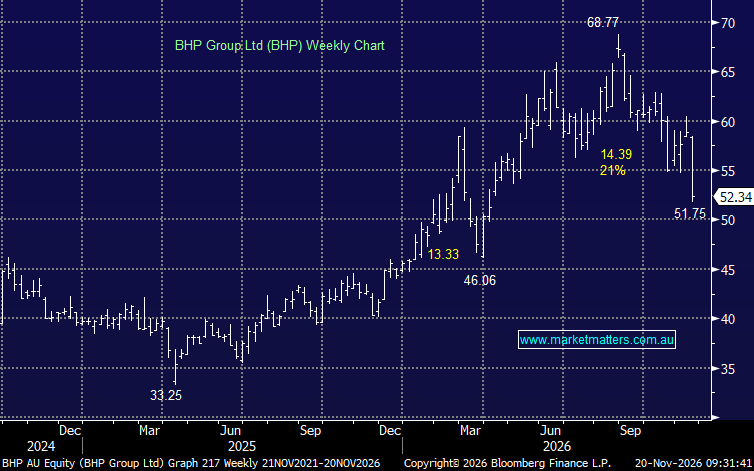
We are increasing our weighting in BHP back to a 10% target, having trimmed recently above $62. The recent sell-off has been aggressive, and we’re now moving back towards index weight.
MM is adding to BHP in the Active Growth Portfolio, increasing the target weight to 10% around $52
Add To Hit List
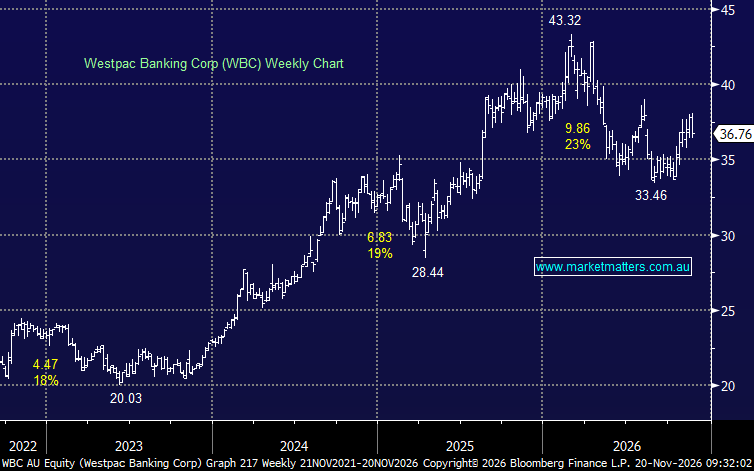
We are funding todays purchases by selling our 5% position in Westpac (WBC), taking profit. We retain an overweight position in ANZ. Macquarie’s international earnings and recent share price weakness make this a more appealing proposition, for the Growth Portfolio only (we are retaining WBC in the Income Portfolio).
MM is selling WBC in the Active Growth Portfolio, taking profit around $36.70
Add To Hit List