Skip to Content
scroll

Resources and Materials

Our Q&As are emailed in our Saturday Morning Report, find the answer to this question below.

The Latest Q&A

Question asked

Resources and Materials

To the MM team, We definitely live in interesting times, however not sure how good these times are for my blood pressure. My question is general in nature and relates to how exposed we should be to Resources. At a quick estimation it looks like your Growth portfolio has about a 30-35% holding in resources (I am including everything: coal, lithium, copper, gold, iron ore, platinum). Seems high but I am sure you have your well thought out reasons. Resources stocks have been pummeled recently, my question is "If MM did not have such a large resource exposure would you be buying the dip?" ? Lastly, if you were to buy the dip what parts of the resources category offer the best risk reward (Gold? Copper? Coal?, etc). Thanks for the great content and keep up the good work, Charles Hi Guys If you didn't already have a position in BHP and FCX at these levels, would you be buyers? Thanks Alex
Answer

Hi Guys,

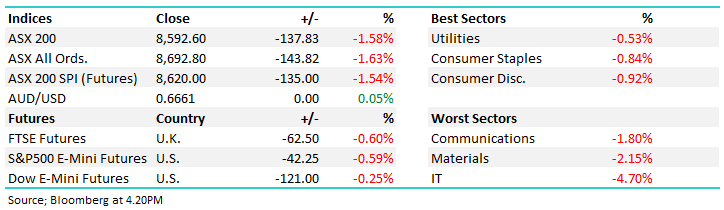
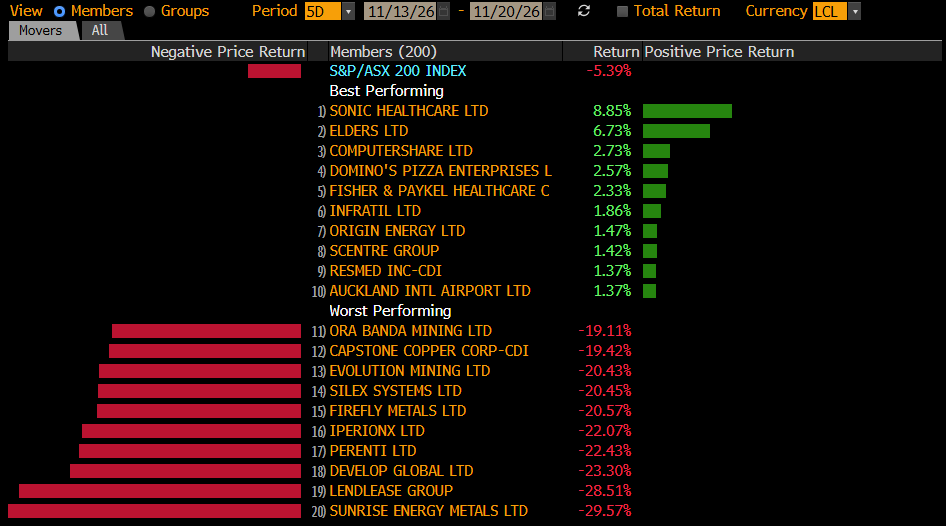
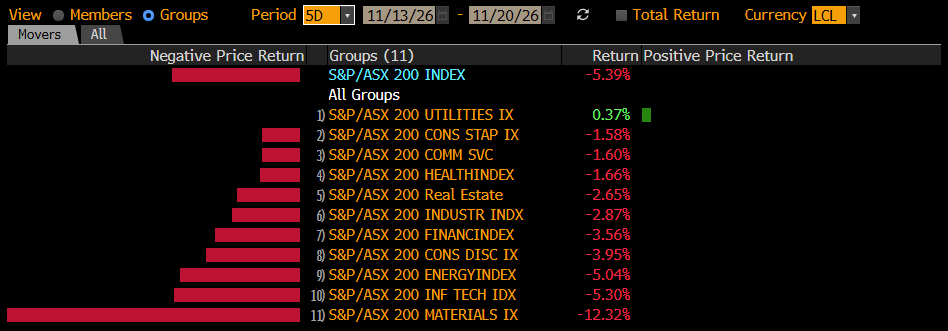
Two very similar questions around the resources which is not surprising considering the movements this week as second derivatives of the “AI Trade” fell on their proverbial sword, particularly those that have enjoyed a valuation premium from expectations of surging data centre construction and electricity demand.

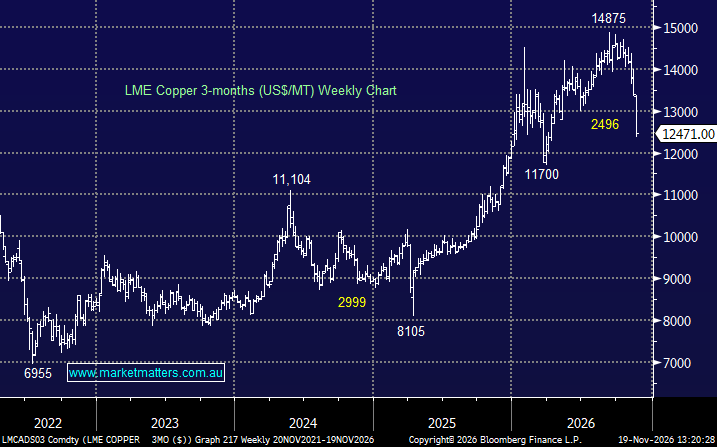
The relatively new backbone of the ASX miners’ copper (Cu) has been smacked ~20% in the blink of an eye.

  • A number of events have coincided to weigh on Cu from the blue wave victory in the US mid-terms, to rising bond yields, and the ructions at NVIDIA plus of course a significant crowded position unwind.

The crux of these two questions is what MM would do if we had no position, bearing in mind the ASX resources sector is ~29% of the ASX 200, by market cap – roughly what we hold although it’s clearly felt too much this week!

The below chart of Cu illustrates our calibrated opinion towards the industrial metal over the coming years:

  • We can see Cu testing the US12,000 area and while its rapidly approaching our buy if it’s going to consolidate as it did through 2024/5, we may not see Cu above US15,000 until 2028.

Hence with our target for this pullback by Cu only ~4% away, but a rapid recovery unlikely, we would favour buying profitable dividend paying companies that pay us to be patient:

  • Diversified miners: BHP and RIO.
  • Copper and gold: Sandfire, Evolution and Regis Resources.

The other higher beta resources areas like uranium and lithium are likely to turn at similar times,  but buying established, cash generative operators is a safer option.

  • MM would say the likes of BHP and RIO are in accumulation zones, and we would be buying if we held no position – we added to BHP on Friday in the Growth Portfolio.
chart
image description
LME Copper 3-months (US$/MT)
image description

Relevant suggested news and content from the site

Back to top