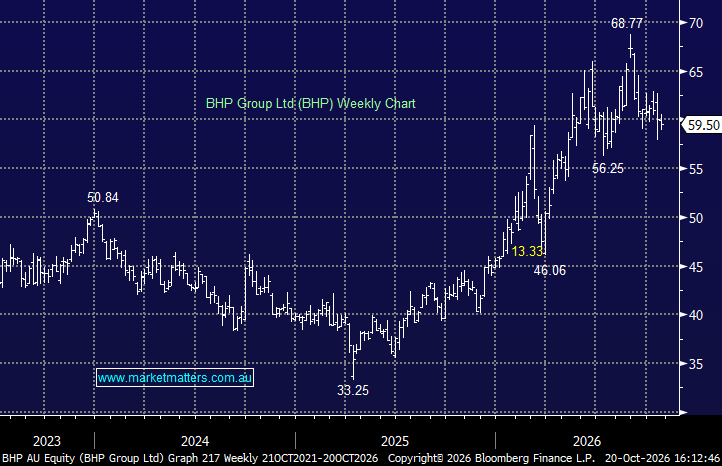
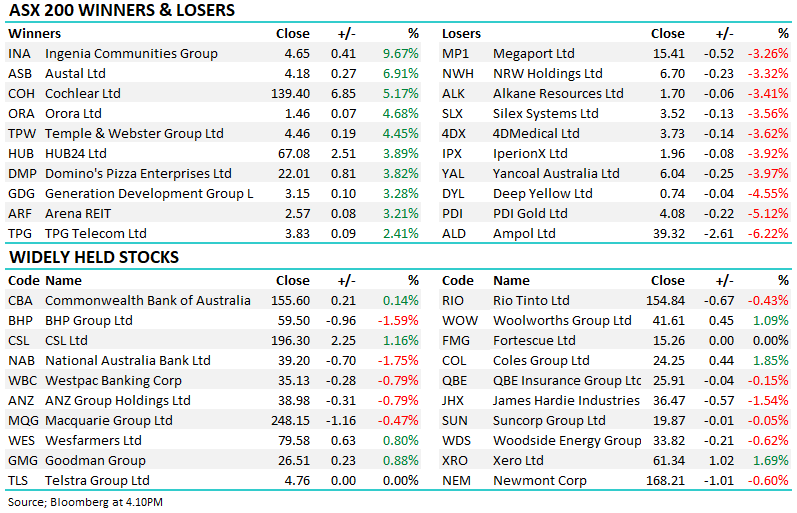
BHP –1.59% traded lower today after reporting a mixed but solid September-quarter, with strong iron ore and coal production offset by a sharp fall in copper output. Importantly, FY27 guidance was maintained across all major commodities, although copper now carries less room for error through the balance of the year.
Key 1Q27 numbers:
- WA iron ore shipments: 73.95Mt, up 4.8% YoY.
- Attributable iron ore production: 66.45Mt, up 3.7% YoY.
- Copper production: 400.7kt, down 19% YoY.
- Met coal production: 4.91Mt, up 1% YoY.
- Thermal coal production: 4.45Mt, up 26% YoY.
- FY27 guidance maintained at 260–272Mt iron ore and 1.65–1.80Mt copper.
The standout was iron ore, where WA operations delivered record mine and port performance despite a maintenance-heavy quarter. Coal was also better, particularly NSW Energy Coal, but the focus is clearly copper. Lower grades, planned maintenance, severe weather in Chile, safety-related stoppages and the Carrapateena conveyor issue all weighed on production.
The good news is price. Realised copper prices were materially higher year-on-year, helping offset weaker volumes, and management remains confident enough to hold guidance. However, BHP now needs production to improve meaningfully over the next three quarters to reach even the bottom end of its FY27 range.
Jansen also continues to progress, with Stage 1 now 87% complete and first production still targeted for mid-2027.
The copper miss is disappointing, but it looks a short term issue, while stronger commodity prices and solid iron ore performance provide support. The key swing factor from here is execution at Escondida and the broader copper portfolio; if volumes recover as expected, the earnings outlook remains attractive.
MM remains long & bullish BHP ~$60
Add To Hit List