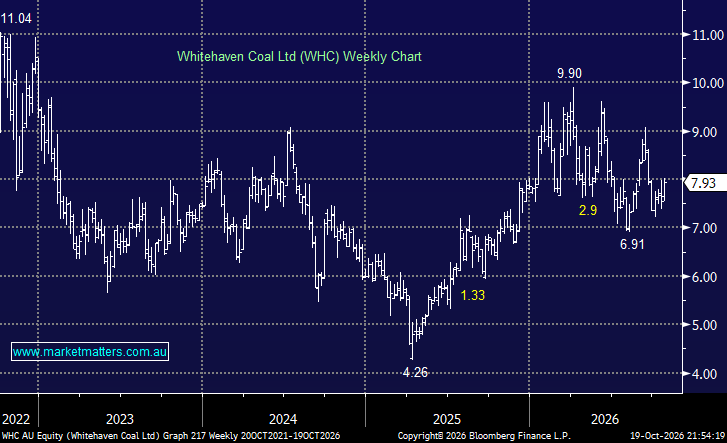
Whitehaven has been the ugly cousin compared to New Hope (NHC) in 2026, with WHC only marginally ahead YTD. NHC has been supported by its direct exposure to thermal coal prices, which have benefited from the US–Iran conflict. Its low-cost Bengalla operation provides leverage to stronger thermal coal prices, while the ramp-up at New Acland helped lift FY26 saleable production by 7.6% to 11.5Mt. WHC’s greater exposure to metallurgical coal following its Daunia and Blackwater acquisitions has limited its participation in the thermal coal rally.
China’s weak property sector continues to constrain steel demand, weighing on WHC, but as we showed, this is showing early signs of a recovery. We believe the improving commodity backdrop is encouraging for WHC, and the stock is cheap compared to the last few years, which could quickly result in a rerating on the upside for WHC.
- We like the risk/reward towards WHC, still targeting a break of $10 moving forward.
MM is long and bullish towards WHC
Add To Hit List