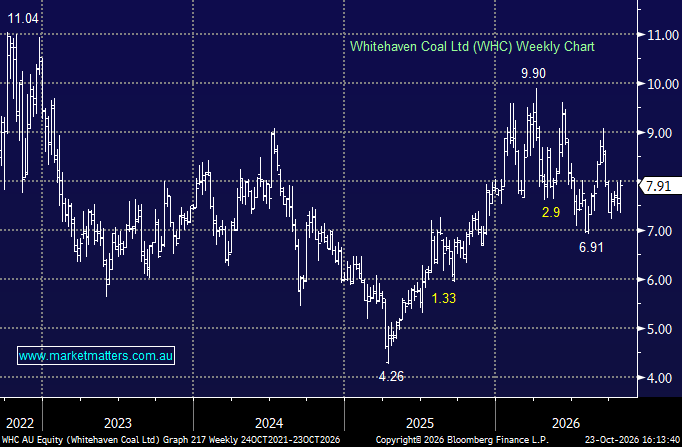
WHC –3.4%: delivered a solid start to FY27 on the production front, although sales volumes lagged as shipments slipped into the December quarter, contributing to higher inventories and net debt.
Key details:
- Managed ROM coal production of 11.03Mt, up 2.8% quarter-on-quarter and around 22% year-on-year.
- Managed saleable coal production rose 5% quarter-on-quarter to 8.47Mt.
- Total managed coal sales fell 7.8% quarter-on-quarter to 7.65Mt, while equity sales declined 10% to 6.09Mt.
- Net debt increased to approximately $1.4bn, reflecting the temporary impact of delayed sales and elevated inventories.
- FY27 guidance maintained, including ROM production of 38–41Mt, managed coal sales of 30.4–33Mt and unit costs of $132–147/t, excluding royalties.
A reasonable operational update from WHC, with production moving in the right direction but sales failing to keep pace. The key distinction is that the weakness appears to be driven by shipment timing rather than a deterioration in underlying mine performance, although the increase in net debt is worth monitoring.
We’re encouraged by the maintained FY27 guidance, particularly given the importance of consistent production and cost control in a cyclical commodity business. However, the December quarter will be important – we want to see inventories converted into sales and cash flow to improve.
MM remains long and bullish WHC
Add To Hit List