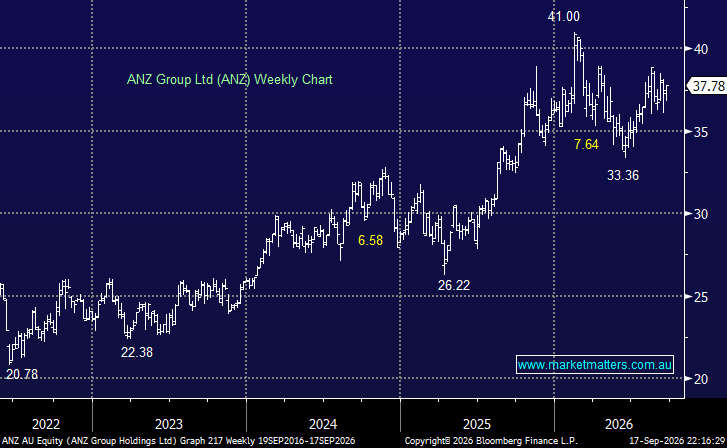
We covered ANZ in detail following its 3Q26 trading update in August here. In summary, ANZ delivered a solid update, with cash earnings (NPAT) of $1.90bn around 2% ahead of expectations.
Importantly, ANZ appears relatively well placed as housing activity slows, with mortgage applications down around 12% since the May budget compared with ~15% at CBA and ~20% at Westpac, while its larger Institutional and Business Banking franchises provide alternative avenues for growth. Margins were broadly stable, credit quality remained sound, and the early signs from CEO Nuno Matos’ ANZ 2030 transformation are encouraging.
We like the turnaround story under the new CEO, and moving forward the opportunity is for management to prove it can convert improved lending momentum, cost discipline and the Suncorp integration into sustainably higher returns on equity, which will drive ANZ’s relative valuation vs the other banks higher.
ANZ trades on 14.8x earnings and 1.6x book value, making it the cheapest of the big 4 banks, implying it has the most upside if they execute on the current transformation program – early signs are encouraging.
- ANZ remains MM’s preferred bank, and we can see the potential to post new highs into 2027.
ANZ remains our top pick in the banking sector
Add To Hit List