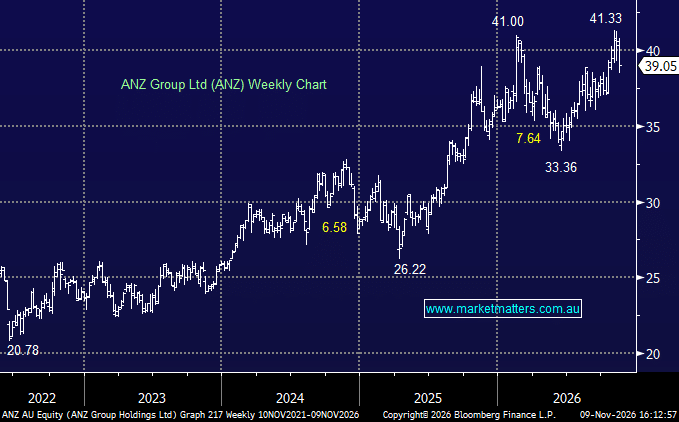
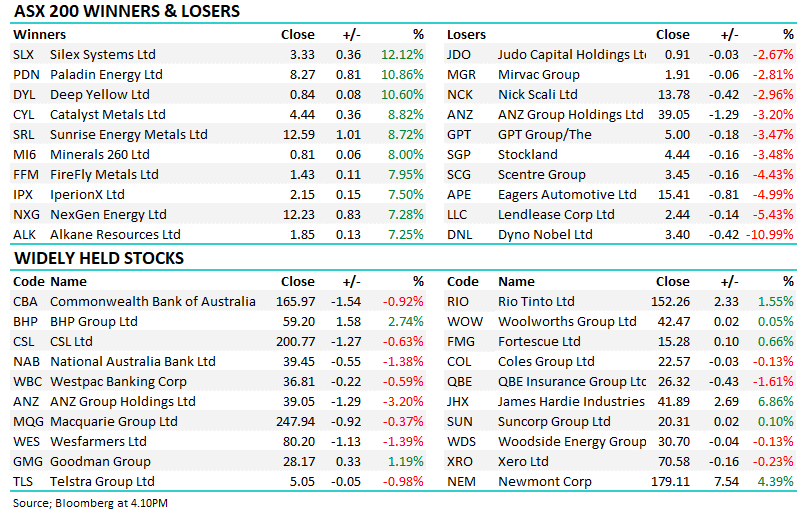
ANZ -3.2%: Reported FY26 cash profit of A$7.59bn, broadly in line with expectations as significant cost savings supported earnings. However, intensifying competition, margin pressure and a more challenging credit environment remain key concerns.
Key details:
- Cash profit rose 31% to A$7.59bn, slightly ahead of consensus
- Net interest margin eased to 1.53% from 1.55%, with further improvement likely challenging amid strong lending and deposit competition.
- Credit impairment charges totalled A$582m, while collective provisions increased to A$222m amid higher rates and cost-of-living pressures.
- Final dividend unchanged at 83¢ per share, in-line with consensus.
- CET1 capital ratio was 12%, while management flagged FY27 as a pivotal year with further investment in growth initiatives.
MM’s view: While the result was a little soft, we remain comfortable being long ANZ. After a strong run, the pullback in share price brings valuation back in check without materially changing our view that ANZ remains the best-executing local bank. Its relatively low housing exposure and ongoing turnaround under Nuno Matos continue to support our preference, with the discount to peers still looking unwarranted. We see scope for ANZ to resume its outperformance and push above $41 into 2027.
MM remains long and bullish ANZ
Add To Hit List