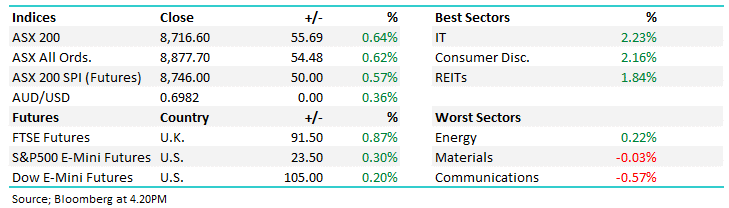
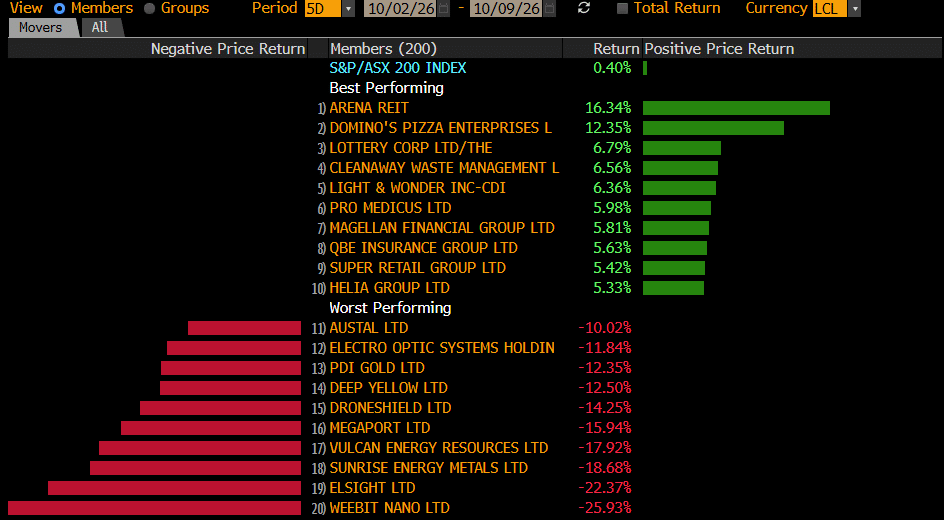
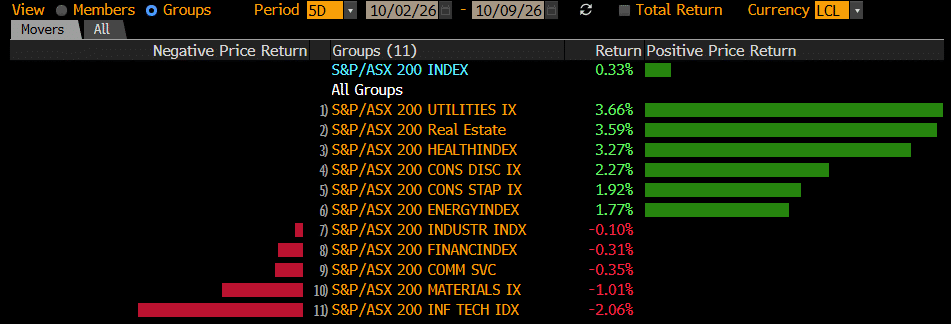
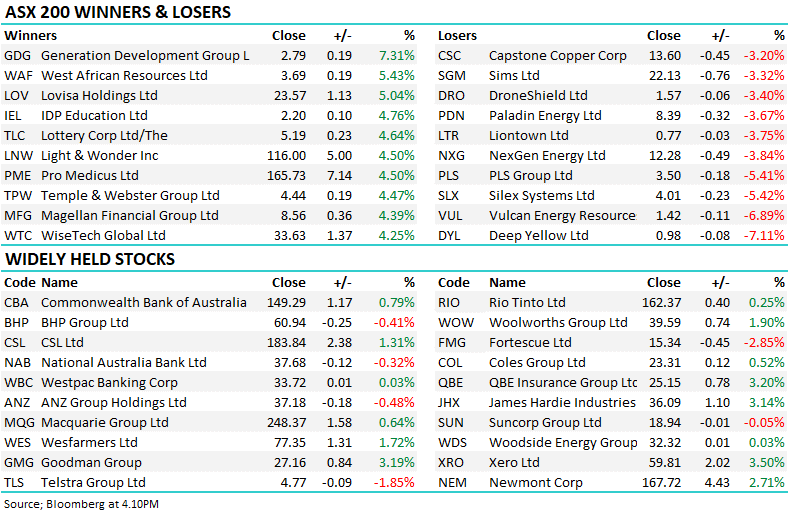
The ASX200 shrugged off some initial morning jitters to commence the week on the front foot rising +0.2% with strength in the banking sector more than offsetting losses in the heavyweight miners e.g. Commonwealth Bank (CBA) and National Australia Bank (NAB) each rallied +0.7%, while OZ Minerals (OZL) and Fortescue Metals (FMG) both fell by over -4%.
After over 3-weeks, May has delivered very little on the index level with the ASX200 up just 5-points month to-date, coincidentally the exact amount the SPI futures are calling the index to fall on the open this morning.
Thursday saw the ASX200 recover over 60% of the previous sessions losses with the banks, real estate and tech stocks leading the broad advance, 80% of the index rallied with only the resources weighing on the gains.
Yesterday saw the ASX200 tumble almost 2% as the “buy the dip” early morning attempt was thumped back into place by fairly aggressive selling across the board, 90% of stocks fell while the futures saw their volume double as worries clearly surfaced through investors’ minds.
The ASX200 bounced strongly yesterday gaining +0.6% as the choppy rotation continues, Tuesday was all about the resources from energy to gold and of course iron ore which continues to swing around with almost as much volatility as Bitcoin!
Yesterday saw the ASX200 fail to hold onto most of its early gains as the “sell the bounce” mentality continues to surface, the local market ended the day on its session lows up just 0.1% with winners and losers pretty evenly matched.
The ASX200 endured some May wobbles last week falling almost 3% by Thursday afternoon, subscribers should remain conscious that the average decline for May & June combined over the last decade is -4.8% which by definition means at its worst the intra-month pullback would have been deeper e.g. last year we saw a -7.7% retracement even while the market was enjoying a phenomenal post COVID recovery.
Yesterday saw the ASX200 fall another 62-points finally breaching the psychological 7000 area in the late afternoon, selling was fairly broad based with well over 60% of stocks down on the day although gains in the heavyweight banking & healthcare sectors stymied the losses.
Yesterday saw the ASX200 fall another 52-points testing the psychological 7000 area in the early afternoon, the worm certainly hasn’t turned yet but there’s definitely some cracks forming in some global indices and local sectors.
Overnight we saw Treasurer Josh Frydenberg spend big in an effort to create another 250,000 jobs, there’s obviously no concerns around inflation or debt levels at this point in time. The booming mining sector has enabled the cash splash from revenue not envisaged by many a year ago when the pandemic dominated most conversations.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.