South32 (ASX: S32): $5.21
S32 +1.36%: Put together a better-than-expected FY26 result, with EBITDA comfortably ahead of consensus, margins expanding and shareholder returns stepping higher.

20 minute delayed
Join Market Matters and get full access to all our Opinion + Action
Fairly valued
Morningstar Quantitative Rating as of 28 OCT 2026.
Quantitative Equity Rating Methodology – view here
Five-star price 3.90 Fair value 4.29 One-star price 4.72
Morningstar Quantitative Rating as of 28 OCT 2026.
Morningstar Quantitative Rating as of 28 OCT 2026. The slider runs from the five-star price (3.90) to the one-star price (4.72).
| Ratios |
|---|
| Currency (Price/reporting): AUD/USD |
| Exchange Rate: 1.4234 |
| Price - closing or last bid | 4.36 |
| Price - 12 month high | 5.33 |
| Price - 12 month low | 2.96 |
| Pricing date | 28 OCT 2026 |
| Volume - avg. trading volume for the last ten days | 19.34 |
| Market capitalization | 19,525.18 |
| 12 Month High price date | 9 SEP 2026 |
| 12 Month Low price date | 5 NOV 2025 |
| Volume - avg. trading volume for the last 3 months | 15.65 |
| Price - 1 Day % Change | -1.80% |
| Price - 13 week price percent change | -3.54% |
| Price - 26 week price percent change | 1.16% |
| Price - 5 Day % Change | 0.93% |
| Price - 52 week price percent change | 37.97% |
| Price - YTD price percent change | 22.47% |
| Price % Change Month To Date | -10.66% |
| EPS excluding extraordinary items - most recent fiscal year | 0.235 |
| EPS excluding extraordinary items - trailing 12 month | 0.235 |
| EPS Normalized - most recent fiscal year | 0.228 |
| Revenue/share - most recent fiscal year | 1.292 |
| Revenue/share - trailing 12 month | 1.292 |
| Book value per share - most recent fiscal year | 2.154 |
| Book value per share - most recent half-year | 2.154 |
| Book value (tangible) per share - most recent fiscal year | 2.120 |
| Book value (tangible) per share - most recent half-year | 2.120 |
| Cash per share - most recent fiscal year | 0.475 |
| Cash per share - most recent half-year | 0.475 |
| Cash Flow per share - most recent fiscal year | 0.345 |
| Cash Flow per share - trailing 12 month | 0.345 |
| Dividend per share - most recent fiscal year | 0.093 |
| Dividends per share - trailing 12 month | 0.131 |
| EBITD per share - trailing 12 month | 0.406 |
| EPS Basic excluding extraordinary items - most recent fiscal year | 0.236 |
| EPS Basic excluding extraordinary items - trailing 12 month | 0.236 |
| EPS including extraordinary items - most recent fiscal year | 0.242 |
| EPS including extraordinary items - trailing 12 month | 0.242 |
| Free Cash Flow per share - trailing 12 month | 0.093 |
| P/E excluding extraordinary items, most recent fiscal year | 12.57 |
| P/E Normalized, most recent fiscal year | 12.98 |
| Price to sales - most recent fiscal year | 2.29 |
| Price to Tangible Book - most fiscal year | 1.42 |
| Price to Free Cash Flow per Share - most recent fiscal year | 31.82 |
| Price to Cash Flow per share - trailing 12 month | 8.57 |
| Price to Book - most recent fiscal year | 1.39 |
| P/E excluding extraordinary items high, trailing 12 months | 44.27 |
| P/E excluding extraordinary items low, trailing 12 months | 11.91 |
| Net Debt, LFI | 25.00 |
| Net Debt, LFY | -278.00 |
| Dividend Yield - 5 Year Average | 2.65% |
| Dividend Yield - indicated annual dividend divided by closing price | 2.99% |
| Current Dividend Yield - Common Stock Primary Issue, LTM | 3.00% |
| Free Cash Flow - most recent fiscal year | 418.00 |
| LT debt/equity - most recent fiscal year | 13.70% |
| Payout ratio - most recent fiscal year | 38.59% |
| Total debt/total equity - most recent fiscal year | 19.06% |
| LT debt/equity - most recent half-year | 14.40% |
| Total debt/total equity - most recent half-year | 18.25% |
| Free Cash Flow - trailing 12 month | 418.00 |
| Payout ratio - trailing 12 month | 38.59% |
| Revenue - most recent fiscal year | 5,816.00 |
| Revenue - trailing 12 month | 5,816.00 |
| EBITD - most recent fiscal year | 1,827.00 |
| EBITD - trailing 12 month | 1,827.00 |
| Earnings before taxes - most recent fiscal year | 1,367.00 |
| Earnings before taxes - trailing 12 month | 1,367.00 |
| Net Income available to common - most recent fiscal year | 1,087.00 |
| Net Income available to common - trailing 12 months | 1,087.00 |
| Earnings before taxes Normalized - most recent fiscal year | 980.00 |
| Net Income Available to Common, Normalized - most recent fiscal year | 1,025.00 |
| Earnings per Share, Normalized, Excluding Extraordinary Items, Avg. Diluted Shares Outstanding, TTM | 0.23 |
| Net Profit Margin % - 1st historical fiscal year | 18.21% |
| Net Profit Margin % - trailing 12 month | 18.21% |
| Operating margin - 1st historical fiscal year | 15.25% |
| Operating margin - trailing 12 month | 15.25% |
| Pretax margin - trailing 12 month | 23.50% |
| Pretax margin - 1st historical fiscal year | 23.50% |
| Operating Margin - 5 year average | 16.59% |
| Pretax Margin - 5 year average | 11.10% |
| Free Operating Cash Flow/Revenue, 5 Year Average | 10.58% |
| Free Operating Cash Flow/Revenue, TTM | 7.19% |
| Net Profit Margin - 5 year average | 6.48% |
| Return on average assets - most recent fiscal year | 7.56% |
| Return on average assets - trailing 12 month | 7.56% |
| Return on average equity - most recent fiscal year | 11.49% |
| Return on average equity - trailing 12 month | 11.49% |
| Return on average assets - 5 year average | 3.70% |
| Return on average equity - 5 year average | 5.48% |
| Net Income/employee - most recent fiscal year | 154,215.81 |
| Revenue/employee - most recent fiscal year | 846,949.18 |
| Revenue growth rate, 5 year | 1.21% |
| EPS growth rate, 5 year | — |
| Growth rate% - dividend, 3 year | -31.29% |
| Revenue/share (5 yr growth) | 2.39% |
| Growth rate% - Revenue, 3 year | 0.99% |
| Growth rate% - EPS, 3 year | — |
| Book value per share growth rate, 5 year | 2.43% |
| Capital Spending growth rate, 5 year | 13.92% |
| Earnings Before Interest, Taxes, Depreciation & Amortization, 5 Year CAGR | 15.81% |
Financial forecast (GBP, millions except per share)
| Actuals | Estimates | |||||||
| 2026 | 2027 | 2028 | 2029 | |||||
| Estimate breakdown | ||||||||
Financials (USD, millions)
| Period end: | JUN 22 | JUN 23 | JUN 24 | JUN 25 | JUN 26 |
| Fiscal year: | 2022 | 2023 | 2024 | 2025 | 2026 |
| Period length: | 12 months | 12 months | 12 months | 12 months | 12 months |
Announcements
| DATE | TIME | HEADING | PAGES |
| Price sensitive |
S32 +1.36%: Put together a better-than-expected FY26 result, with EBITDA comfortably ahead of consensus, margins expanding and shareholder returns stepping higher.
S32 transformed its business last month through the planned sale of its aluminium, alumina and bauxite business to Alcoa in a deal worth up to US$5.6bn ($8.1bn), materially simplifying the company’s portfolio and accelerating its transition toward a future-facing base metals producer - discussed at the time here. Later in July, S32 delivered a solid fourth quarter update, discussed here, which has helped propel the stock towards fresh all-time highs.
South32 (S32) +4.62%: delivered a solid finish to FY26, with improved fourth-quarter production across alumina, manganese and Cannington, while several key operations exceeded full-year guidance. Fourth-quarter alumina production increased 4.6% to 1.29Mt, including a 6.4% lift at Worsley to 943,000 tonnes. Manganese production rose 20% to 1.31Mwmt, while Cannington payable zinc-equivalent production increased 29% to 57,800 tonnes.
S32 has transformed itself in recent weeks after selling off its aluminium value chain, including Worsley Alumina, Hillside Aluminium and its Brazilian bauxite and alumina assets, to Alcoa for an implied US$5.6bn. The package comprises US$3.1bn in cash, around US$1bn in Alcoa shares, assumed liabilities and contingent payments linked to future aluminium prices. The assets accounted for around 60% of group earnings, making this a transformational portfolio reshaping.
S32 +9.74%: announced the transformational sale of its aluminium, alumina and bauxite business to Alcoa in a deal worth up to US$5.6bn ($8.1bn), materially simplifying the portfolio and accelerating its transition toward a future-facing base metals producer. The consideration includes US$3.1bn in cash, around US$1bn in Alcoa shares, US$750m of assumed net debt and lease liabilities, plus a US$750m contingent value right (CVR) linked to aluminium and alumina prices over the next four years.
MM bought S32 last month for our Active Growth Portfolio when it wasn’t on our Hitlist; hence this morning we’ve discussed the stock and our reasoning to gain exposure to the miner following its recent pullback.
It’s not just copper that’s marching higher, aluminium is dancing a similar jig heading towards its highest level in years. This year is increasingly being described by aluminium producers and traders as a “gap year”, a pivotal period where years of underinvestment and constrained supply are colliding with rapidly accelerating demand. The metal sits at the centre of global electrification, power-grid expansion, EV production and aerospace demand, yet new smelting capacity is struggling to keep pace due to high energy costs, environmental restrictions and limited spare capacity.
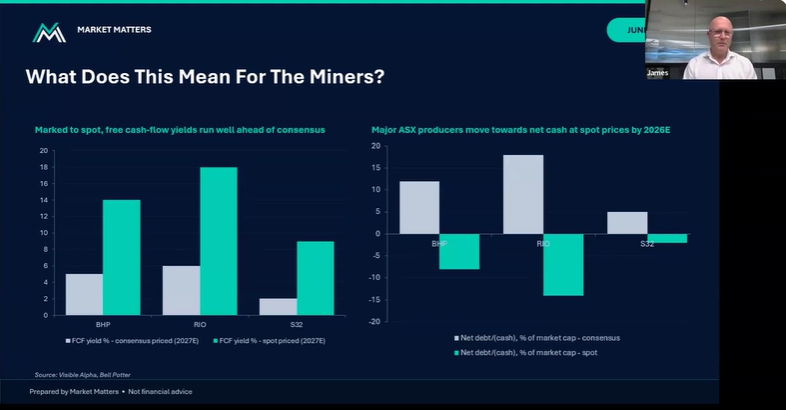
Aluminium and steel-related commodities drive S32’s earnings, with bauxite, alumina and aluminium at the core, plus silver, while the company is also a major global manganese producer with exposure to met coal. This leaves S32 well leveraged to steel demand, a theme we like amid the global push toward decarbonisation, but with less exposure to iron ore than peers like BHP and Rio, where rising supply could prove a headwind.
Volatility has been extreme in precious metals of late, but in the bigger picture, we can see deficits and declining inventories suggesting silver is now increasingly vulnerable to periods of strong investment demand, which in turn could lead to further bouts of liquidity tightness. S32 is exposed to silver through its 100% interest in the Cannington mine in QLD, which produces silver, zinc and lead, and is one of the top 10 silver mines globally.
MM remains long and bullish S32
MM remains long and bullish towards S32 around $5.10
MM remains long & bullish S32 ~$4.00
MM is long and bullish towards S32 around $4
MM is long and bullish S32
MM is long and bullish towards S32
MM is buying S32 in the Active Growth Portfolio, targeting a 4% weighting around $4.20
MM is bullish towards S32 around $4.35
MM is bullish towards S32 around $4.20
MM prefers S32 over ANZ in the coming weeks/months

South32 was born of the demerger of noncore assets from BHP in 2015. Its operations include alumina businesses in Australia and Brazil, aluminum in Brazil, South Africa, and Mozambique, and manganese businesses in Australia and South Africa. It sold New South Wales metallurgical coal in August 2024, the Cerro Matoso nickel mine in Colombia in December 2025, and has also agreed to sell its alumina and most of its aluminum assets. It also owns the Cannington silver/lead/zinc mine in Queensland. Its Australian manganese operations deliver high returns, but have a relatively short reserve life. It acquired Arizona Mining, which brings with it the high-grade and likely low-cost Taylor project in the US, and also entered copper in 2022 by buying a 45% stake in the Sierra Gorda mine in Chile.



Forgot password? Request a One Time Password or reset your password
One Time Password
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
A link to create a new password will be sent to the email address you have registered to your account.

Hi, this is only available to members. Join today and access the latest views on the latest developments from a professional money manager.

Our Smart Phone App will give you access to much of our content and notifications. Download for free today.
Hi, this is only available to members. Join today and access the latest views on the latest developments from a professional money manager.
JOIN NOW
Something went wrong. Please try again in a moment.