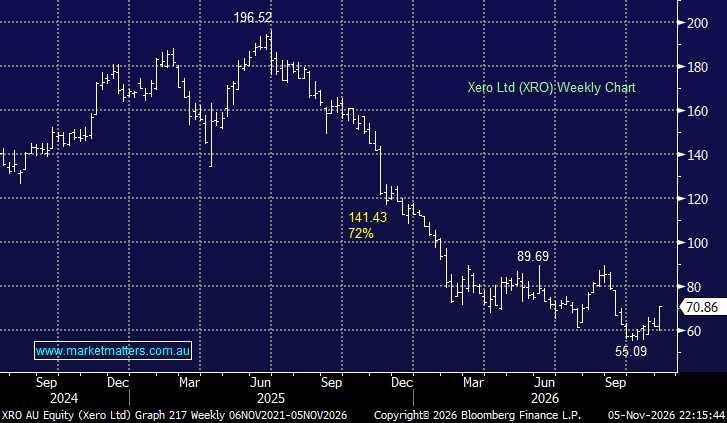
XRO shouldn’t be tarred with the same brush as the AI Trade, especially as it’s been a major casualty of the AI Disruption concerns that have rolled through many ASX and global stocks. We did a deep-dive into XRO back in September here, and our feelings haven’t changed much: XRO has been at the forefront of the sensationally named SaaSpocalypse, but Xero has delivered consistent revenue growth over the past decade, while its share price has followed a far more volatile path, heavily influenced by changing bond yields and AI concerns.
For XRO, and many ASX tech names, the main question, as we so often write with growth stocks, is what valuation investors should be prepared to pay for the anticipated growth ahead. Importantly for MM, AI could ultimately represent a greater opportunity than threat for Xero. If the company can use AI to automate more of the accounting process, lift average revenue per user (ARPU) and reduce its own development costs, the technology could strengthen its competitive position rather than disrupt it. While on 46x, the valuation is rich on traditional metrics, it’s still around the cheapest in the company’s history, trading ~60% below its 5-year average, which could prove a bargain if they nail AI adoption.
- We can see XRO testing the $90-100 area in the coming months.
MM is long and bullish towards XRO
Add To Hit List