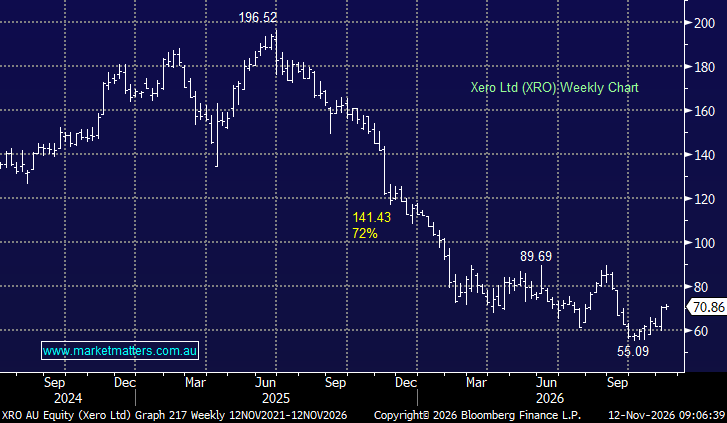
Xero (XRO) delivered a solid first-half update this morning, with revenue ahead of expectations and FY27 guidance mildly upgraded, largely reflecting stronger-than-expected performance from Melio.
Key highlights:
- 1H operating revenue: NZ$1.75bn, up 46% YoY and slightly ahead of expectations.
- International revenue: NZ$950m, up 79% YoY, well ahead of consensus.
- ARPU: NZ$62.21, up 25%, comfortably above expectations of NZ$56.92
- Subscribers: 5.15m, up 12% – inline with consensus
- FY27 revenue guidance increased to NZ$3.77–3.83bn from NZ$3.62–3.73bn. The market was sitting at $NZ3.66bn, so about 4% ahead.
- Adjusted EBITDA guidance narrowed to NZ$880–920m, lifting the bottom end – the market was already at $NZ901m – so not much change there
- Xero now sees FY28 revenue above NZ$4.6bn, excluding synergies – the market was at NZ$4.4bn (not sure if synergies were in this number) but assuming they weren’t, it’s about +4.5% ahead of consensus.
- A A$1bn on-market buyback has also been announce – this good news, and equates to about 8% if issued shares if they go through with the lot. The buy back can start as soon as tomorrow (13th Nov).
Some focus will be on weaker than expected headline net profit and free cash flow, but that reflects the impact of Melio and integration spending, while gross margins remain below historic levels. However, management expects stronger second-half EBITDA as price rises, payments growth, cost discipline and lower Melio losses begin to flow through.
MM’s view: We think this is a good update. The important numbers are heading in the right direction – revenue guidance has moved higher, ARPU is strong, International is outperforming and Melio appears to be gaining traction faster than expected. The buyback is also a positive signal.
MM remains long & bullish XRO
Add To Hit List