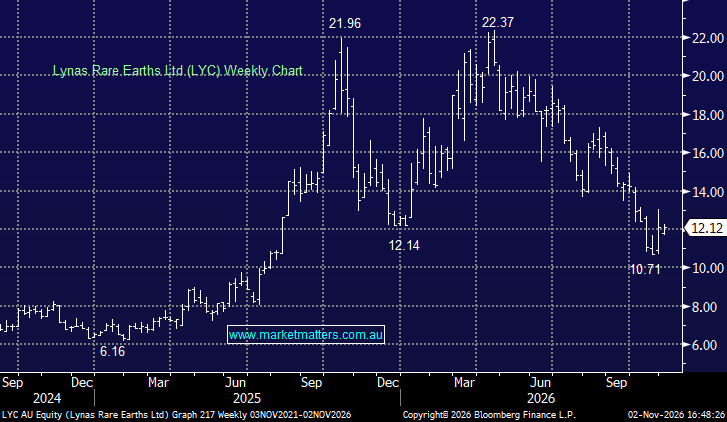
Lynas Rare Earths (LYC) is Australia’s dominant producer and the largest rare earths supplier outside China, with NdPr oxide as its key revenue driver, alongside lower-value co-products such as lanthanum and cerium. In the September quarter, LYC produced 4,254 tonnes of total rare earth oxides, with revenue rising 55% year-on-year to $310mn. The company processes ore from its Mt Weld mine in Western Australia at its Malaysian separation facility, while it’s expanding its Australian processing capabilities.
This $12bn miner is forecast to deliver $1.52bn revenue in FY27 and EBITDA of $800mn.
However, LYC is very much a growth story, with the 2030 investment case for LYC being about becoming a broader, vertically integrated rare earths supplier outside China, rather than simply increasing NdPr production. Its strategy has three key pillars: expanding and improving its Mt Weld resource base, including developing higher-grade carbonatite ore and securing additional feedstock; increasing downstream capacity, including targeting 12,000 tonnes per annum of NdPr separation capacity and expanding production of higher-value heavy rare earths such as dysprosium and terbium; and moving further into the metal and permanent magnet supply chain through partnerships and joint ventures.
- In FY30, consensus expects LYC to deliver revenue of $2.6bn and EBITDA of $1.67bn – around a 70% lift.
The commercial opportunity is to capture more value across the supply chain, diversify its product mix and secure long-term customers seeking alternatives to Chinese supply. LYC already has a 12-year Japanese supply agreement that includes a US$110/kg NdPr floor price on 5,000 tonnes per annum, providing a degree of earnings visibility. If it can deliver the next phase of expansion and translate its heavy rare earth and downstream investments into higher margins, the business should look materially different by 2030.
Hence we view short-term cost pressure as secondary to the longer-term growth opportunity, although execution, capital requirements and rare earth pricing remain key risks. How much LYC makes will continue to largely be driven by the levers that China decides to pull.
- We like LYC as a quality vehicle for rare earths exposure, but it’s still 3x more expensive than, say, BHP due to the rare earths premium still in the stock.
MM is cautiously bullish towards LYC around $12
Add To Hit List