Hi Young,
Thanks for the thumbs up, much appreciated!
Two stocks whose fate is largely in the hands of China which keeps us cautious:
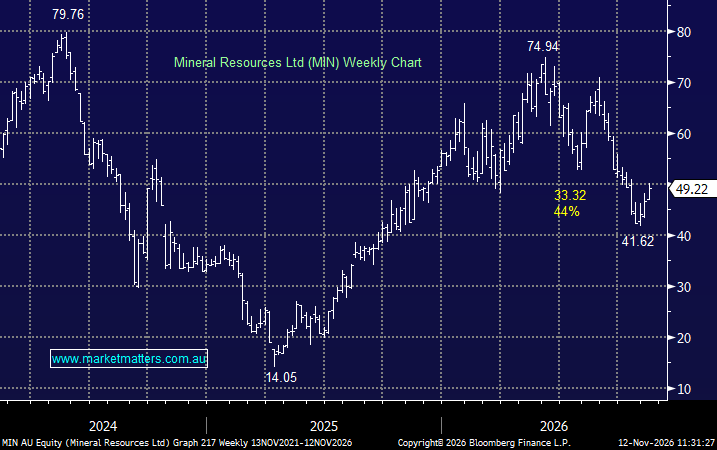
Mineral Resources (MIN) – MIN isn’t a lithium stock per se but it’s very much where the company’s growth is expected to come from. Hence, the stock’s recent ~40% correction, in line with the lithium sector, which was has been hit by a triple blow:
- A sharp increase in reported Chinese inventories following a methodology change, China’s temporary suspension of new battery projects pending an industry capacity review, and the growing threat of cheaper sodium-ion batteries replacing lithium in some applications.
While the inventory shock is largely an accounting issue, the demand uncertainty and substitution threat are more concerning, potentially weighing on lithium prices and sector valuations for some time, much as fears of AI disruption have hammered software stocks before the full impact is known.
However, we now see decent risk/reward towards MIN ~$48 with its iron ore and mining services divisions adding decent value support.
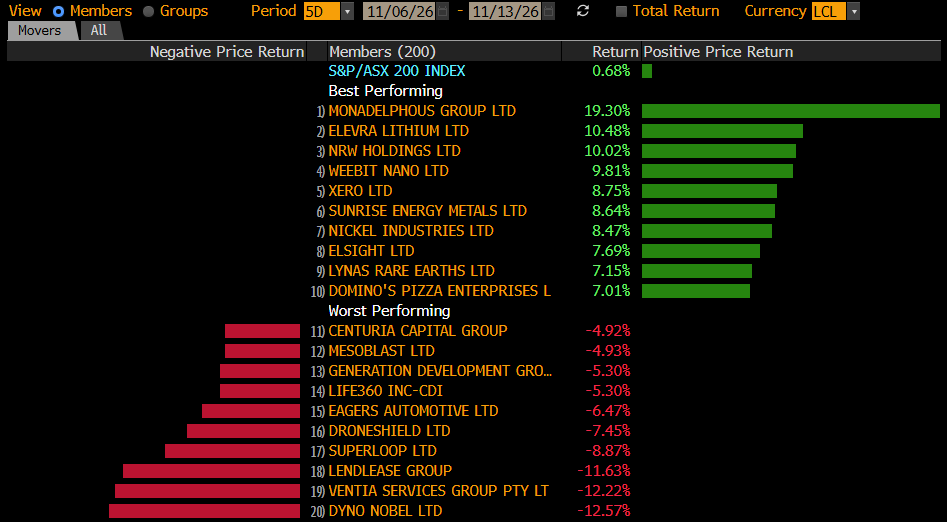
Lynas Rare Earths (LYC) – having more than halved from its April high leading us to adopt a more constructive stance ~$12. The issue for LYC has been twofold:
- LYC is a light rare earths producer. Its core product is NdPr (neodymium-praseodymium) oxide, which accounts for the large majority of its revenue has fallen ~8% weighed down by softer EV demand and easing supply fears.
- LYC disappointed investors with a 26% 4Q26 revenue miss, weaker-than-expected full-year profits amid rising costs and operational challenges, and planned shutdowns in Malaysia and Australia that threaten near-term production.
This is undoubtedly a volatile beast but we still like the risk/reward below $14, but it’s not for the faint hearted.