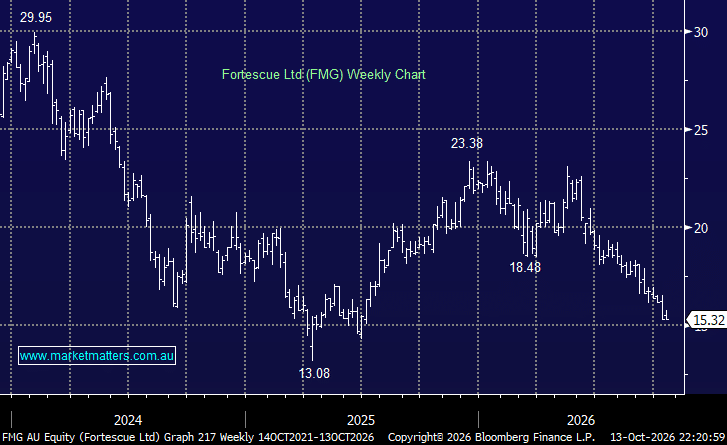
Fortescue (FMG) has continued to weaken following a disappointing September-quarter update, and we’re reviewing our position in the Income Portfolio. The issue is less the iron ore price itself and more weaker cash conversion at a time when capital spending remains elevated.
September-quarter shipments were 46.8Mt versus 49.7Mt expected, while sales were softer again at 42.9Mt, driving a 3.9Mt inventory build. Net debt subsequently increased from US$0.9bn in June to US$2.8bn. The key uncertainty is the ongoing negotiation with China’s CMRG, which is weighing on sales and realised pricing. UBS recently cut its FY27 EPS forecast by 16% and expects weaker price realisation through the first half.
At the same time, FMG still has substantial capital commitments across Iron Bridge, Blacksmith and its decarbonisation program. The issue for us is that FY27 operating cash flow is now likely to dip below capex, which could put pressure on the dividend.
While there is scope for improvement if the CMRG issue is resolved quickly and inventory converts back into cash, the near-term setup has clearly deteriorated. At ~$15.80, FMG is on the cheaper side, but with earnings, free cash flow and likely dividends all moving lower, we think the prudent move in the near term would be the cut the position, take the ~14% loss and re-allocate the capital into a lower risk position.
MM is likely to cut FMG from the Income Portfolio
Add To Hit List