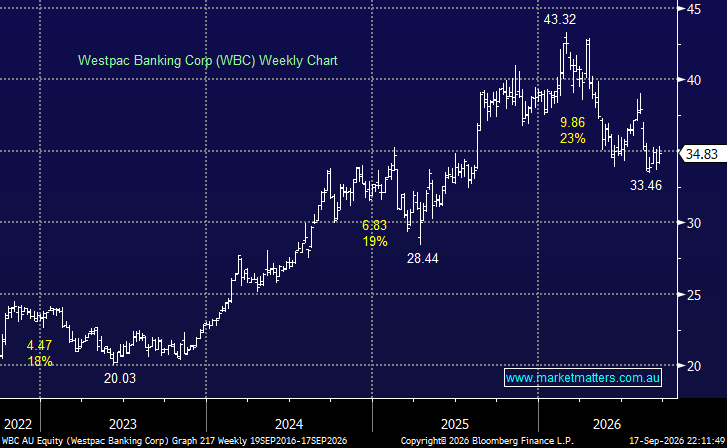
We covered WBC’s disappointing August 3Q26 trading update here, and the stock has underperformed its peers since, as is generally the case in the current market.
The ~20% pullback from recent highs is aggressive and as we’ve previously flagged, we think there is a good chance that WBC could surprise with a larger than expected dividend in November, hence we have recently added WBC to the Income Portfolio.
Westpac’s investment case is more about excess capital than growth in our opinion. WBC’s CET1 ratio was 12.75% at the end of March (reported at their 1H26 results in May), implying around $2.7bn of surplus capital above its internal target. The subsequent sale of the $15.4bn RAMS mortgage portfolio added another 23 basis points to CET1, equivalent to more than $1bn of additional capital headroom.
Westpac also has approximately $3.7bn of surplus franking credits, the largest balance among the major banks. That creates a strong incentive to return capital through fully franked dividends rather than relying exclusively on buybacks.
Following the recent pullback, we think the yield support is attractive, and the potential special dividend becomes more meaningful. If consensus is correct, and WBC pay 80cps in November, plus a 30c special (mid-point of potential), a $1.10 dividend equates to 3.2% for the half fully franked, or 4.6% gross. If they keep the 80cps in May 2027, the 12-month yield is worth ~8% (incl franking).
- We wouldn’t be surprised to see WBC bounce back towards $39-40 into Christmas
WBC is MM’s preferred bank for Income
Add To Hit List