New Hope’s FY26 result released yesterday was broadly in line at the earnings level, but the more important story is the setup into FY27. Earnings fell sharply as realised coal prices declined and costs rose through the New Acland ramp-up, but production increased, the balance sheet strengthened and coal prices have already rebounded materially since year-end.
Key results:
- Revenue of A$1.77bn, slightly ahead of A$1.76bn consensus.
- Underlying EBITDA of A$514.3m, down 33% but essentially in line with A$514.2m expected.
- Adjusted net income of A$161m, broadly in line with expectations.
- Final dividend of 30cps fully franked, taking FY26 ordinary dividends to 40cps.
- Free cash flow of around A$370m.
- The balance sheet finished in net cash, stronger than expected.
The earnings decline was largely driven by a 10% fall in realised coal prices to A$145.2/t, while group FOB cash costs rose 7.9% to A$88.9/t. This compressed underlying margins from A$64.4/t to A$45/t.
However, the cost story is important. New Acland is still ramping towards its targeted 5Mtpa saleable production rate, which is temporarily pushing group unit costs higher. At full run-rate, management expects costs to become more comparable with Bengalla. Bengalla also returned to its targeted 13.4Mtpa ROM run-rate in the second half following pit-sequence realignment, while group saleable production increased 7.6% to 11.5Mt and coal sales rose 11.8%. That leaves the business entering FY27 from a much stronger operational position than the headline FY26 profit result suggests.
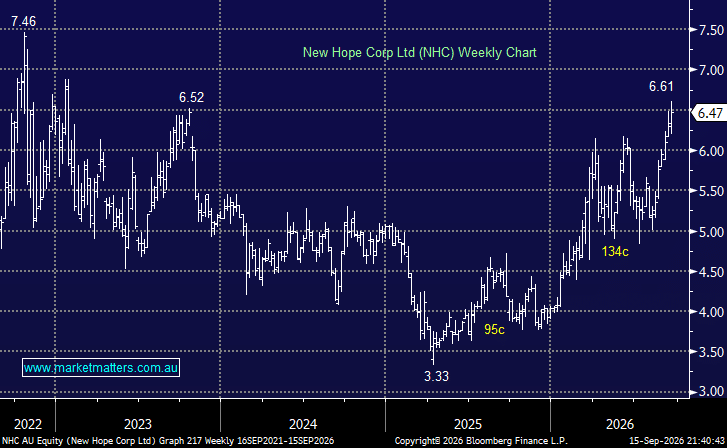
The other key change is coal pricing. Thermal coal prices have rebounded sharply from their lows, with the Newcastle benchmark sitting around US$148/t. Very little of that recovery is reflected in the FY26 numbers.
We would not base the investment case on spot coal prices remaining at current levels, but stronger pricing combined with higher production and a normalising cost base creates a much better earnings setup. Consensus currently expects EBITDA to rebound towards A$738m in FY27, producing an expected yield of ~6.6% fully franked.
The balance sheet remains another major positive. NHC finished FY26 in net cash, continues to generate strong free cash flow and refinanced A$300m of convertible notes at 2.625%, down from 4.25%.
- We own NHC in the Active Income Portfolio and remain comfortable holding it even though the FY26 earnings decline looks ugly on paper – we think it is more likely to represent the trough than the start of a weaker trend.
Bengalla is back at run-rate, New Acland continues to ramp, production is increasing, the balance sheet is strong and coal prices have recovered materially from the levels reflected in FY26. Importantly, the investment case is not purely a call on higher coal prices. There are operational levers within NHC’s control that should support earnings growth through FY27, while the constrained supply backdrop remains supportive for established, low-cost producers.
MM remains long and bullish NHC
Add To Hit List