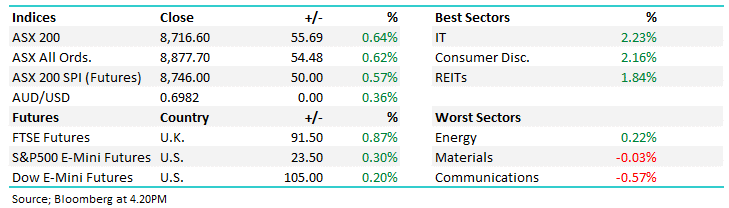
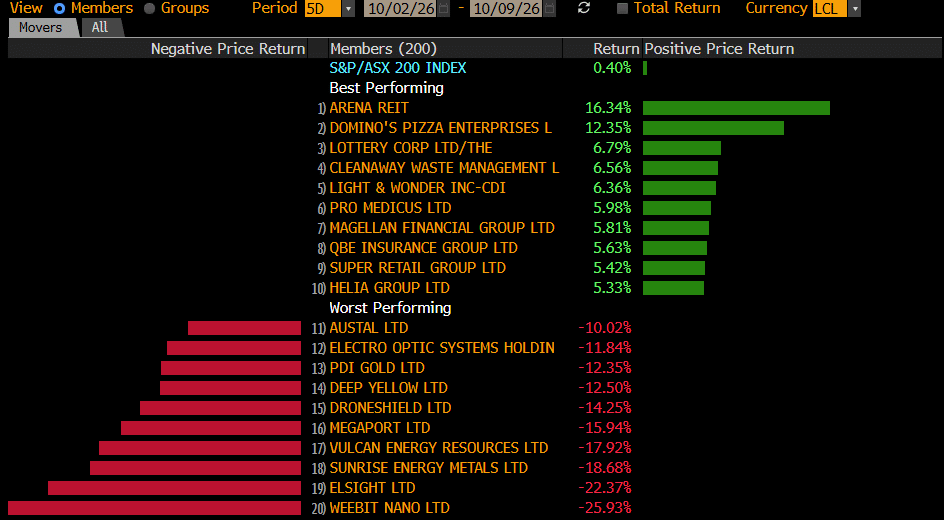
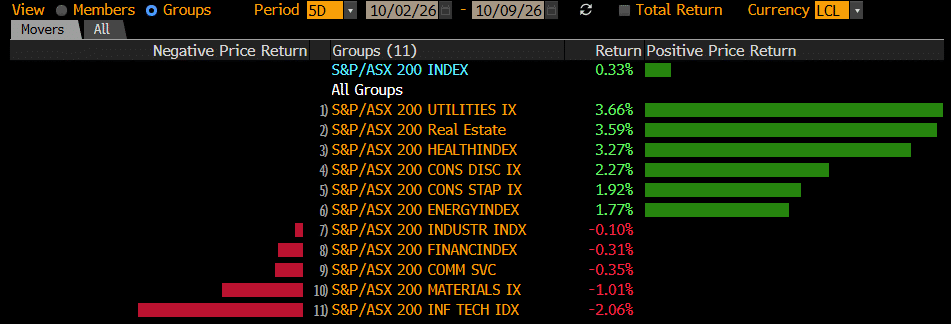
The rally by building stocks caught my attention yesterday in what was another fairly lacklustre session. The 4 local building stocks we are looking at today reside in the large Materials Sector which is illustrated below. At MM we had reduced our exposure to the influential Resources Sector.
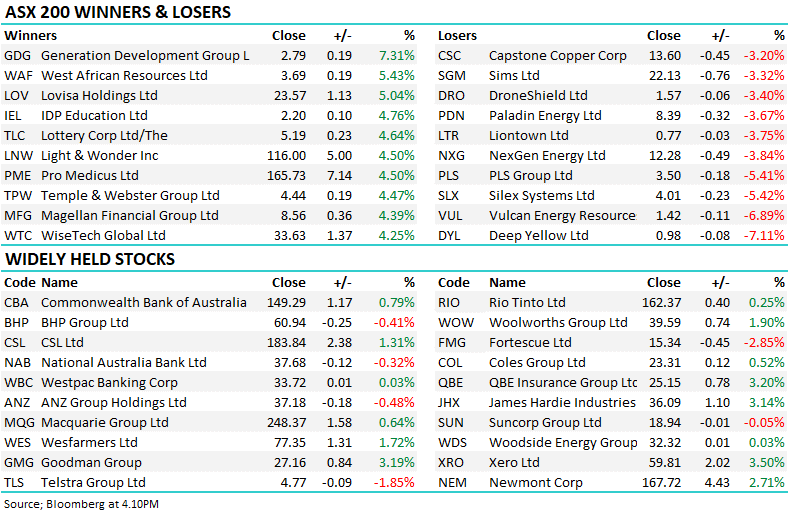
The ASX200 enjoyed a surprisingly strong Wednesday ignoring weakness in both the US and Asian Indices, although only just over half of the stocks rallied from an index perspective strength was at the right end of town with both Commonwealth Bank (CBA) and CSL Ltd (CSL) up by almost 2%. Weakness was again focused in the recovery and European facing stocks as the COVID situation deteriorates in many parts of the world, whenever I type words like this I think how lucky we’ve been in Australia.
The ASX200 again challenged the 6800 area early on yesterday only to spend the afternoon drifting lower on broad based selling, the tourism stocks garnered some especially harsh treatment e.g. Flight Centre (FLT), Corporate Travel (CTD) and Webjet (WEB) fell by an average of -3.8%. The market remains choppy and non-committed in both directions making it easy to adopt both a bullish & bearish outlook over 24-hours, overall we feel its best to adopt the attitude of “if in doubt do nowt”.
The ASX200 kicked off the week in good form closing up +0.7% as 65% of the index rallied and all sectors advanced except the resources which fell as iron ore tumbled over 7% at its worst. The greater their leverage to the bulk commodity the harder they fell from RIO Tinto (RIO) -1.2% to Fortescue (FMG) -4.3% and Champion Iron (CIA) -10.1% at the extreme, as the sector falls out of favour we are slowly becoming more interested but we’re in no hurry, just yet.
The ASX200 struggled last week even while US indices scaled fresh all-time highs, Europe posted new COVID highs and Asia was stable. The -0.9% fall locally was largely caused by the value end of town as Banks & Resources surrendered some of their recent gains with the likes of BHP Group (BHP) and RIO Tinto (RIO) both falling over 6%, however the interesting side of the coin is bond yields continued to rally posing the question - “are value stocks pre-empting a pullback / period of consolidation in bond yields?”. Subscribers know our view on this subject hence today I’ve looked at a few different pockets of interest to keep our finger on the financial markets pulse.
The ASX200 is starting to feel very tired as it continually discounts apparent good news while embracing anything that feels vaguely off point. Local stocks are up only +2.4% year to-date compared to the S&P500 at +5.8% and it’s been weighed down by the heavyweight tech sector which has struggled as bond yields have rallied higher (both basis yesterday afternoon). The selling which drove stocks down yesterday was broad based and fairly unrelenting although not aggressive and outside of the Gold Sector there weren’t many bright areas – it felt to me like stocks were trying to 2nd guess how US stocks would digest the Feds rhetoric after a good night’s sleep, they were clearly nervous which has proved well founded given the Nasdaq’s ~3% decline.
The ASX200 continues to tread water around the 6800 area, yesterday saw over 70% of the market close in the red but in line with the recent lack of commitment the underlying index was unable to make a meaningful move away from the magnetic pull of 6800. The Fed is likely to awaken equities from their slumber following their comments this morning as Jerome Powell attempted to talk up the economic recovery while not unnerving markets that interest rates will rise in the near future – it feels akin to a gymnast balancing on a beam, this time we feel he should be ok but it’s becoming a tougher ask as each month goes by, especially as longer dated bond yields push higher.
I reiterate MM believes the defensive stocks will outperform in the coming few months hence we have started aligning our portfolios accordingly e.g. yesterday in our Growth Portfolio we reduced our holding in Commonwealth Bank (CBA) and finally went long CSL Ltd (CSL) after a very long absence from the healthcare giant which makes up ~7% of the ASX200. However to be more precise we actually believe the markets due some reversion back towards yield sensitive stocks / sector illustrated perfectly by the IT stocks rallying almost 3% yesterday.
MM has been looking for a recovery by the defensive sectors over recent sessions and its slowly been playing out but the big question is do we believe the likes of Healthcare will rally or simply outperform some hot value stocks that have soared in 2021.
The ASX200 rallied almost 1% last week but it noticeably underperformed the Dow which rallied over 4% to fresh all-time highs, unfortunately we remain 6% below our 7197 all-time high posted in February last year. A couple of COVID cases plus an amazing Labor landslide victory in WA wont help the local market today which was already only looking for a flat opening following another poor session by US tech stocks on Friday night.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.