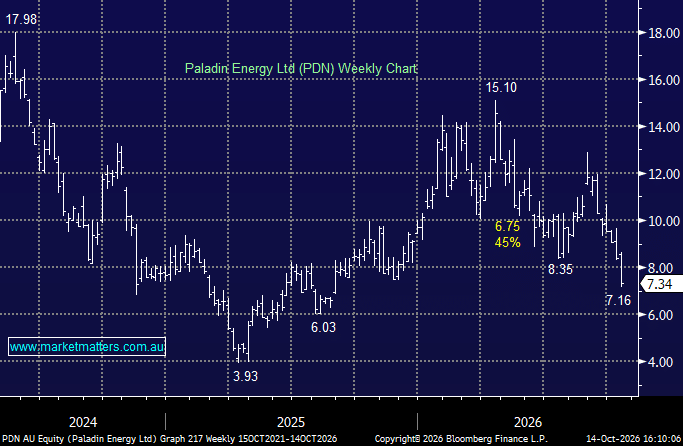
PDN -9.34%: The September quarter was softer than expected, with lower production and higher costs at Langer Heinrich, however the sell off looks like an overreaction to us, given the planned shutdown was already well communicated to the market. We’re reassured by management maintaining FY27 production guidance, though we can’t ignore that the update has landed at an unfortunate time, with uranium equities already under pressure both locally and globally, amplifying the move.
Key results:
- Uranium production: 1.00Mlbs, down 19% QoQ and around 14% below consensus.
- Uranium sales: 1.16Mlbs, down 14% QoQ.
- Production costs: US$61.60/lb, up 19% QoQ.
- FY27 guidance maintained: Production of 5.1–5.6Mlbs, sales of 4.8–5.3Mlbs and costs of US$44–48/lb.
The weak quarter reflected a planned shutdown, softer recoveries and low opening inventory within the processing circuit. Importantly, management expects production to accelerate in the second half as higher-grade ore enters the plant. That recovery is essential, with the full-year targets now requiring a substantial improvement in grades, recoveries and operating costs.
We continue to hold PDN in our Active Growth Portfolio and believe the selling is overdone at these levels, particularly given the broader weakness across uranium stocks. Management’s recent efforts to improve transparency give us some confidence in its reiterated guidance, although the operational recovery still needs to be delivered. We’re optimistic that higher grades will drive a stronger second half and are comfortable maintaining our exposure rather than selling into sector-wide weakness.
MM remains long and bullish PDN
Add To Hit List