Hi Andrew,
We’ve been asking ourselves similar questions around PDN this week, their timing for capital raises leaves a lot to be desired!
- In Sept/Oct PDN raised a total of $400mn at $7.25 primarily to advance the Patterson Lake South (PLS) uranium project in Canada.
- This month PDN raised $500mn, assuming an unsuccessful SPP, again to advance its PLS project, support exploration and strengthen its balance sheet.
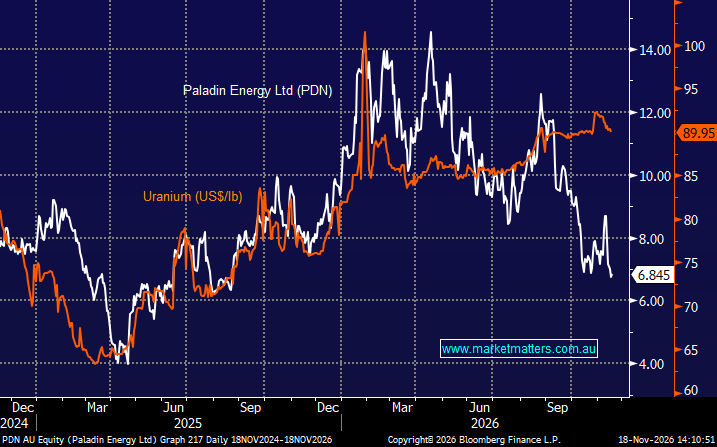
Over the last 3 years PDN’s average closing price has been $9.96 while it was trading significantly above $10 for many months, including hitting a high ~$18 in 2024 and $15 in 2026 hence our comments around the timing of PDN’s capital raisings.
Paladin’s November raising is primarily about funding PLS, however, coming just 14 months after its previous $400m raising, highlights the capital-intensive nature of its growth ambitions and raises legitimate questions about further dilution before PLS reaches production in 2031 – the market wasn’t expecting them to tap the market until 2027.
- We have been surprised to see PDN trade well below the raise but believe this is more around the recent AI disruption as opposed to problems at PDN itself.
Pricing assumptions are where we see room for a bullish re-rating from PDN:
- UBS have a price target of $11.80 with a long-term assumption for U308 of US$100/lb.
Long-term uranium contracts are trading above US$100/lb versus spot ~US$90/lb, with demand expected to outgrow supply into the 2030s. Hence, we are targeting the US$110-120/lb area which should create a major tailwind for PDN during times of positive sentiment.