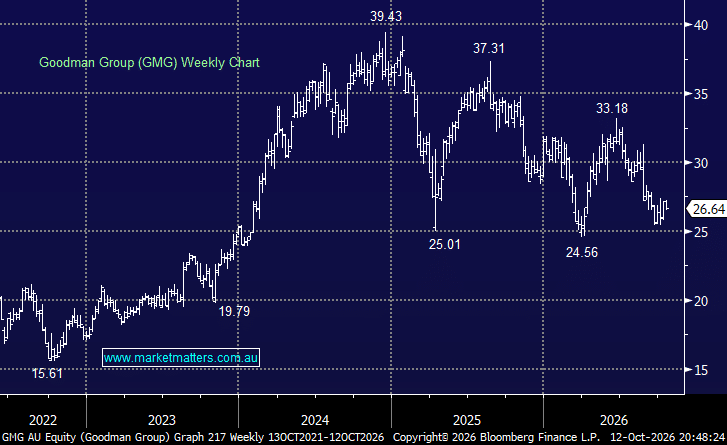We discussed GMG at length 2-weeks ago here, after they delivered a solid FY26 result, with operating EPS increasing 10%, although FY27 growth guidance of 9% was slightly below expectations. Its data centre opportunity continues to expand rapidly, with development work in progress (WIP) up 53% to $19.7bn, of which 78% is allocated to data centres. The strategic shift towards fully fitted facilities should allow GMG to capture a greater share of the AI infrastructure investment boom, although this also comes with higher capital requirements and increased execution risk.
The key now is execution. GMG has built an impressive development pipeline, but the next leg of the investment case hinges on converting that pipeline into contracted, cash-generating assets. With several major projects approaching completion in 2027, securing new customer commitments will be critical to validating demand, underpinning earnings growth and ultimately justifying the significant capital being deployed.
We believe much of the recent share price weakness reflects uncertainty around the timing of these leasing commitments rather than any fundamental deterioration in the longer-term opportunity. Trading on approximately 20x forward earnings, compared with its long-term average of 23x, GMG is becoming increasingly attractive from a valuation perspective. However, a sustained re-rating will likely require tangible evidence that its substantial development pipeline is translating into profitable, contracted earnings.
- GMG has a good track record of identifying and developing high-quality infrastructure assets – now the challenge is to deliver on this new playing field by securing major data centre contracts and converting its ambitious pipeline into earnings. The potential is significant, but execution is now everything.
MM is long and bullish towards GMG
Add To Hit List