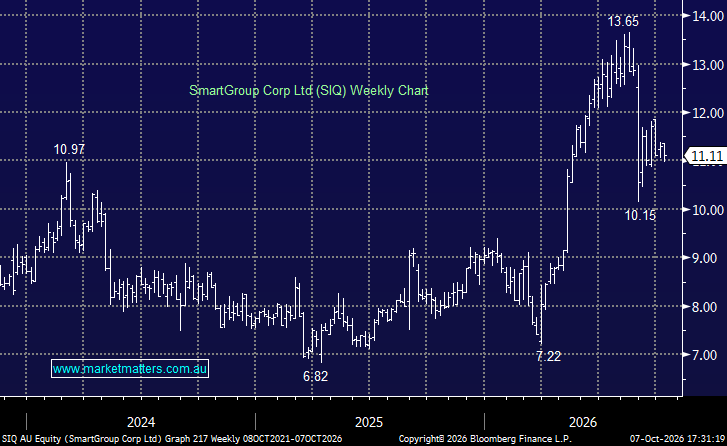
SIQ is no stranger to the ASX 200, having exited a year ago, but its hiatus hasn’t lasted long. This $1.5bn business is one of Australia’s leading employee-benefits providers, specialising in salary packaging, novated vehicle leasing and fleet management, with a large customer base across government, healthcare, education and not-for-profit organisations. Its growth is becoming increasingly leveraged to novated leasing and EV adoption, where favourable tax treatment has helped drive demand for salary-packaged vehicles.
The stock was volatile in August around the time of its FY26 result covered here, which were ok but failed to live up to lofty market expectations. Overall we felt the core business continues to perform well, EV adoption remains supportive and there is a credible pathway to stronger margins as technology investment starts to deliver operating leverage.
The exit (September 2025): SIQ was one of nine stocks removed from the ASX 200, effective prior to trading on 22 September 2025, despite its shares having performed reasonably well over the preceding year. S&P did not provide a company-specific explanation, but SIQ had slipped sufficiently far down the relative market-cap rankings as the gold miners in particular soared higher
- We’ve seen this before with lithium stocks, with “hot sectors” often coming and going fairly quickly.
The return (September 2026): After a 12-month hiatus, SIQ’s return wasn’t simply a case of creeping back above 200th place: S&P confirmed the five entrants had three-month average float-adjusted market-cap rankings inside the 179th-rank entry buffer, while existing constituents generally have protection until falling below 221st.
SIQ’s re-rating was supported by improving operating momentum, including record customer numbers and strong novated-leasing demand. In other words, SIQ’s return was underpinned by genuine earnings and share-price momentum rather than index buying alone a healthier foundation for its latest stint in the ASX 200.
- We have owned SIQ before in the Income Portfolio and may again with a yield of ~5% fully franked.
MM is neutral SIQ for now, but would get interested ~$10
Add To Hit List