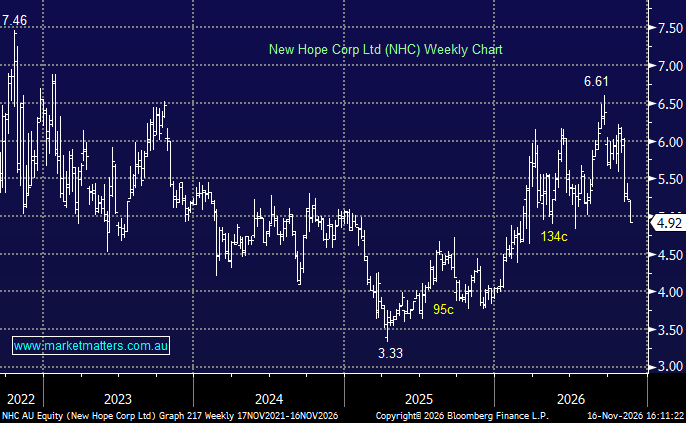
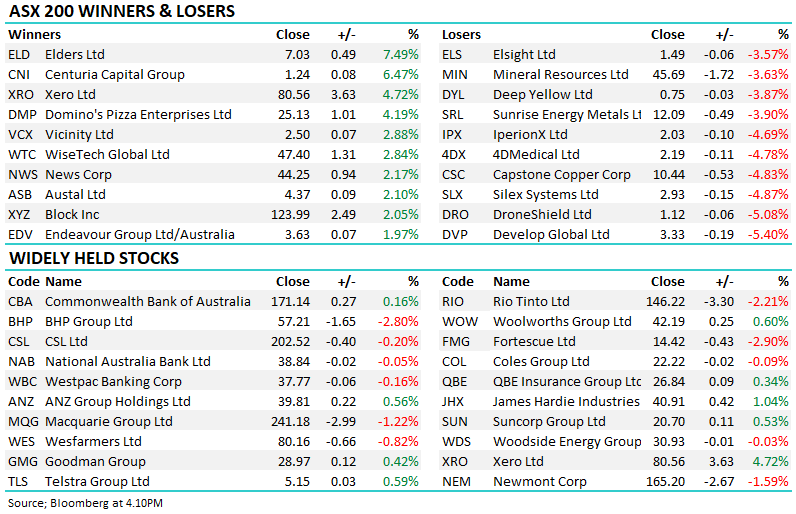
NHC -5.93%: sold off today despite delivering a solid Q1 FY27 operating update, with run-of-mine production up 10% YoY to 4.3Mt and coal sales up 9.3% to 2.9Mt. Quarter-on-quarter production was lower as Bengalla prioritised waste movement, but the more important takeaway was that realised pricing improved, with the average sales price rising 6% QoQ to A$165/t.
Underlying EBITDA of A$168.1m was broadly flat on the prior quarter, while NHC continues to target 11.5–13Mt of saleable production in FY27, with the midpoint around 6% above FY26.
Operationally, there was little to concern us. Production is growing year-on-year, pricing improved and the FY27 production target continues to point to another step-up in volumes. The softer quarter-on-quarter production numbers largely reflect mine sequencing rather than any deterioration in the underlying operation.
Separately, NHC announced a A$250m ASX-listed hybrid issue, with proceeds available for general corporate purposes and potentially to refinance part of the debt inherited through the proposed Malabar Resources acquisition. The securities will carry a 4% margin over BBSW, equating to ~8.82% (incl franking), stepping up to 5% from 2031 if they remain outstanding.
What makes the deal interesting is that it is being pitched as the first ASX-listed franked corporate hybrid from a non-financial company in around 20 years. With bank hybrids progressively being phased out, NHC is effectively tapping a pool of income investors looking for replacement securities.
We like the logic. It diversifies NHC’s funding sources, potentially reduces reliance on conventional debt and takes advantage of strong demand for income securities at a time when bank hybrids are disappearing. Importantly, it also provides additional funding flexibility around the Malabar acquisition without issuing ordinary equity.
We continue to see NHC as a well-run, cash-generative coal producer, with the Malabar acquisition adding another meaningful leg to future production growth.
MM remains long & bullish NHC
Add To Hit List