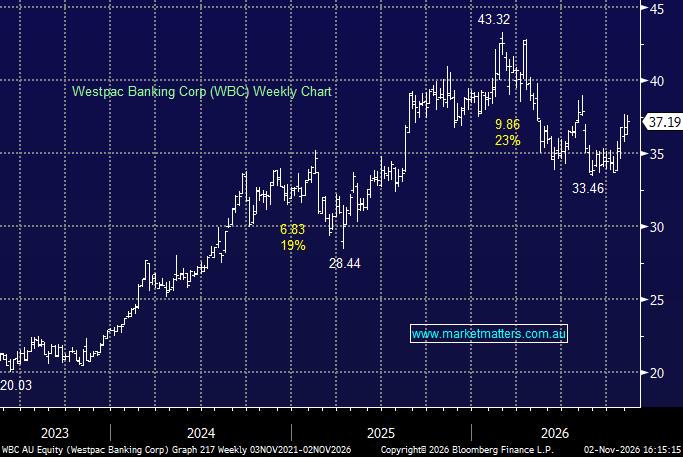
WBC +1%: Delivered a largely in-line FY26 result, with softer net interest margins weighing on earnings, however it was the improved credit quality that stood out, providing some reassurance amid higher rates and pressure on borrowers.
Key details:
- FY26 net profit of A$6.81bn, down 1.5% and slightly below consensus.
- Core NIM declined to 1.76% from 1.81%, reflecting ongoing competitive pressure.
- Expenses were broadly flat, with the cost-to-income ratio improving to 51.9%.
- CET1 capital ratio remained strong at 12.5%, with A$2.9bn of capital above its target.
- Credit quality remains sound- total stressed exposures declined to 1.17%, from 1.28% in FY25
- FY27 productivity benefits are expected to exceed A$600m.
A reasonable result from WBC, with softer margins offset by disciplined costs, solid asset quality and a strong balance sheet. Competition remains the key headwind, although management’s FY27 commentary offers some reassurance that margin pressure may not be as severe as the latest quarterly trend suggested.
We remain long WBC in the Active Growth and Income portfolios. The bank’s balance capital position, improving productivity and resilient credit quality support our position, while the extended buyback provides an additional tailwind. With competition and margin pressure still evident, we’re not expecting a dramatic earnings acceleration, but the result reinforces WBC’s appeal; its earnings are defensive and still pays an attractive yield at current levels.
MM remains long and bullish WBC
Add To Hit List