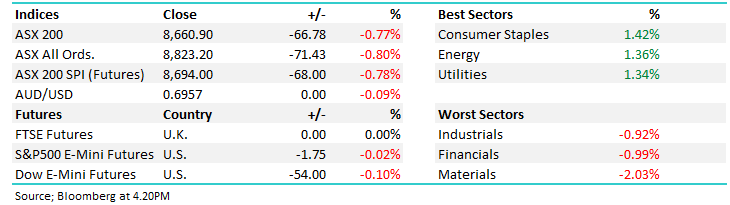
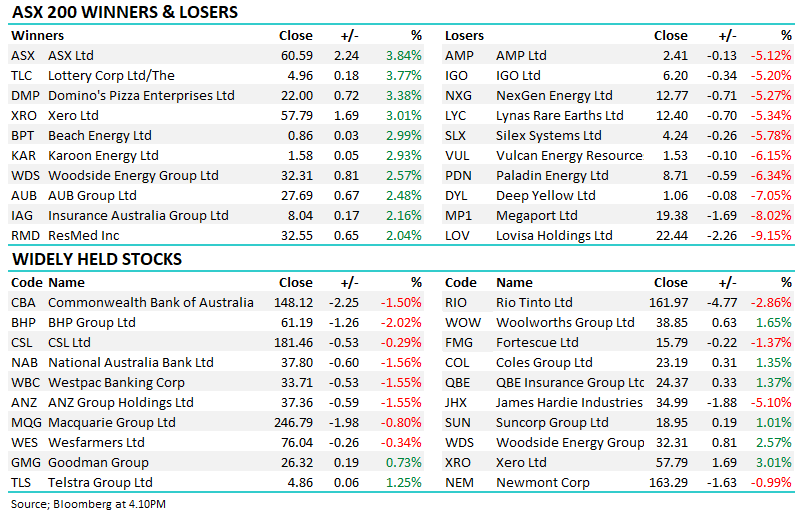
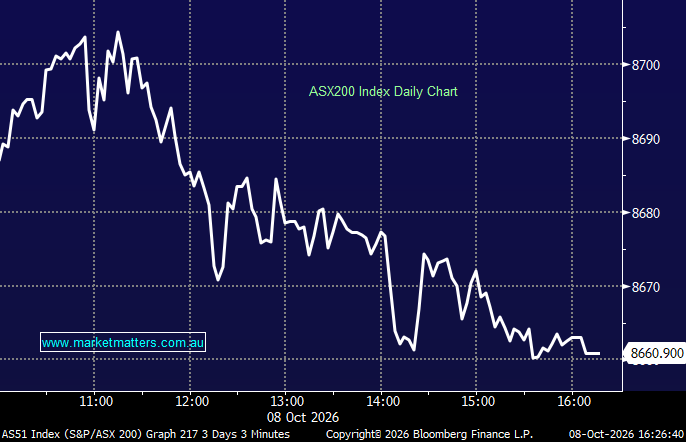
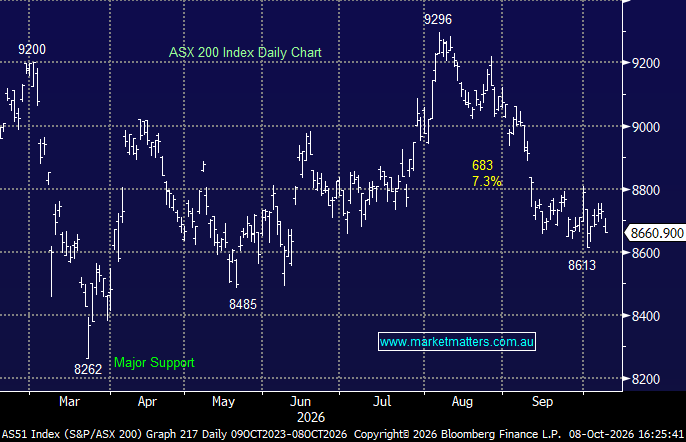
The ASX200 drifted lower yesterday on apparent nervousness ahead of this week’s US rates decision as economists weighed the prospect of a 0.75% move, or potentially a sledgehammer-style 1% rate hike – only a few months ago the idea of a 0.5% hike was foreign to investors now many believe it could be twice that amount! Markets are developing that self-fulfilling quiet before the storm feel about them before Wednesday’s decision, we’re still looking for buying opportunities but at the moment the path of least resistance remains on the downside.
Stocks endured a very tough 2nd half to last week following a strong US CPI number which caught most economists on the wrong foot, again – consensus was for inflation to have fallen by -0.1% in August but in fact, it rose by yet another +0.1%. We feel the biggest problem for equities last week wasn’t so much the unexpected positive inflation print but the aggressive optimism fuelled rally that preceded the number:
The ASX200 managed to reclaim a little lost ground yesterday but the bounce was very unconvincing with almost 60% of the main board closing in negative territory – fortunately, the influential banks enjoyed a solid day which offset the more broad-based losses. Elsewhere the Energy Sector continued to defy gravity rallying another +3.7% with all 10 stocks closing up on the day, an impressive performance considering crude oil is still languishing ~25% below its June high.
The ASX200 was clobbered over -2.5% yesterday wiping over $60bn from the local index following steep losses on Wall Street after Tuesday’s US CPI demonstrated that inflation remains stubbornly high. Waking up to a 1300-point rout on Wall Street is enough to scare any investor but we should consider the previous few sessions before throwing the baby out with the proverbial bathwater:
The last 4 sessions have seen the ASX200 recover strongly from last week’s early sell-off impressively taking the index back into positive territory for September – to be exact it rallied 4.4% from last Wednesday’s low as investors appeared to “square up” ahead of the overnight US inflation data. Tuesday’s advance was again broad-based with over 80% of stocks closing up on the day led by the Real Estate Sector for a change but it was again the lack of meaningful selling which saw the main benchmark close above 7000. This lack of selling came as no surprise to MM although the rally was stronger than we expected courtesy of a positive lead from the US equities:
The ASX200 has enjoyed a strong start to the week with yesterday’s +1% taking the index back to almost unchanged for September following the major jitters early last week – in today’s market a week is clearly a long time! Buying was broad-based on Monday with well over 70% of stocks advancing led as was expected by the Resources Sector e.g. Sandfire Resources (SFR) +3.6% BHP Group (BHP) +3.5% and Fortescue Metals (FMG) +3.3%. There was some very interesting news out of Ukraine over the last 24 hours which the market seemed to largely ignore probably because it can be interpreted in a number of different ways:
Equities managed to rally in the face of adversity last week after a tough 3-weeks, there was no major bullish news around but even as US short-dated yields continued to test 15-year highs the growth stocks enjoyed a sharp recovery post aggressive falls on Monday and Tuesday to end higher for the week:
Moving back to the markets, the RBA finally injected some optimism into stocks on Thursday after Governor Philip Lowe suggested the market needs to downgrade its projected path for rate hikes into 2023 – remember MM is looking for the Cash Rate to top out ~3% whereas the market was previously looking for a move closer to 4%. Our “best guess” is the RBA will now only hike 0.25% in October & November before giving people a reprieve in December hoping to add to the Christmas cheer i.e. the Official Rate will be 2.85% going into 2023.
The ASX200 was simply whacked on Wednesday closing down almost 100-points on fairly broad based selling which saw over 70% of stocks close in the red, losses were led by the influential resources and financials names e.g. Commonwealth Bank (CBA) -2.1%, National Australia Bank (NAB) -3.1%, BHP Group (BHP) -2.7% and South32 (S32) -2.3%. We dipped our toe back into the market in the afternoon, more on those moves later, on balance we feel that Goldman Sachs might be correct with their latest piece of headline grabbing research “Goldman Strategists warn stocks yet to make “decisive” low”:
As I’m sure most subscribers know the RBA hiked the Official Cash rate another 0.5% yesterday afternoon making it a stratospheric rise to 2.35% from 0.1% in less than 6-months. More are now likely according to governor Philip Lowe as they attempt to quell inflation providing the local economy with a great platform to emerge stronger over the future years:
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.