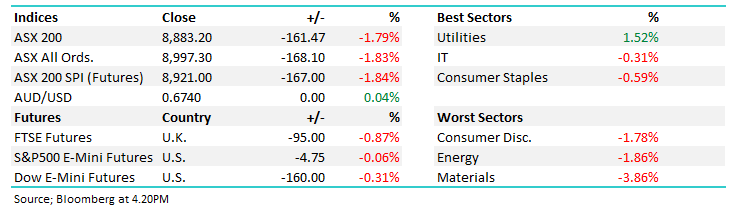
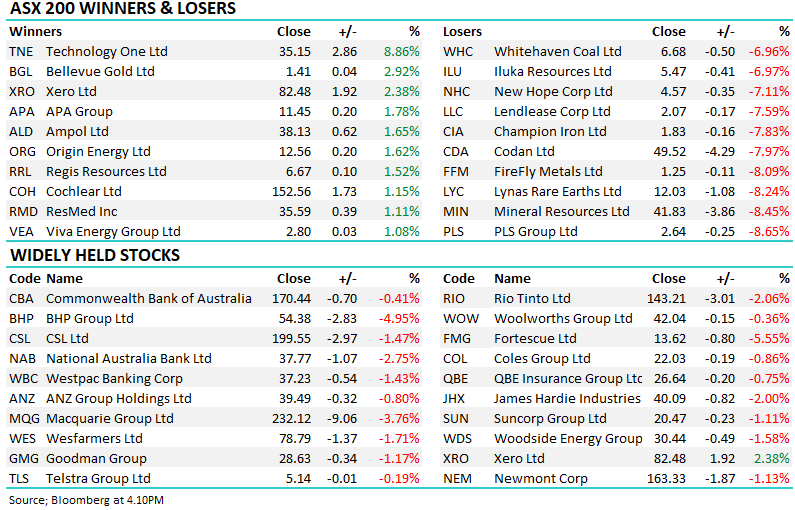
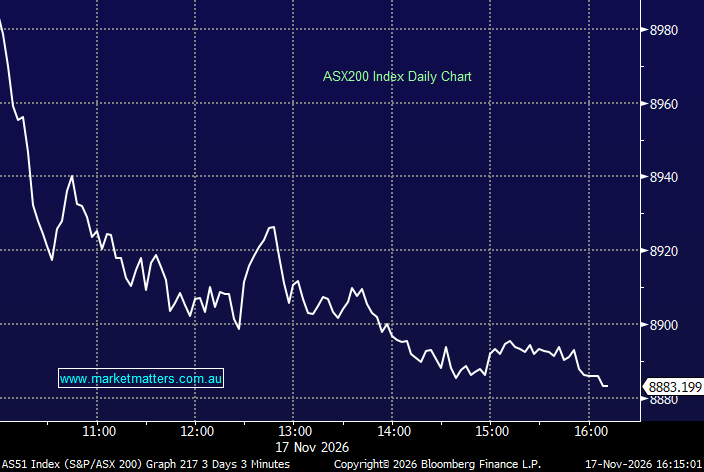
The ASX 200 ground out a +0.4% gain to start the week, but it wasn’t all plain sailing, with over 50% of the main board closing on the wrong side of the ledger. A +1% average gain by the “Big Four Banks” contributed most to the day's advance, while the miners had a mixed session, with BHP Group (BHP) gaining +0.7% helped by the pick-up in China's growth, which we will look at today, while South32 (S32) -2.6% and PLS Group (PLS) -2.7% were drags on the index. However, Monday was all about takeover fever, a subject MM has written about a few times in 2026.
Thursday's employment data shocked the market and media alike, with employment falling by 39,300 compared to the 20,000 increase economists were expecting. Bad news for the government ahead of next month's Victorian State election, but a welcome reprieve for the RBA, with markets now pricing in only a ~40% chance of another 25bps rate hike before Christmas, although inflation could ultimately force their hand if oil prices keep rising. In 10 days, we get the September CPI (inflation data), which will go a long way in determining the next move on rates.
The ASX 200 staged an impressive recovery on Thursday, clawing its way back from an early 1% decline to finish virtually unchanged at 8,720 (-0.1%), as weaker than expected employment data provided a welcome reprieve from the recent interest rate concerns.
The ASX 200 was hit -0.6% on Wednesday for no obvious reason, with renewed selling in the banks the main weight, with the financials accounting for more than 70% of the index's decline. However, weakness was broad-based, with over 70% of the main board closing lower, and the miners adding to the market's woes, which unfortunately look set to extend today.
The ASX fought valiantly on Tuesday to reverse early losses ending the session basically flat. However, it was far from a quiet session on the stock and sector front with AI facing tech stocks whacked, with Megaport (-9.9%) and NEXTDC (-6.6%) enduring sessions to forget.
The ASX 200 big guns started firing on Monday in a rare session of solidarity between the banks and heavyweight miners, the financials and materials combined to add 79-points to the ASX 200, which only closed up 66-points on the day! For a 0.8% gain it was unusual to see almost 50% of the main board close lower, such was the dominance of the likes of BHP (+2.5%) and Westpac (+2.7%).
Shawn reckons the current market reminds him of an old 1980’s song – Reasons to be Cheerful – part 3 (here), hence the title of today’s note – certainly showing his age! Despite the ongoing unsettling news across the newswires, we remain positive on equities here, and today we’ll outline some of the reasons that underpin that view.
The ASX 200 fell away on Thursday afternoon to close down -0.8%, with weakness in the influential banks and heavyweight miners again driving the index lower while further bargain hunting was evident in the rate-sensitive end of town, although not with any great gusto as would be expected when the index is tumbling toward a fresh 4-month low.
The ASX 200 failed to hold onto its early gains on Wednesday ultimately ending the session down -0.1%, smack in the middle of the day’s trading range, with the influential banks and miners dragging the index lower despite over 60% of the main board closing higher. The rate-sensitive stocks again caught our eye bucking the trend with all major retailers and real estate stocks outperforming the broader index.
The ASX advanced +0.6% on Tuesday on relatively broad based gains with over 60% of the main board closing higher. However, it was the rare combination of strength in both materials and financials that dragged the index higher, contributing ~86% of the days advance from a points perspective. What caught our eye was some buying coming back into some of the consumer facing stocks, ironically just as consumer confidence data plunged towards a 30-year low - there’s nothing quite like the combination of rising interest rates and cost-of-living pressures to squeeze everyday Australians, particularly when the holy grail of household wealth - property prices, are falling at the same time.
Thursday's employment data shocked the market and media alike, with employment falling by 39,300 compared to the 20,000 increase economists were expecting. Bad news for the government ahead of next month's Victorian State election, but a welcome reprieve for the RBA, with markets now pricing in only a ~40% chance of another 25bps rate hike before Christmas, although inflation could ultimately force their hand if oil prices keep rising. In 10 days, we get the September CPI (inflation data), which will go a long way in determining the next move on rates.
The ASX 200 staged an impressive recovery on Thursday, clawing its way back from an early 1% decline to finish virtually unchanged at 8,720 (-0.1%), as weaker than expected employment data provided a welcome reprieve from the recent interest rate concerns.
The ASX 200 was hit -0.6% on Wednesday for no obvious reason, with renewed selling in the banks the main weight, with the financials accounting for more than 70% of the index's decline. However, weakness was broad-based, with over 70% of the main board closing lower, and the miners adding to the market's woes, which unfortunately look set to extend today.
The ASX fought valiantly on Tuesday to reverse early losses ending the session basically flat. However, it was far from a quiet session on the stock and sector front with AI facing tech stocks whacked, with Megaport (-9.9%) and NEXTDC (-6.6%) enduring sessions to forget.
The ASX 200 big guns started firing on Monday in a rare session of solidarity between the banks and heavyweight miners, the financials and materials combined to add 79-points to the ASX 200, which only closed up 66-points on the day! For a 0.8% gain it was unusual to see almost 50% of the main board close lower, such was the dominance of the likes of BHP (+2.5%) and Westpac (+2.7%).
Shawn reckons the current market reminds him of an old 1980’s song – Reasons to be Cheerful – part 3 (here), hence the title of today’s note – certainly showing his age! Despite the ongoing unsettling news across the newswires, we remain positive on equities here, and today we’ll outline some of the reasons that underpin that view.
The ASX 200 fell away on Thursday afternoon to close down -0.8%, with weakness in the influential banks and heavyweight miners again driving the index lower while further bargain hunting was evident in the rate-sensitive end of town, although not with any great gusto as would be expected when the index is tumbling toward a fresh 4-month low.
The ASX 200 failed to hold onto its early gains on Wednesday ultimately ending the session down -0.1%, smack in the middle of the day’s trading range, with the influential banks and miners dragging the index lower despite over 60% of the main board closing higher. The rate-sensitive stocks again caught our eye bucking the trend with all major retailers and real estate stocks outperforming the broader index.
The ASX advanced +0.6% on Tuesday on relatively broad based gains with over 60% of the main board closing higher. However, it was the rare combination of strength in both materials and financials that dragged the index higher, contributing ~86% of the days advance from a points perspective. What caught our eye was some buying coming back into some of the consumer facing stocks, ironically just as consumer confidence data plunged towards a 30-year low - there’s nothing quite like the combination of rising interest rates and cost-of-living pressures to squeeze everyday Australians, particularly when the holy grail of household wealth - property prices, are falling at the same time.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Something went wrong. Please try again in a moment.
You're trying to view member-only content
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.