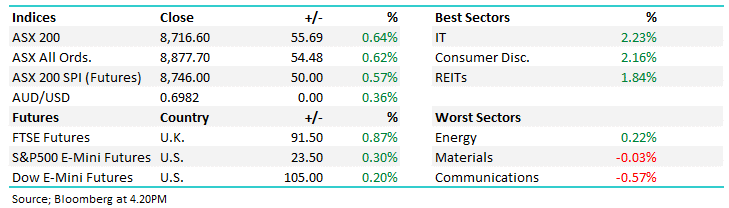
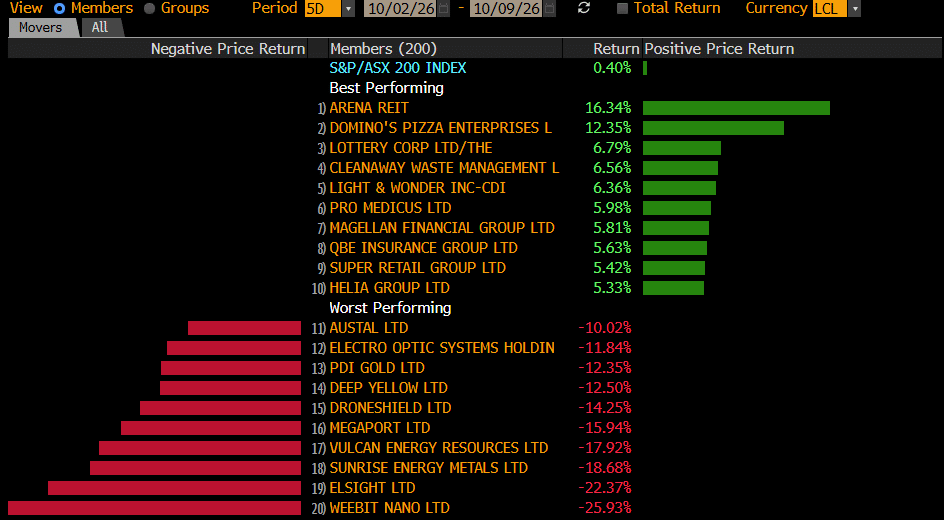
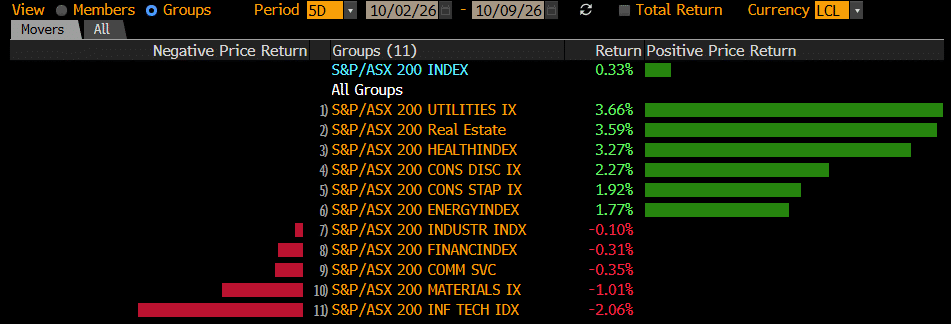
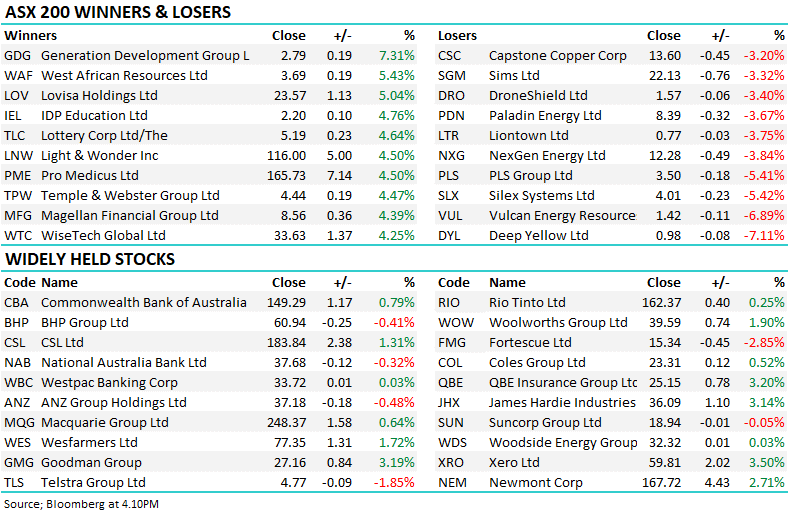
The ASX200 fell 120-points / 1.8% last week with all of the losses, plus more, occurring on Friday as rising bond yields shook the confidence of global equities. Friday was the last trading day of February and it’s common that volatility becomes elevated at both the start and finish of a month, interestingly both January and February saw early strength with tops on the 17th & 25th respectively before weakness saw most of the months gains lost in fairly rapid fashion – as we’ve said previously it feels like the airs getting thin whenever 7000 is on the horizon. From a seasonal perspective the next few months are pretty neutral before weakness usually sets in for May & June hence at this stage we believe that MM’s mantra for 2021 of “buy weakness and sell strength” remains very much in play especially when we consider the last 2 months.
The ASX200 enjoyed a strong bounce on Thursday but after 4-days of choppy trading the market remains in a tight consolidation around 6800. As we all know bond markets are playing the tune for equities in 2021 so far and this week’s seen the Australian 10-year bond yield surge form 1.43% to 1.74%, that’s a whopping +22% increase in yields in just a few days compounding the more than +75% increase in less than 2-months, its not hard to see why investors are becoming fixated with the global economic recovery i.e. reflation. We only have to look under-the-hood of the ASX at some major stocks to see how its significantly transforming the stock / sector performance so far in 2021:
The ASX200 gave back all of Tuesdays gains yesterday as the volatile consolidation pattern continues, the -0.9% fall was again highlighted by selling in the IT Sector but this time it was notably accompanied by some fairly aggressive profit taking in the Resources Sector with BHP’s -3.1% drop the most influential for the bears. Considering the markets basically gone nowhere for a month there are limited things catching our eye but a couple keep resurfacing:
The ASX200 enjoyed an excellent rally yesterday as the Resources & Banking Sectors continued to drag a begrudging index higher although this time there were also some decent gains in the Real Estate & Industrial stocks which combined to take the index up almost 1%, less impressively only 60% of the stocks managed to close in positive territory. The short-term “value-growth” elastic band continues to stretch and the likelihood is when the surge higher by bond yields takes a breather growth stocks like IT and Healthcare will find some buying, how sustainable it can be is of course the million dollar question.
The ASX200 drifted lower yesterday but the action under the hood remains very pronounced with 10 members of the index rallying by more than 5% but less than 40% of the index actually managed to close in positive territory i.e. it’s all about backing the right horse or in this case thematic / sector. Monday saw the travel stocks come back into favour while copper continued its acceleration higher conversely yield sensitive stocks like the Healthcare, Real Estate, Utilities and IT Sectors continued to struggle.
No major market news over the weekend as the COVID vaccine is rolled out from today in Australia, hopefully meaning no more state lockdowns, tennis remained the main topic of conversation both in the press and in our household and it was a bit of an anticlimax I’ve got to say! The ASX200 feels like its “wobbling” around the 6800 area but as we discussed in the Weekend Report all the actions unfolding beneath the hood. So far in 2021 the sectors catching my eye in 2021 are:
I often quote that “what defines us is how we deal with adversity” and the market certainly gave us a big right cross to recover from yesterday, mining and construction business NRW Holdings (NWH) tumbled -17% after delivering a disappointing half-year profit although we felt the market was too harsh on the stock – I felt like it was Friday when the bell rang yesterday, not Thursday.
The ASX200 gave back some recent hard fought gains yesterday under the weight of broad based selling with over 65% of the index finally closing down on the day.
The ASX200 posted its highest close in almost 12-months yesterday with the Resources Sector surging higher e.g. BHP Group (BHP) +2.7%, RIO Tinto (RIO) +3% and OZ Minerals (OZL) +4.4%
The ASX200 enjoyed a great start to the week eventually closing almost 1% higher, stocks opened strongly after global markets posted fresh all-time highs on Friday with the gains then compounded by some excellent advances on the stock level as company reports added to the markets positive tone e.g. Nearmap (NEA) +19% and Bendigo Bank (BEN) +11.3%. On the sector level the “risk on” theme remained very dominant with the Resources & IT Sectors strong while the defensive Utilities / Real Estate Sectors again slipped.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.