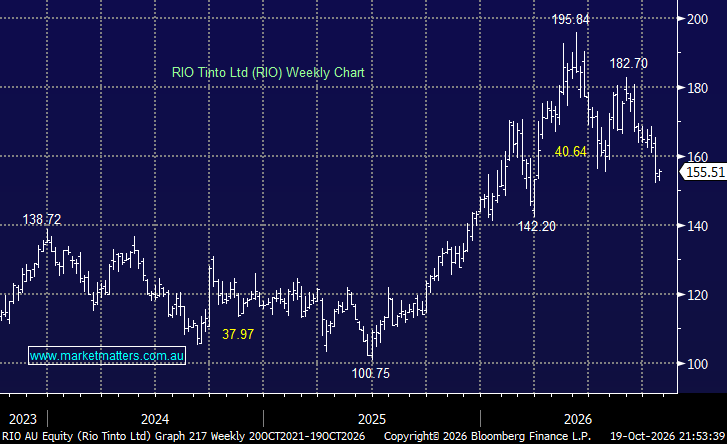
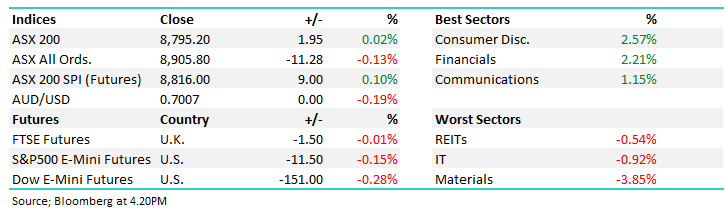
RIO has managed to eke out a ~6% gain in 2026, well behind BHP’s ~33% due to its commodity mix and poorer earnings momentum. BHP’s re-rating has been driven by its growing exposure to copper, which overtook iron ore as its largest earnings contributor in FY26 for the first time. Copper prices have risen more than 30% YoY, helping BHP deliver a 30% increase in underlying profit to US$13.2 billion. Rio Tinto (RIO), by contrast, remains more reliant on iron ore, which accounted for around 47% of first-half earnings, compared with approximately 26% from copper.
- RIO is more exposed to weakness in iron ore and less leveraged to the copper rally that has attracted institutional capital towards BHP. RIO has also faced operational headwinds.
Earnings quality and cash flow have further widened the gap. RIO’s net profit fell 14% to US$10.0 billion, while free cash flow declined 28% to US$4.0 billion as capital expenditure rose to US$12.3 billion, largely reflecting investment in Simandou and copper growth projects. BHP, meanwhile, received material earnings upgrades following its February results, with consensus EBITDA estimates rising around 6%. The market has rewarded BHP’s stronger copper exposure and earnings momentum while applying a discount to RIO’s heavier capital spending requirements and greater sensitivity to iron ore.
- We can see RIO extending its recent weakness if iron ore tests CNY660, but strong support is looming, and it could address some of its underperformance vs. BHP if iron ore finds support in the coming months.
MM likes RIO if/when it tests ~$142-5
Add To Hit List