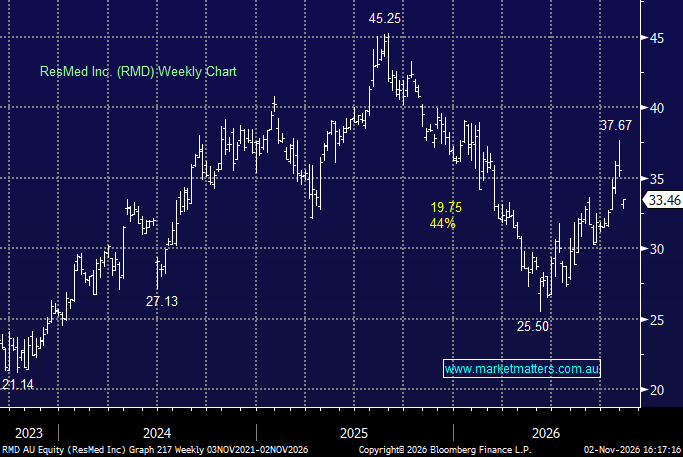
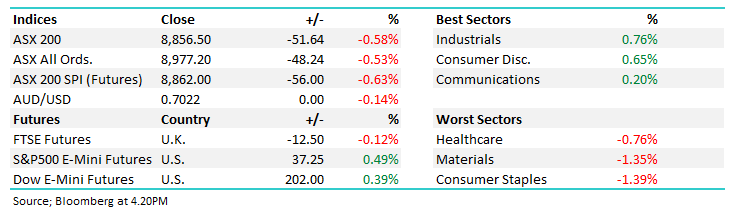
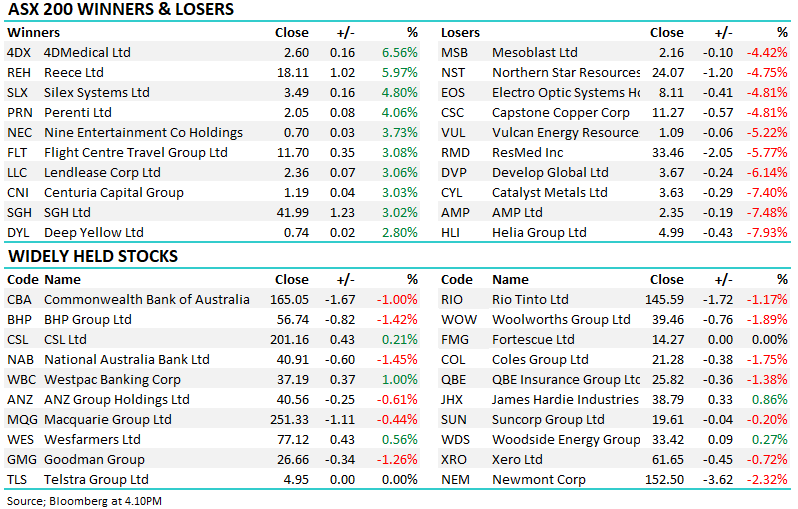
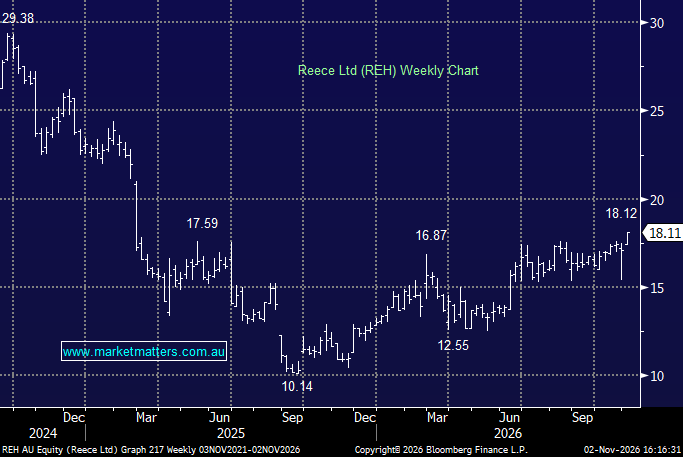
RMD -6.17%: was hit today after a strong run despite delivering decent 1Q numbers, with revenue, earnings and margins all ahead of expectations. The quality of the result was good, particularly across masks and devices, although the stock had enjoyed a strong run into the print, leaving a relatively high bar to clear.
Key Q1 highlights:
- Revenue: US$1.42bn, up 5.9% YoY vs US$1.39bn expected.
- Adjusted EPS: US$2.91 vs US$2.68 expected.
- Adjusted gross margin: 62.5% vs 61.8% expected.
- Masks & other revenue: US$540m, up 10% YoY.
- Devices revenue: US$716m, up 5.2% YoY.
- Residential Care Software revenue: US$155m, down 6.7% YoY.
- Operating income: US$453m, up 1.4% YoY.
The standout was the combination of solid top-line growth and better margins, with continued global demand for sleep and breathing products driving the result. Masks remained particularly strong, while the software business was the softer part of the quarter.
Management guided to FY27 revenue of US$5.75–5.85bn, and this was the issue for the share price today, with consensus already at ~$5.84bn i.e. towards the top end.
Overall, a strong and clean result from ResMed. The core franchise continues to perform well, margins are holding up and demand remains robust. The main issue is valuation & FY27 top line guidance, particularly after the recent share-price strength.
MM is neutral RMD ~$33.50
Add To Hit List