A fortnight ago Gold Fields Limited (JSE: GFI, NYSE: GFI) made a bid for Northern Star Resources Limited (ASX: NST); the news of the takeover crossed the Bloomberg screens on Sunday and was released to the market on Monday morning. Basically, the first time we heard of it, Northern Star’s board had already unanimously rejected the bid! The breakdown of the offer was as follows:
- For each NST share, 0.3125 Gold Fields shares (held as CDIs on the ASX) plus A$7.25 cash.
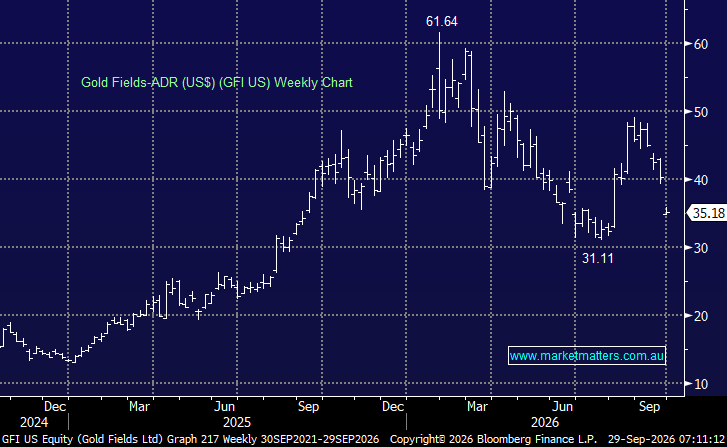
- That was worth A$27.00 per share, or about A$38.7bn in total, at Gold Fields’ 11 September close, but Gold Fields shares have plunged ~22% since.
- The mix is roughly 73% scrip and 27% cash, and NST holders would own about 33% of the combined group.
- The premium was 22% to NST’s 11 September close and 15% to its 30-day VWAP – a far from aggressive approach.
Gold Fields appears to see NST as a rare opportunity to acquire a large, high-quality producer at a discounted valuation, following NST’s production downgrades and processing issues at KCGM. The deal would immediately bolster Gold Fields’ relatively thin production pipeline, adding around 1.5Moz of annual output, while diversifying the group away from Ghana, where the key Tarkwa lease could face challenges around both the renewal terms and higher royalty rates. It would also continue an increasingly acquisitive strategy following the purchases of Gold Road Resources and Osisko Mining, although the sheer size of the NST approach is roughly ten times either deal.
- We see limited strategic appeal for NST shareholders in owning Gold Fields.

Not surprisingly, NST rejected the offer, saying it materially undervalued its tier-one, long-life assets, arguing the timing was highly opportunistic given it arrived just ahead of the expanded Fimiston mill commissioning and a change of CEO, effectively allowing Gold Fields to capture the expected operational recovery at a depressed valuation. The board also highlighted the “onerous” conditions attached to the proposal and the increased jurisdictional risk NST shareholders would inherit through the largely scrip-based deal, with Chairman Michael Chaney saying the offer “falls well short” of Northern Star’s fundamental value.
- While we feel NST have dropped the ball a few times in recent years, this rejection makes total sense to us; the bid is too low with too large a scrip component.
The ball is now back in Gold Fields’ court, and Bloomberg, which appears to have its finger on the pulse here, reports the miner is weighing its next move rather than walking away. That leaves the door open to a higher bid or an attempt to engage NST shareholders directly, although funding and FIRB approval remain meaningful hurdles.
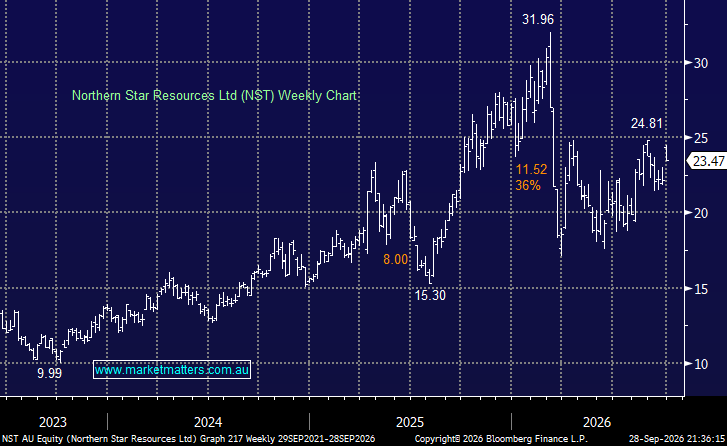
- We see Goldfields’ interest providing some support for NST’s valuation, but it’s hard to see both parties agreeing on a deal; it would need to be closer to ~$30
MM is cautiously bullish on NST ~$23.50
Add To Hit List