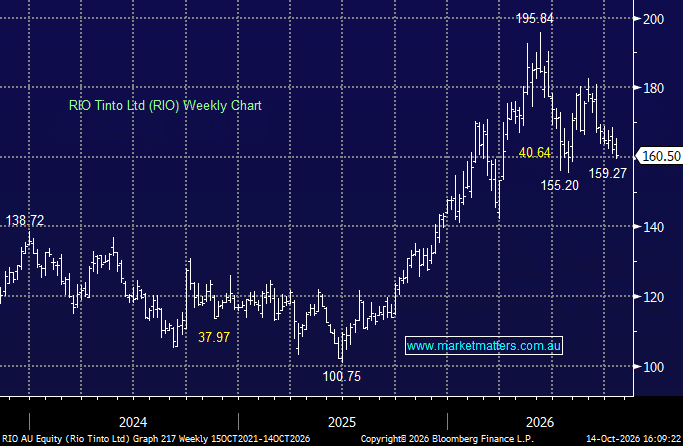
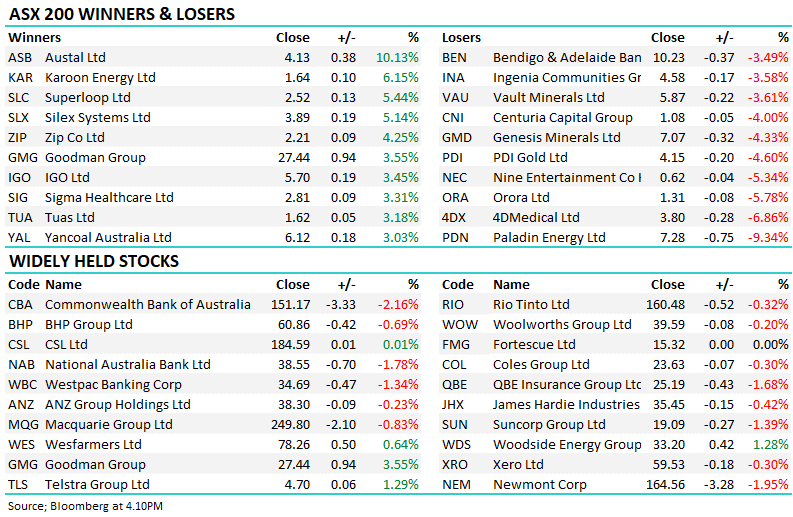
RIO -0.32%: Delivered a broadly solid September quarter, with Pilbara shipments slightly ahead of expectations and its major growth projects progressing to plan. While the operational result was relatively uneventful, the combination of productivity improvements, capital discipline and increasing copper exposure is encouraging.
Key results:
- Pilbara iron ore shipments: 85.7Mt, up 1.7% YoY, ahead of the 84.9Mt consensus.
- Copper production: 204,500 tonnes, broadly flat YoY.
- Bauxite production: 15.75Mt, down 4% YoY, but ahead of expectations.
- Alumina production: 2.07Mt, up 9.7% YoY, also ahead of expectations.
- FY26 guidance maintained: Pilbara shipments of 323–338Mt and copper production of 800,000–870,000 tonnes.
The bigger story remains Rio’s growth pipeline. Oyu Tolgoi copper production increased 27% YoY during the quarter, while Simandou remains on track to reach a 60Mtpa production run-rate in the second half of 2028. Rio is also targeting US$1.8bn in annualised productivity benefits by year-end and has released more than US$2bn of capital year-to-date. Higher diesel prices remain a cost headwind in the Pilbara, while lithium production is now expected at the lower end of guidance following weather-related disruptions.
A solid update from RIO, with the core iron ore business performing broadly to expectations and the longer-term growth story progressing. We particularly like the increasing move toward and contribution from copper, as we have so often written about, with the likes of BHP doing the same. Iron ore remains the key near-term earnings driver and has been weak of late, although the expansion of its lithium and, more importantly, copper business should gradually diversify earnings and support steady growth over time.
MM remains bullish toward RIO
Add To Hit List