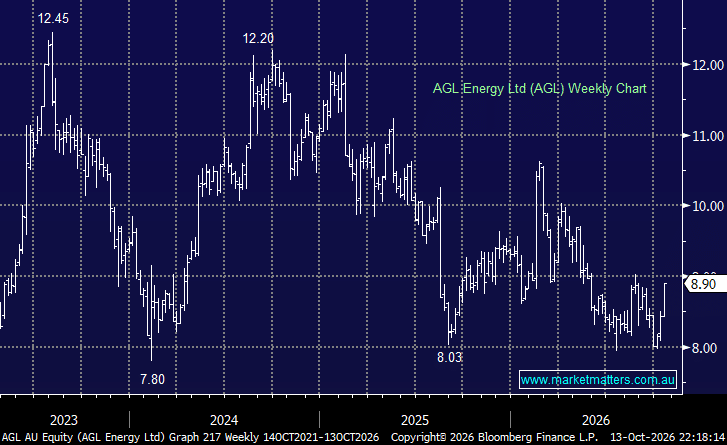
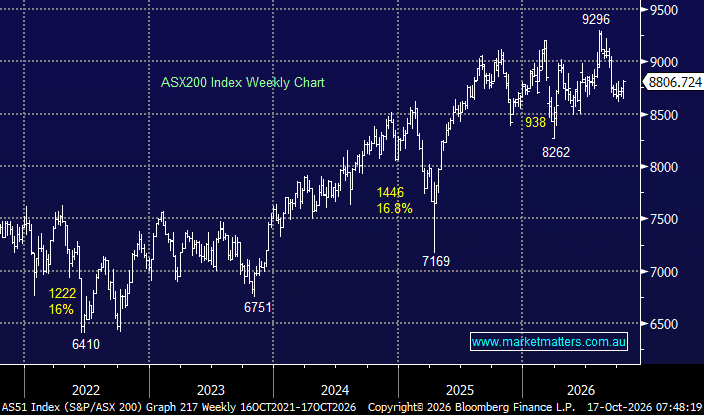
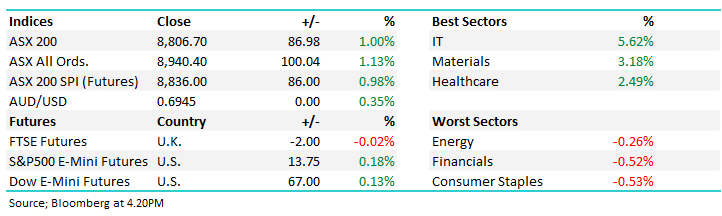
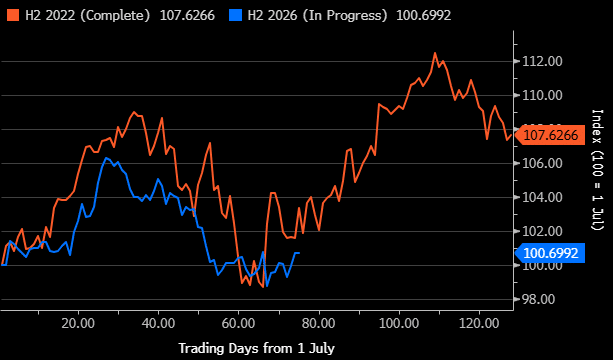
Yesterday saw strong gains from utilities AGL (+4.1%) and Origin (+2.8%) helping advance the sector +1.8%, making it the best performer on the day. The move reminded us of the performance overlay we showed a few weeks ago comparing the ASX 200 in 2022, the last time bond yields rallied strongly, and the subsequent sector performance in the fourth quarter where the utilities helped drive the markets recovery:
- In 2022, from October, the ASX 200 gained ~12%, with utilities (+27%), materials (+17%), and financials (+13%) leading the line.
chart

ASX 200 2H 2022 vs. 2026 (Indexed to 100)
chart
ASX 200 2H 2022 vs. 2026 (Indexed to 100)
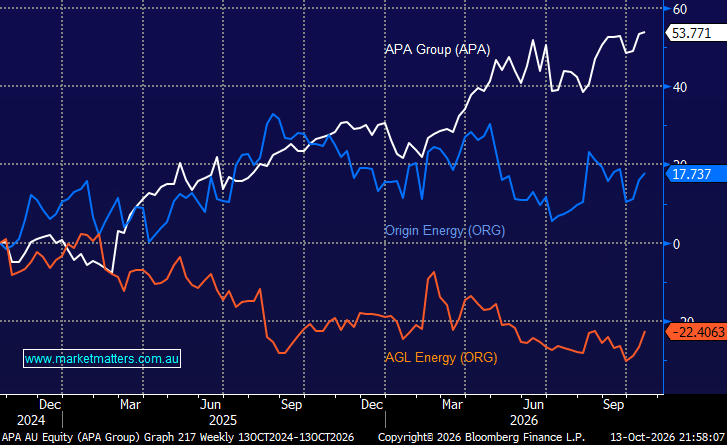
In line with our view that bond prices are approaching their nadir we are looking to add some utilities exposure to the Growth Portfolio. As the chart below illustrates, the three ASX 200 utilities names have experienced very different performances since 2025, with APA the standout gaining more than 50% while AGL has fallen more than 20%.
Firstly a quick snapshot of the three:
We covered ORG in detail mid-last month here, our conclusion being we are bullish around current levels initially looking for new highs above $13. Interestingly in late September the stock spiked lower following its FY26 results, and in particular a revenue miss, although EPS was a beat – a net disappointment after a 4-year streak of revenue beats. However, we continue to like ORG and it remains on our Hitlist.
APA’s FY26 result came out in August here, we like defensive infrastructure business, which is doing its job: growing earnings steadily, generating cash and increasing dividends, while building out a credible pipeline of future projects. However, after enjoying strong returns in both of MM’s growth and Income Portfolios we feel this previous recovery story has largely played out and despite its 5.4% part-franked yield we believe the risk/reward is deteriorating above $11, especially from a growth perspective.
chart
APA Group (APA) vs. Origin Energy (ORG) vs. AGL Energy (AGL) – % Gain/Loss
chart
APA Group (APA) vs. Origin Energy (ORG) vs. AGL Energy (AGL) – % Gain/Loss
The AGL FY26 result here, was well received due to a better than-feared FY27 outlook and dividend, i.e. 5.6% fully franked is attractive. Moving forward AGL’s growth outlook is centred on earnings resilience rather than rapid headline growth, with consensus forecasts pointing to EBITDA remaining broadly stable at around A$2.0–2.1bn through FY29 as lower wholesale electricity prices offset improvements elsewhere. The clearest near-term growth driver is batteries, with battery earnings (EBITDA) forecast to rise from A$57m in FY26 to around A$145m in FY27 and A$209m in FY28, supported by demand for flexible power as renewable generation increases and grid volatility creates opportunities to capture higher prices.
Longer term, AGL’s opportunity lies in its plan to develop up to 12GW of new renewable capacity by 2035, including batteries, wind, solar and gas peaking assets, while its existing coal fleet continues to provide a near-term earnings base. Rising electricity demand from AI and data centres presents another potential growth avenue, with AGL’s energy hubs offering land, grid connections and generation infrastructure that could support future development. However, converting these opportunities into earnings comes with plenty of risk and will require significant investment, suitable funding partners and supportive policy settings.
While consensus forecasts imply only modest earnings growth through FY29, we see scope for stronger underlying profit growth through FY30 as batteries scale up and new projects contribute. The key question is how quickly AGL can translate its development pipeline into sustainable earnings and cash flow as wholesale power prices normalise.
AGL is a “transition in progress” story rather than a near-term growth one. FY27 is a holding year, and the earnings step-up depends on batteries and peakers ramping up while coal winds down – we think it’s too early to buy AGL for growth.
We like AGL for yield, but it hasn’t made it onto MM’s Growth Hitlist – Origin Energy (ORG) still has our vote in the sector for Growth.
MM is long and bullish towards AGL for income
Add To Hit List