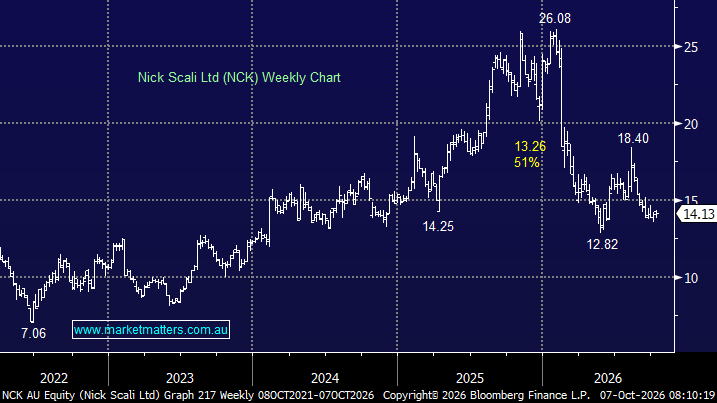
Nick Scali (NCK) has had a difficult run since its FY26 result, with the stock now back around $14 as investors remain cautious on the Australian consumer and housing cycle.We own NCK in the Emerging Companies Portfolio and, while the domestic environment remains soft, we think the market is becoming increasingly focused on the wrong part of the story.
Australia and NZ are still doing it tough. Housing turnover remains subdued, big-ticket discretionary spending is under pressure and store traffic has weakened. That was evident in FY26, when local written sales orders slowed through the second half despite the group still delivering underlying profit of $75.7m, up 22%.
The key question from here is whether the Australian business simply stabilises while the UK becomes a more meaningful growth engine. The UK opportunity is starting to look increasingly important – losses narrowed materially in FY26, the business moved into a small profit in the second half, like-for-like sales rose 19%, and early FY27 written sales orders were up 35%. The Fabb Furniture turnaround and store rebranding appear to be gaining traction, giving NCK a genuine second leg of growth beyond Australia.
This should drive an improving earnings outlook, with consensus forecasts pointing to relatively modest earnings growth in FY27, before accelerating thereafter. Importantly, the balance sheet is also expected to strengthen materially, with current net debt of around $243m forecast to move into a net cash position from FY27. That provides flexibility for continued store expansion and supports the dividend.
- At current prices, NCK is trading on ~16x forward earnings, broadly in line with its five-year average. That is not screamingly cheap on headline P/E, but other measures are more supportive i.e. Forward EV/EBITDA is around 7.9x versus an historical average of 8.2x.
More importantly, if the UK business continues to scale and earnings recover as expected, the multiple falls quickly. Consensus has NCK on around 14.8x FY28 earnings and 13.1x FY29 earnings. Income also provides support. NCK continues to offer a reasonable yield while we wait for the growth story to reaccelerate. Consensus DPS rises from 69c in FY26 to 72.5c in FY27, 79c in FY28 and 89.1c in FY29, implying a forward yield of around 5%, increasing toward 5.5-6% over the following years. That income stream is useful while the market waits for evidence that the UK rollout can offset ongoing softness in Australia.
For now, NCK remains a tale of two businesses. Australia is still soft, but the UK is increasingly looking like the more important part of the medium-term investment case. If Fabb continues to improve, store productivity lifts and the rollout gathers pace, the market should begin to value NCK less as a challenged Australian furniture retailer and more as a business with a genuine offshore growth platform.
- MM remains positive on NCK despite the domestic backdrop likely to remain challenging in the near term, and we continue to believe the UK expansion can drive the next leg of earnings growth.
MM remains bullish NCK ~$14
Add To Hit List