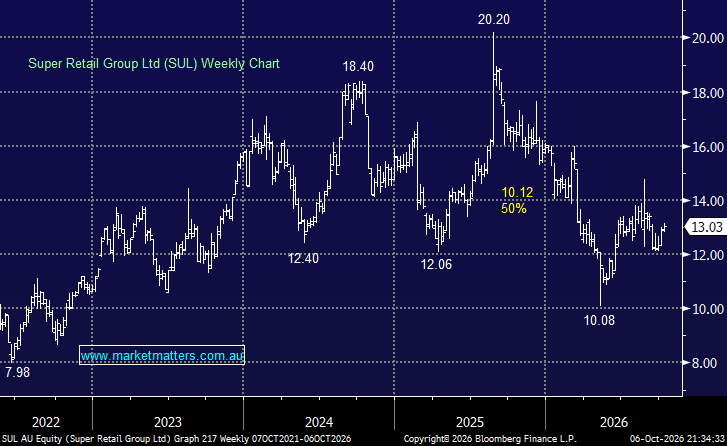
SUL has endured a tough 2026 falling ~19% so far, underperforming the weak consumer discretionary sector which is down ~11%, although it has outperformed some of its peers helped by Augusts FY26 earnings beat: SUL delivered a reasonable earnings result for the times in a reporting season that punished many consumer-facing stocks, while a resilient start to FY27 eased concerns that trading conditions were deteriorating sharply. Revenue rose 3.2% to $4.20bn, while profit of $205.9m beat consensus by ~9%; comparable sales increased 1.5% over the first seven weeks of FY27, and the group declared a 33c final dividend. Rebel was the standout, Supercheap Auto has started FY27 positively and BCF remains resilient, while Macpac continues to lag following a mild winter.
ASX major retailers YTD: Harvey Norman (HVN) -42%, Nick Scali (NCK) -40%, JB Hi-Fi (JBH) -27%, Super Retail (SUL) -19%, Premier Investments (PMV) -13%, and Wesfarmers (WES) -6%.
On the surface, SUL’s revenue has grown steadily over the past five years, with another ~5% increase expected in FY27, but earnings have been far more volatile as rising wages, rents, investment, and financing costs have squeezed margins. Revenue rose 17% from FY22–26, yet operating expenses increased 23%, pushing the EBIT margin from 11.1% to 8.5% and leaving EPS ~22% below its FY23 peak, i.e. sales have grown, but less of each additional dollar is reaching the bottom line.
Hence, with MM postulating that conditions may be approaching a nadir for the Australian consumer, we’ve also taken a fresh look at our other favourite local retailer, JB Hi-Fi (ASX: JBH) – as the chart below illustrates SUL and JBH have trodden a very similar path.
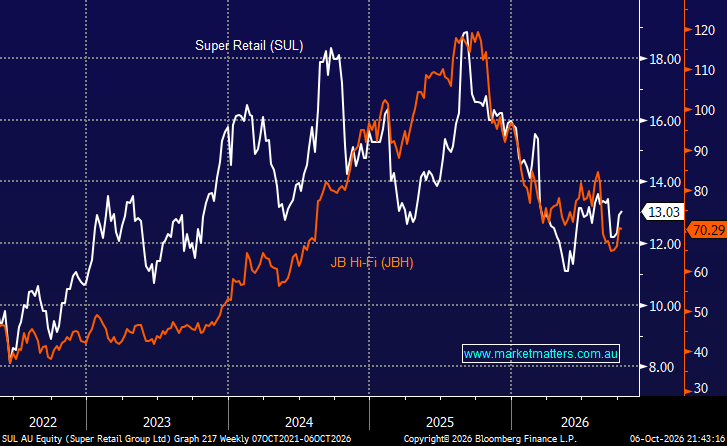
chart

Super Retail Group Ltd (SUL) vs JB Hi-Fi (JBH)
chart
Super Retail Group Ltd (SUL) vs JB Hi-Fi (JBH)
Both SUL and JBH have grown revenue by more than 20% since FY21, but their earnings outcomes have been noticeably different. JBH’s EPS has broadly held its ground, while SUL’s has fallen materially, highlighting that SUL’s challenge has been more than simply a weak consumer backdrop — higher operating costs, investment spending and margin pressure have absorbed much of its sales growth, while JBH has converted its top-line growth into earnings far more effectively.
- JBH has demonstrated better earnings quality, converting similar top-line growth into more resilient EPS, while SUL’s cost structure has absorbed the revenue gains and then some.
From a valuation perspective both are trading on the cheap side of the ledger, albeit just, but both reward shareholders with a healthy yield: Super Retail (SUL) more than 7% fully franked and JB Hi-Fi (JBH) almost 5% fully franked.
- We like both JBH and SUL, preferring SUL for income and JBH for growth – we have added both to our respective Hitlists.
MM is bullish towards SUL around $13
Add To Hit List