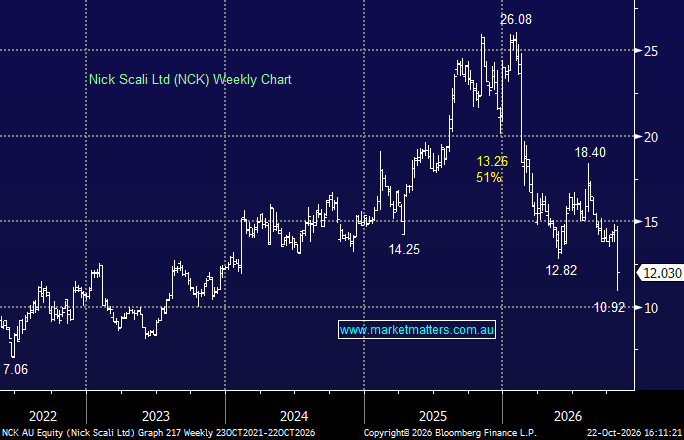
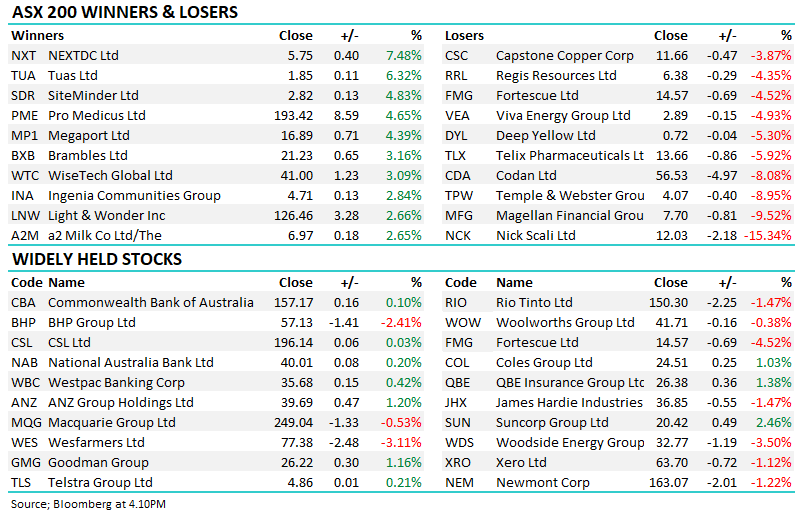
NCK –15.34%: delivered a disappointing trading update showing signs of weakness across Australia and New Zealand, flagging a material downgrade to first-half earnings expectations.
Key details:
- 1H27 net profit guidance of $28–32m, down from $41m a year earlier and around 20% below market expectations.
- ANZ written sales orders fell 15% year-on-year in Q1, while store traffic declined approximately 10%.
- ANZ revenue is expected to be 11–14% lower in the first half.
- UK written sales orders rose 29%, with like-for-like orders up 14%, providing a positive contrast to the domestic performance.
- August cyber incident resulted in approximately $980k of consulting and legal costs, which will be reported separately as non-underlying items.
The deterioration in trading is more pronounced than expected, and the housing downturn and pressure on discretionary spending are weighing on big-ticket furniture purchases, with store traffic and written orders both declining. The UK business is an encouraging bright spot, and continued store expansion provides a longer-term growth opportunity. However, the near-term outlook is challenging – the key indicators going forward will be stabilising domestic orders and protecting margins whilst trading conditions remain difficult.
MM is long but cautious toward NCK
Add To Hit List