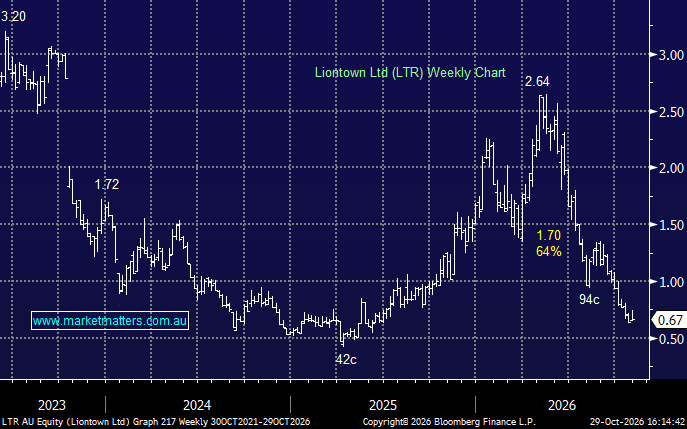
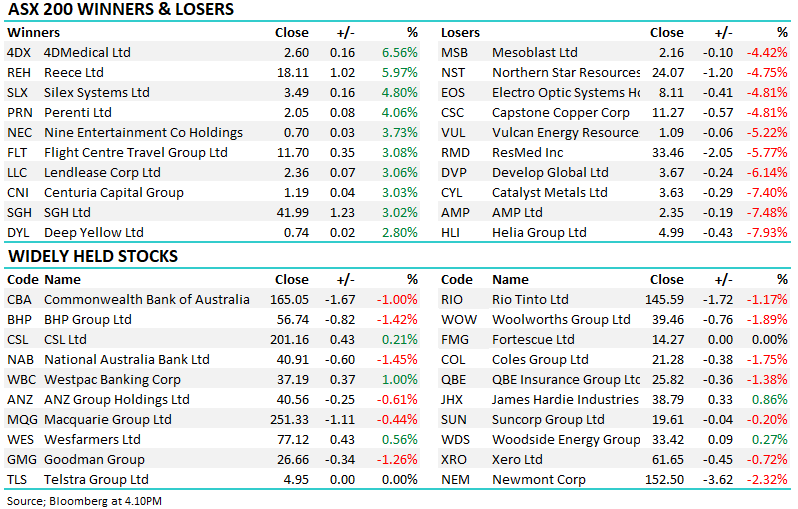
LTR –4.96%: Maintained FY27 guidance as it continues to ramp up Kathleen Valley, with the approved expansion set to materially increase longer-term production capacity. However, shares weakened alongside broader lithium sentiment, with uncertainty around Chinese demand and battery capacity continuing to weigh on the sector.
Key details:
- Q1 production of 77,982dmt, with revenue of A$199m.
- Still sees FY27 production guidance at 390,000–440,000dmt, consensus at 402,574
- Still sees capex at A$435 million to A$495 million, estimate A$468.9 million
We recently sold LTR, and the subsequent share price weakness reinforces our cautious stance. While the expansion provides an attractive longer-term growth opportunity, we struggle to see a meaningful recovery in lithium prices until uncertainty around China’s inventory levels, battery capacity and demand clears.
Stronger energy-storage demand offers some support, but near-term sentiment remains fragile. For now, we prefer to remain on the sidelines and wait for greater clarity on the lithium price outlook before reconsidering the position.
MM remains neutral toward LTR
Add To Hit List