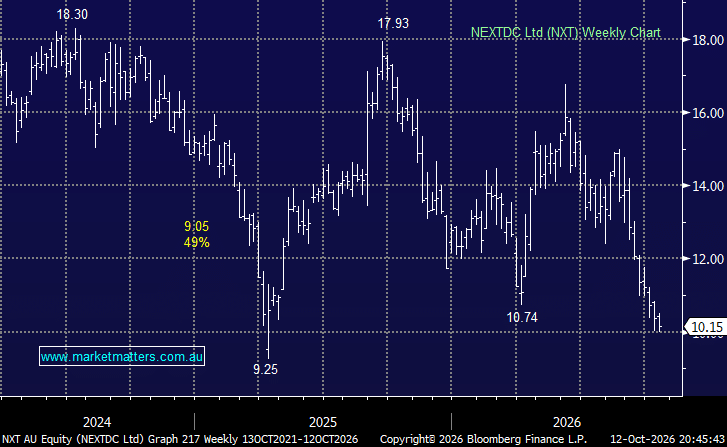
NXT delivered a solid FY26 result in August, here, which we liked at the time but the stock has continued to be weighed down by rising bond yields. The stock trades at the highest valuation of the pure-play operators, its FY26 EV/EBITDA of 51x reflects the market pricing in a very large, contracted pipeline, but the valuation does compresses sharply to 25x by FY28 as earnings start to come through.
NEXTDC has 565MW of contracted capacity in its forward order book, with 197MW expected to convert to billing in FY27 and another 221MW in FY28. Management has also guided to FY27 underlying EBITDA of $385–410m. Longer-term forecasts target EBITDA of ~$1.1 billion by FY30 – attractive numbers for a ~$10bn company (Enterprise Value).
There are still plenty of execution risks to get to that number, but we do have strong visibility on the contracted pipeline, and they have shown an ability to execute well over time. The key will be sustainable profitability, and that will depend on EBITDA growth eventually outpacing the combined burden of depreciation and interest.
The share price has been under a lot of pressure, largely a function of debt (~$3.4bn) at a time when the cost of capital has gone up significantly. The risk here is that the trend continues, and if that happens, we expect NXT to trade lower. That’s not our base case, and we do believe there are early signs of bonds stabilising. When yields turn lower, NXT will be a stock to benefit.
- We believe NXT is in an accumulation zone but sentiment could easily drag it down towards its 2025 low, or 10% lower.
MM is cautiously bullish towards NXT around $10
Add To Hit List