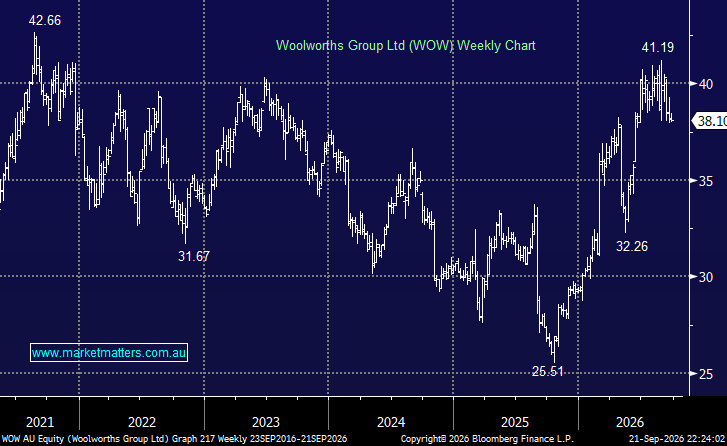
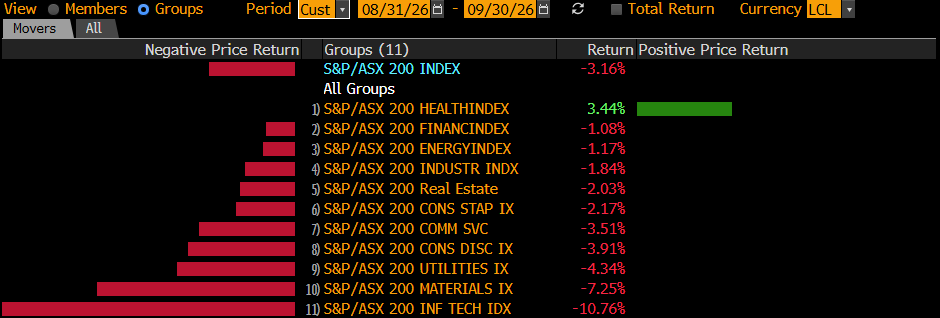
This household name that 48% of Australians say is their primary place to shop delivered a strong FY26 result covered here, but the stock has slipped ~5% since, pretty much in line with the broad market.
Looking ahead, FY27 looks like a tougher environment than FY26. Softer consumer spending, elevated costs and intensifying competition is likely to provide a more challenging backdrop. Wage inflation, higher logistics and supplier costs and the company’s investment in lower prices are having an impact on margins. At the same time, continued trade-down towards private-label products are limiting pricing power, while BIG W and New Zealand Food remain challenging.
There is also the concern of regulatory risk, rising interest rates and a relatively demanding valuation, with several brokers downgrading WOW and price targets clustering around $35–39. With Australian bond yields near 15-year highs and the consumer under increasing pressure, WOW needs an improvement in earnings momentum to justify its valuation, leaving the stock vulnerable if margins or sales growth disappoint further.
Immigration is also becoming an increasing political football, and this long-term tailwind for WOW looks set to diminish.
- We can see WOW continuing to trade in line with the ASX but see no reason to buy the retailer on a PE of 25.4x.
MM is neutral towards WOW around $38
Add To Hit List