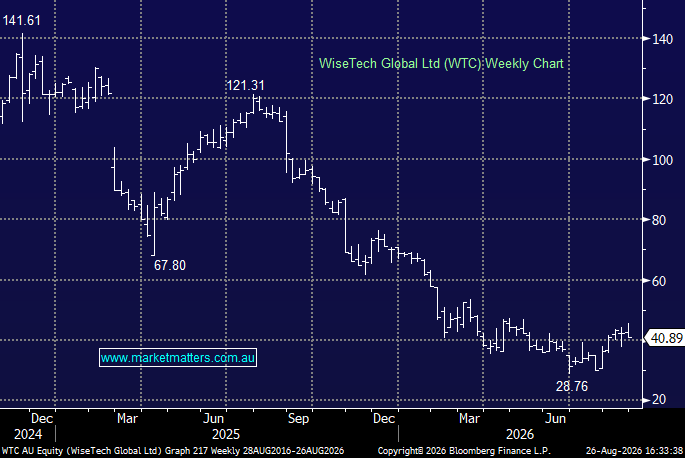
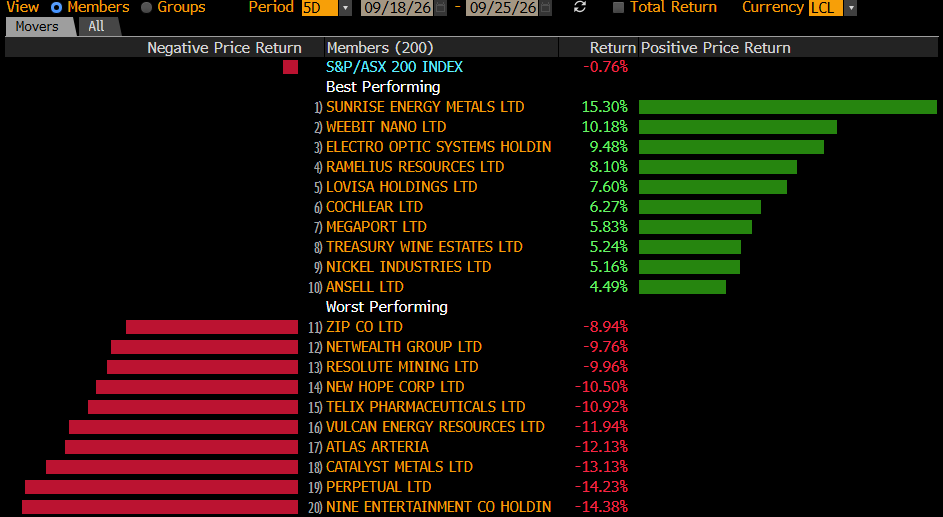
WTC -10.07%: Produced strong headline earnings growth in FY26, with underlying NPAT up 29% and EBITDA up 46%, but the market focused on a softer-than-expected CargoWise performance and FY27 revenue growth guidance of just 6–10%. For a stock that has historically been priced for exceptional growth, merely good numbers don’t cut it – particularly when the flagship platform missed the company’s own growth expectations.
Key results:
- Revenue of A$1.40bn, up 79% but slightly below ~A$1.41bn expected.
- EBITDA of A$558.4m, up 46% but below ~A$573m consensus.
- Underlying NPAT of A$313.5m, up 29% and well ahead of ~A$241m expected.
- Statutory NPAT of A$178.7m, down 11% and below ~A$249m expected.
- Recurring revenue remained very high at 95%.
- Final dividend of 8.8cps.
- FY27 revenue guidance of A$1.48–1.54bn, implying 6–10% growth.
- FY27 underlying EBITDA guidance of A$725–780m, implying 12–21% growth.
CargoWise organic growth of 11% was the key disappointment, missing the ~15% expectation and WTC’s prior 14–21% guidance. There were also no additional major global freight-forwarder rollout wins, while deleveraging has been slower than hoped. On the positive side, the AI transformation program has already generated A$34m of annualised savings following a reduction of around 1,200 roles, helping underpin a targeted FY27 EBITDA margin of 49–51%.
MM’s view: A decent result that was hampered by outlook – the quality isn’t really in question – 95% recurring revenue, huge margins and CargoWise’s strategic position are difficult to replicate – but slowing organic growth matters when you’re paying a premium multiple. Cost reductions can drive FY27 EBITDA nicely, but we’d prefer the growth to come from CargoWise acceleration and major customer wins rather than simply taking costs out. WTC remains an exceptional software asset, but the market is getting back to demanding that the earnings justify the narrative.
MM remains long and bullish WTC
Add To Hit List