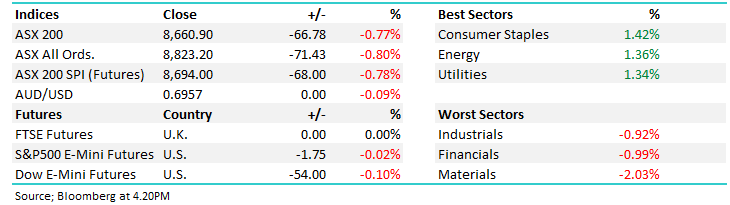
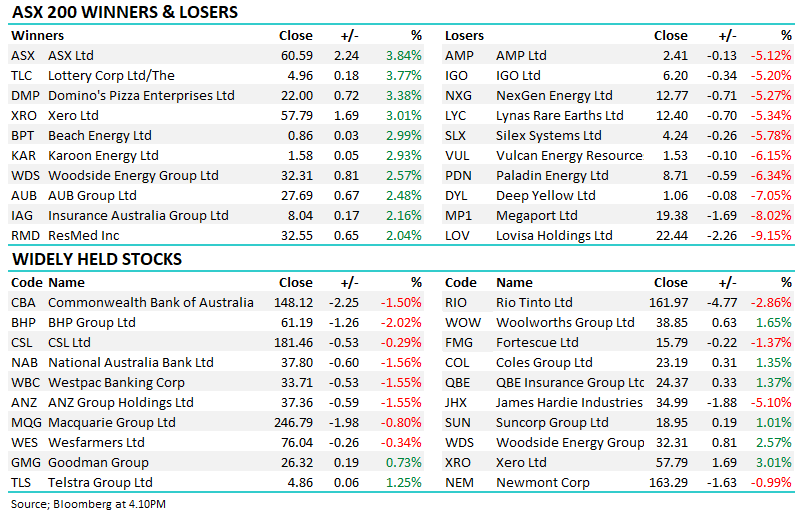
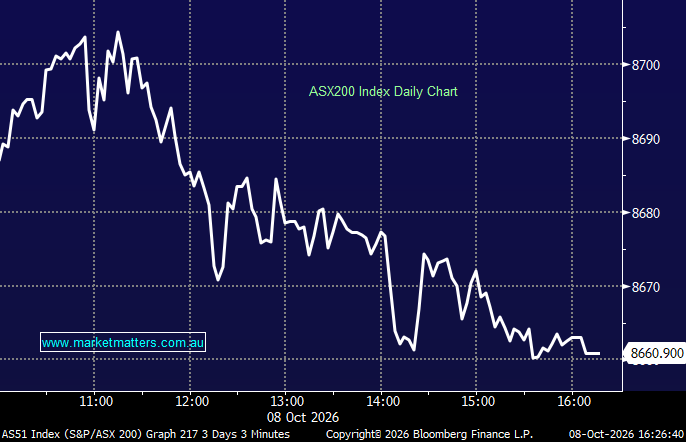
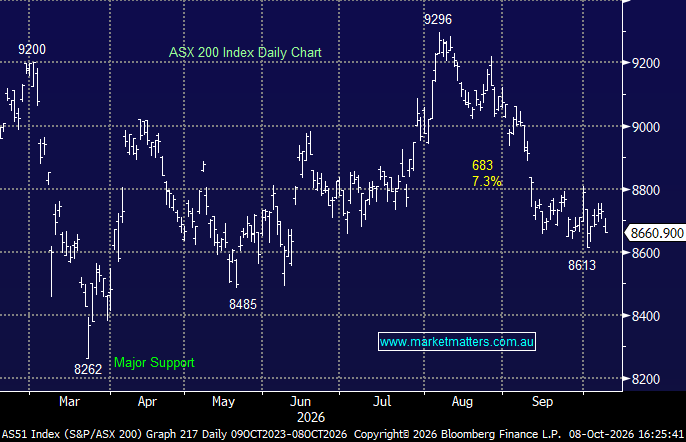
The ASX200 fell over 1% yesterday as increasing Covid cases across the globe started to weigh on an already fragile market – it already feels like ages ago that everybody was trying to buy into the re-opening trade! Over 80% of stocks on the main board fell on Monday but although there was broad based weakness it was on relatively low volume suggesting buyers simply took a step backwards as opposed to the sellers returning in force. Rising economic fears weighed on the miners as would be expected with a number of prominent names very close to making fresh 2022 lows e.g. OZ Minerals (OZL), BHP Group (BHP) and South32 (S32).
The title for Monday’s report over the last fortnight has been “Here comes the bounce – 1 & 2” and the ASX200 has delivered on the index level albeit in a slow and choppy manner with major stock/sector rotation unfolded beneath the hood - investors are swinging their attention between focusing their fears on either rising inflation/bond yields or an imminent recession. On Friday night strong US employment data saw an expected rally in bond yields which initially sent US stocks lower but it was encouraging for the short-term bulls like MM that they ground back to close unchanged setting the stage for a firm open by local stocks this morning.
The ASX200 rallied +0.8% yesterday on reasonably broad based buying that saw over 60% of the main index rally while importantly there was an absence of any meaningful aggressive selling across any of the 11 sectors. Its early days but stocks are positive for the month following the carnage experienced by equities through June, the market feels well supported at the moment which coincides with the seasonal strength that usually unfolds through July before things historically go quiet into early October. The stock / sector rotation under the hood of the market looks destined to continue for...
Bizarrely it felt like a positive day for the ASX200 on Wednesday even though the index ended the choppy day down -0.5%, most stocks managed to rally but the weakness for the index came from one very specific and influential sector of the market i.e. the heavyweight resources which were hammered following steep declines across commodities markets on Tuesday night as fears of a global recession continued to escalate. MM has been looking for a snap back in the dislocation between bond yields and tech stocks for a few weeks and it finally kicked into play with a vengeance yesterday supporting the index in the process:
The ASX200 managed to rally +0.25% after the RBA raised interest rates 0.5%, right in line with expectations, the cash rate sits at 1.35% with pundits now attempting to 2nd guess what comes next. We are in the midst of the most aggressive tightening cycle in almost 30 years after two consecutive 0.5% hikes and many people are now expecting another to follow in August as local inflation is tipped to edge towards 7% by Christmas:
The ASX200 started its first full week of July on the front foot rallying +1.1% on broad-based buying which saw over 80% of the main board close up on the day. All sectors rallied with only the industrials and utilities advancing less than 0.5%, the underlying strength flowed through from the bond market which has started to question how fast central banks will hike rates as recession fears increase, global economic data is already starting to deteriorate threatening a recession sooner rather than later. On balance, MM believes we will see rate cuts in late 2023 but in today’s uncertain...
Last week’s title on Monday was “Here comes the bounce”, things were looking on track come mid-week with the ASX200 up over 200-points but increasing recession fears were enough to reverse all of the gains plus a little more leaving the index down -0.7% come Friday’s close. Market volatility remains extremely high across a number of markets, not just financials, although interesting the stocks and sectors aren’t necessarily reacting as would often be expected:
The ASX200 bode farewell to the financial year in the same bearish manner that’s dominated the last 2-months taking its decline for the tax rule-off period to -10.2%. Losses on the disappointing Thursday compounded through the day with the index closing down 2%, only 10% of the main board managed to close in positive territory but the fall wasn’t caused by tax-loss selling as many might discuss this morning, it was all about aggressive falls in global risk assets during our time zone which flowed into the ASX:
The ASX200 struggled throughout yesterday finally closing down -0.9% although it did recover a third of the morning’s losses through a relatively unconvincing afternoon bounce. Considering over 80% of the market fell it wasn’t a bad result aided by a relatively steady Banking Sector. Under the hood, it was another tough session for tech, real estate and healthcare stocks, three sectors that keep looking for a low with very little success. Overall yesterday was a quiet day bar the sharp drop on the opening, EOFY portfolio tweaks feel like they’ve already been actioned i.e. investors have become much smarter over recent years with regards to tax-loss selling now commencing much earlier.
The ASX200 enjoyed another strong day on Tuesday rallying +0.9%, although over 40% of the main board closed down on the day – it was a stellar performance from the Resources Sector that dragged the index higher e.g. BHP Group (BHP) +4.3%, Fortescue Metals (FMG) +3.8% and South32 (S32) +3.7%. One of the main themes over the last 6-months has been the huge gyrations across the relative stock/sector performances which definitely remains in play today:
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.