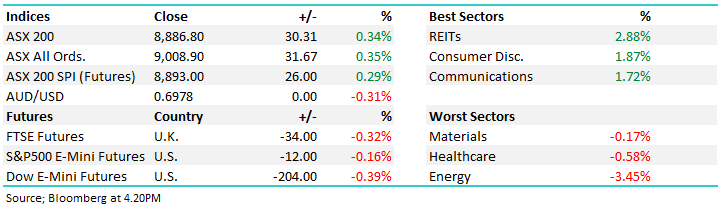
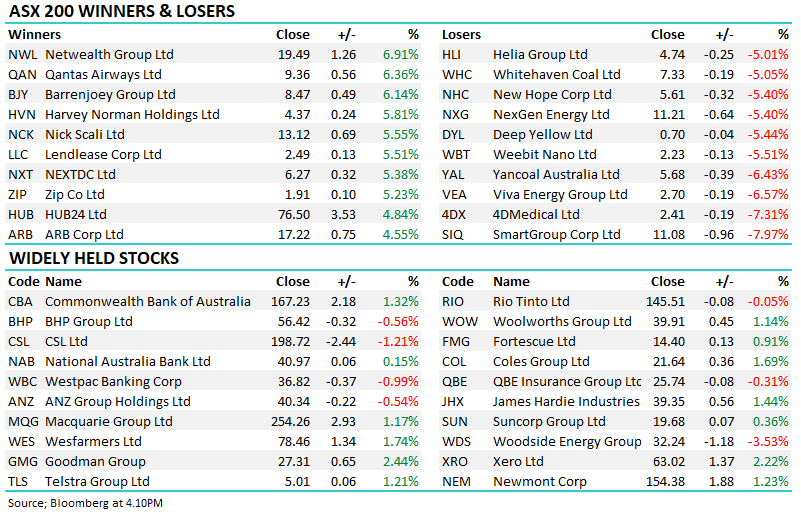
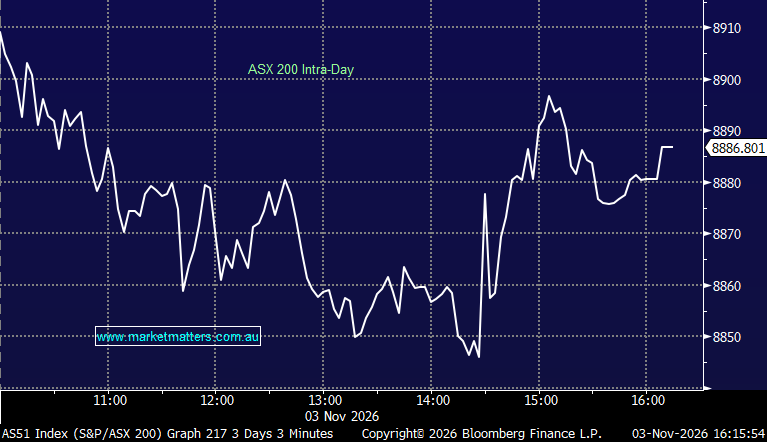
The ASX 200 started the week slowly, with the U.S session on Friday night largely in the rearview mirror, and closed for tonight, there was little in the tank to drive a move either way as strength across Energy, Materials and the banks was cancelled out by weakness in Technology. The market remains firmly in post-reporting-season mode, with attention shifting back to oil, bond yields and central-bank policy to determine the next move.
The ASX 200 struggled to hold onto a positive start on Friday, giving back an early ~0.6% gain to trade slightly lower into the afternoon. The reversal was largely a resources story, with the heavyweight names dragging on the index, while Energy also weighed despite Brent.
The local market found some support today, snapping a three-day losing streak as banks and miners led a modest rebound. The move was helped by some relief in bond markets, with the Australian 10-year yield easing from multi-year highs to around 5.16%.
The ASX came under pressure today as another surge in oil and global bond yields weighed on risk appetite. Crude oil pushed higher as tensions between the US and Iran escalated, adding to inflation concerns at a time when global central banks are already leaning increasingly hawkish.
The ASX 200 slipped every so slightly, though certainly performed better than feared given escalation in the Middle East and rate hike expectations jumping over the past few days. A renewed spike in oil prices and global bond yields was largely shrugged off at the index level, though did put pressure on rate-sensitive parts of the market as consumer names took a hit. The move was reasonably broad with 7 of 11 sectors modestly lower, though strength across Energy and parts of Resources kept the index-level decline modest.
The ASX 200 started the week on a relatively subdued note, finishing mildly lower with a strong rebound across the banks largely offset by heavy selling in Materials and Technology.
The ASX 200 finished the week on a firmer footing, bouncing around after Thursday’s broad sell-off. The recovery was led by tech stocks, which snapped back strongly after a tough couple of sessions as Nvidia and Salesforce’s overnight rallies reignited enthusiasm for the AI trade and Software trades. The banks and miners also provided support, with seven of 11 sectors higher through the afternoon.
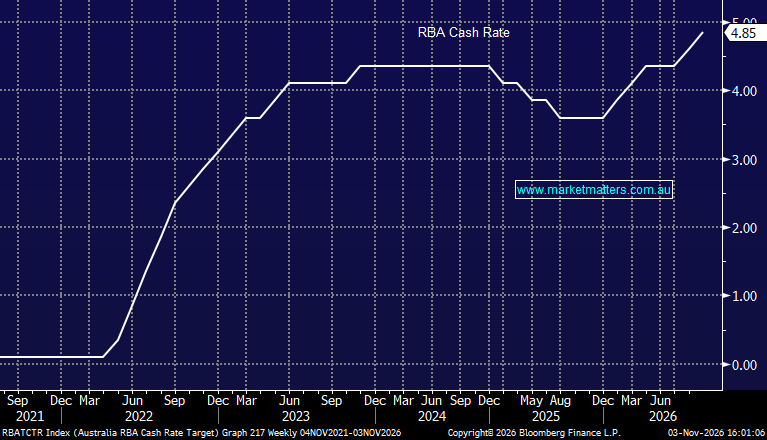
It was a slow and painful session today with the ASX sliding hour by hour through to the close in a broad-based sell-off, with 10 of 11 sectors lower, as yesterday’s hotter-than-expected CPI print drove bond yields higher and sharply increased expectations for another RBA rate hike.
The ASX 200 looked set for a third straight gain early on, trading as much as 0.6% higher to ~9220, before July inflation completely changed the tone of the session. The index reversed sharply after the release and ultimately finished lower with the market quickly pricing a greater chance that the RBA will need to go again on rates. Financials swung from an early gain into the red as higher rate expectations weighed on the market. Consumer Staples were the standout, holding onto a gain after a solid result from Woolies, while Materials remained one of the few reliable areas of strength early before giving back gains in the afternoon.
The ASX 200 put together one of its better sessions in recent weeks as the market built on Monday’s gains and breadth improved markedly. Ten of the 11 sectors finished higher with Healthcare continuing its rebound, now 44% above its low set back in June. Financials were also notably stronger, finally delivering their first meaningful bounce in around two weeks after falling almost 10% across the previous 12 sessions. BHP hit yet another record high, as weakness across lithium, rare earths, gold and parts of the iron ore complex offset strength in the diversified miners and copper exposures.
The ASX 200 struggled to hold onto a positive start on Friday, giving back an early ~0.6% gain to trade slightly lower into the afternoon. The reversal was largely a resources story, with the heavyweight names dragging on the index, while Energy also weighed despite Brent.
The local market found some support today, snapping a three-day losing streak as banks and miners led a modest rebound. The move was helped by some relief in bond markets, with the Australian 10-year yield easing from multi-year highs to around 5.16%.
The ASX came under pressure today as another surge in oil and global bond yields weighed on risk appetite. Crude oil pushed higher as tensions between the US and Iran escalated, adding to inflation concerns at a time when global central banks are already leaning increasingly hawkish.
The ASX 200 slipped every so slightly, though certainly performed better than feared given escalation in the Middle East and rate hike expectations jumping over the past few days. A renewed spike in oil prices and global bond yields was largely shrugged off at the index level, though did put pressure on rate-sensitive parts of the market as consumer names took a hit. The move was reasonably broad with 7 of 11 sectors modestly lower, though strength across Energy and parts of Resources kept the index-level decline modest.
The ASX 200 started the week on a relatively subdued note, finishing mildly lower with a strong rebound across the banks largely offset by heavy selling in Materials and Technology.
The ASX 200 finished the week on a firmer footing, bouncing around after Thursday’s broad sell-off. The recovery was led by tech stocks, which snapped back strongly after a tough couple of sessions as Nvidia and Salesforce’s overnight rallies reignited enthusiasm for the AI trade and Software trades. The banks and miners also provided support, with seven of 11 sectors higher through the afternoon.
It was a slow and painful session today with the ASX sliding hour by hour through to the close in a broad-based sell-off, with 10 of 11 sectors lower, as yesterday’s hotter-than-expected CPI print drove bond yields higher and sharply increased expectations for another RBA rate hike.
The ASX 200 looked set for a third straight gain early on, trading as much as 0.6% higher to ~9220, before July inflation completely changed the tone of the session. The index reversed sharply after the release and ultimately finished lower with the market quickly pricing a greater chance that the RBA will need to go again on rates. Financials swung from an early gain into the red as higher rate expectations weighed on the market. Consumer Staples were the standout, holding onto a gain after a solid result from Woolies, while Materials remained one of the few reliable areas of strength early before giving back gains in the afternoon.
The ASX 200 put together one of its better sessions in recent weeks as the market built on Monday’s gains and breadth improved markedly. Ten of the 11 sectors finished higher with Healthcare continuing its rebound, now 44% above its low set back in June. Financials were also notably stronger, finally delivering their first meaningful bounce in around two weeks after falling almost 10% across the previous 12 sessions. BHP hit yet another record high, as weakness across lithium, rare earths, gold and parts of the iron ore complex offset strength in the diversified miners and copper exposures.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Something went wrong. Please try again in a moment.
You're trying to view member-only content
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.