Hi Charles,
A couple of interesting angles here, with the outcomes somewhat dependent on how things play out from a macro perspective.
Firstly, the statistics around the US market are very telling. Only about 1% of the S&P 500 is trading at or around all-time highs, but importantly, these are the stocks carrying significant weight in the Index. Meanwhile, nearly half of the S&P 500 is in bear market territory, having fallen more than 20% from their respective highs.
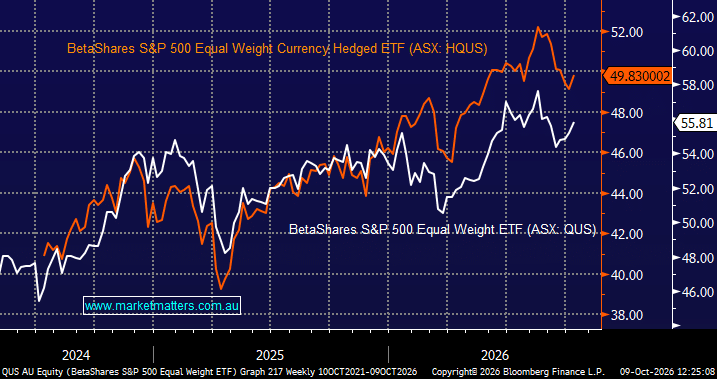
We like your thinking here, but the key will be interest rates. If rates stop rising, or begin to fall, we believe the equity market rally can broaden, allowing equal-weighted ETFs to play some performance catch-up. Conversely, if rates (bond yields) continue to rise, we expect companies delivering the strongest earnings growth, particularly those less exposed to the economic cycle (i.e. large-cap technology), to continue outperforming.
Right now, we’re 50/50 on this call, but that would change if we saw bond yields peak and begin to fall, alongside evidence of capital rotating into other sectors. As a potential trigger, we’d be looking for the US 10-year Treasury yield to move back below 5% (currently 5.23%), which could provide the catalyst for a broader market rally.
In terms of GUS versus HQUS, we’re bullish on the A$, so we’d favour the currency-hedged option, HQUS, even though its management fee is slightly higher (0.32% versus 0.29%).