Hi Debbie,
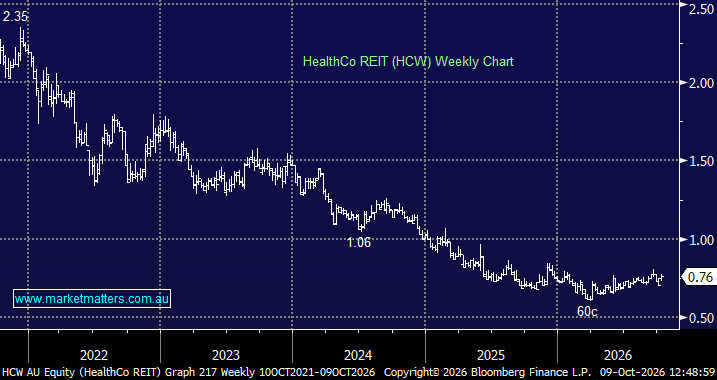
We can see why you’ve looked at HCW after its ~70% fall from its 2022 highs and return to profitability forecast for FY27. However, after failing to pay a dividend in FY25 and much of FY26, it’s easy to see why the market isn’t fully pricing in four 2.1c dividends in the years to come.
HCW has been hit hard by the collapse of Healthscope, Australia’s second-largest private hospital operator, which entered receivership and accounted for approximately 60% of HCW’s net tangible assets (NTA) at December 2025. The REIT is working to transition affected hospitals to alternative operators, but new leasing incentives could easily reduce near-term property valuations by 10–15%, even if headline rents remain unchanged.
- For a REIT traditionally valued on its income stream, the loss of distributions has been particularly damaging to investor confidence.
The Healthscope issue has been compounded by higher interest rates, declining property valuations more broadly and the consequences of HCW’s aggressive expansion in 2023, when it raised $320m to help fund a $1.2bn hospital portfolio acquisition that increased its exposure to Healthscope. HCW trades at a substantial 44% discount to its June 2026 NTA of $1.35 per unit, highlighting the market’s concerns over asset values and the recovery in rental income.
However, gearing of 29%, completed asset sales of $76.8m and an extension of its debt facilities to December 2027 provide some financial breathing room. The key to any sustained recovery will be securing replacement hospital operators, stabilising property valuations and ultimately restoring distributions, with the significant NTA discount potentially offering upside if these challenges are successfully resolved.
The recent stabilisation in price reflects some optimism that the Healthscope transition is progressing. The WA government guarantee on The Mount lease and the ongoing receiver negotiations for the remaining 10 hospitals are the key catalysts to watch. A successful re-tenanting at or near face rents, with manageable incentive packages, would be the primary trigger for NTA discount compression and distribution reinstatement.
- We like the risk/reward towards HCW around 75c for investors prepared for the volatility that a recovery stock/REIT can bring.