Hi Anton,
Unfortunately, these two stocks have endured a shocking 12-months, and in the case of GRR four-years. They are very different businesses with major structural issues:
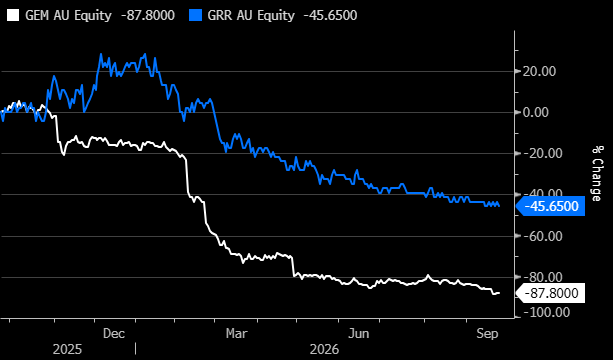
G8 Education (GEM) – GEM has collapsed almost 90% over the past 12 months, dramatically underperforming the ASX 200. The slide began with a major earnings downgrade in November before accelerating after serious child-safety incidents damaged parent confidence and enrolments.
- FY25 subsequently delivered a $303m statutory loss, ~$350m goodwill impairment and cancellation of the final dividend, while occupancy deteriorated sharply.
At the time we said “MM is neutral at best towards GEM ~70c” – we should have been more bearish!
Conditions have worsened even further through 2026, prompting G8 to suspend operations at 40 underperforming centres, while 1H26 revenue fell 11% and operating EBIT slumped 64% to A$14.7m. Consensus forward EPS has fallen roughly 67% over the past year, showing that the share-price collapse reflects both a severe deterioration in earnings and a major loss of market confidence.
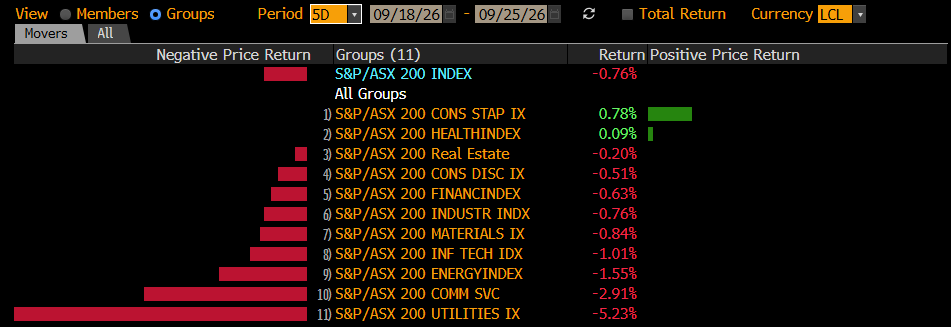
Cost-of-living pressures, lower birth rates and increased childcare supply have added to the challenge, but GEM’s problems extend well beyond the broader weakness in Consumer Discretionary.
- We see no reason to buy GEM, even below 10c, the companies decline has a terminal feel about it.
Grange Resources (GRR) – underperformance by GRR comes down to company-specific disappointment combined with a softer iron ore backdrop. The turning point was the FY25 result in February: revenue fell 8% to $477.9m, NPAT dropped 21% to $46.6m, and critically no final dividend was declared. That decision stripped away the key drawcard for income-focused holders who’d grown used to a hefty yield.
- GRR paid a 2.5c fully franked dividend in 2024, this was scraped in 2025.
These challenges have been compounded by the less supportive iron ore market, with China’s property downturn weighing on steel demand and the ramp-up of Guinea’s Simandou project adding to future supply concerns. At the same time, GRR lacks exposure to the commodities driving the broader Materials rally, most notably gold and copper.
While GRR remains profitable, earnings have deteriorated sharply over the past four years, with revenue and margins under sustained pressure since 2023.
- We cannot see downside from current levels but also there’s no compelling reason for MM to buy this $150mn iron ore miner. Iron Ore mining is a volume and logistics game, and GRR falls short in both areas.