Hi John,
Telix Pharmaceuticals (TLX) has agreed to acquire Germany’s ITM Isotope Technologies Munich in a transformational deal that significantly expands its position in radiopharmaceuticals. In the large deal TLX has agreed to pay US$1.65bn upfront, predominantly through ~US$1.25bn of new TLX shares, with a further US$700m potentially payable subject to regulatory and sales milestones for ITM’s lead therapy, ITM-11.
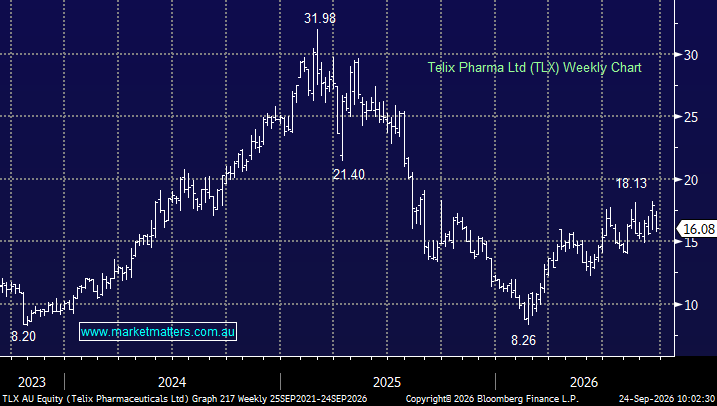
- The issue of almost 106mn new TLX shares at $16.65 is clearly dilutive and has weighed on the stock which closed at $17.85 last week.
The fact the stock was trading above $16 on Wednesday bears testament that investors think the deal is “ok” but not amazing otherwise it would have held above $16.65.
Strategically, the deal sounds good, creating a vertically integrated radiopharmaceutical business spanning drug development, isotope production and global manufacturing. Importantly, ITM is the worlds only globally scaled commercial producer of lutetium-177, while its pipeline adds several late-stage therapeutic assets, including ITM-11 for neuroendocrine tumours.
The market initially cautious view is understandable, and replicates moves we’ve seen when other ASX names make large acquisitions, but the strategic rationale is compelling:
- ITM brings a profitable, cash-generative isotope manufacturing operation, strengthens Telix’s supply chain and accelerates its push into commercial cancer therapeutics.
The combined business is expected to generate more than US$1.3bn of pro-forma 2026 revenue, with Telix targeting US$50m of cost synergies in just two years.
- We like the ITM deal and believe TLX is a buy around $16 but note the bio pharma space is not our area of expertise.