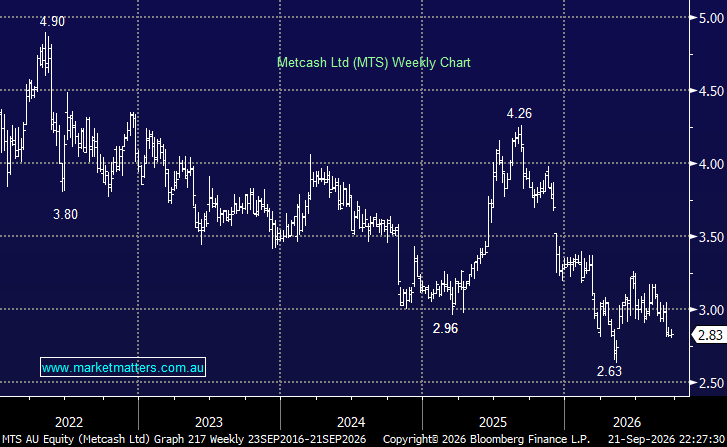
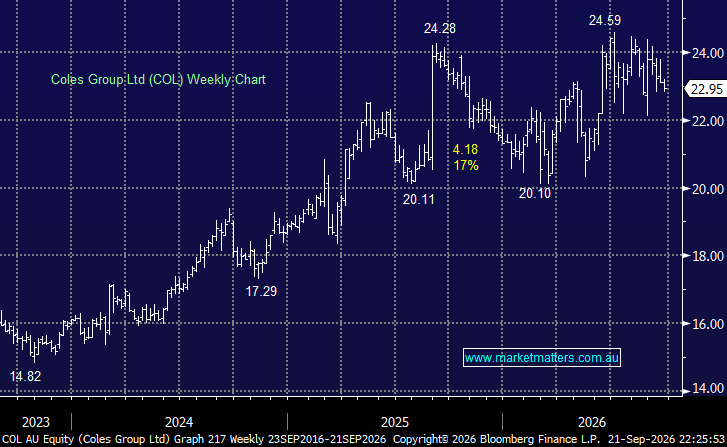
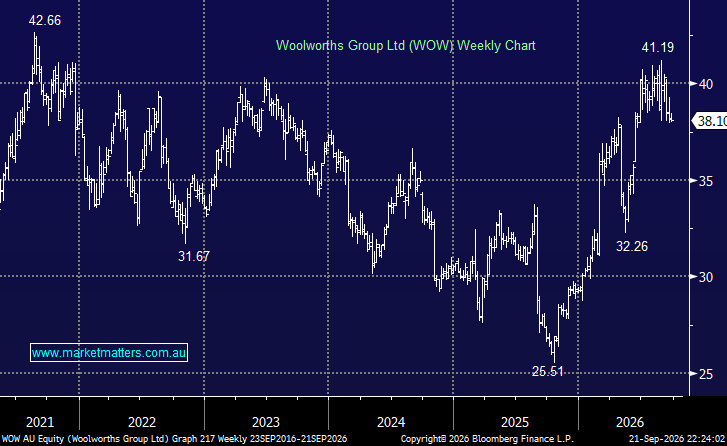
Metcash delivered its FY26 result in June here, with the standout read being earnings had stabilised, but growth was hard to come by – echoes of Coles. Metcash (MTS) is trading on just 12.1x forward earnings, roughly half the multiple of Coles and Woolworths, while early FY27 sales growth has remained positive across Food, Liquor and Hardware. We believe the valuation support, combined with resilient supermarket trading and solid cash flow, makes MTS the clear value play of the three, although near-term earnings remain under pressure from weaker hardware margins, tobacco-related headwinds and ongoing cost inflation.
Conversely, Woolworths carries the highest valuation and weakest analyst rating mix, leaving less room for disappointment after its strong share-price run, while Coles sits somewhere in the middle. Hence, on balance, we feel MTS offers the greatest valuation upside if trading conditions stabilise, while its larger cousins carry greater risks due to their elevated valuations, i.e. both COL and WOW are trading above their 5-year average PE while MTS remains at more than 10% discount.
- We can see MTS trading higher into Christmas and particularly like the stock’s ~6.4% fully franked yield- we hold MTS in our Income Portfolio.
MM is bullish on MTS for yield around $2.80
Add To Hit List