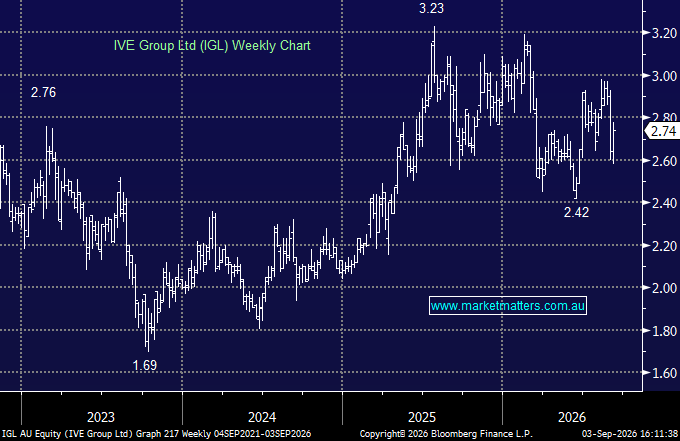
IGL +0.74% reported FY26 results on 26th August that were reasonable in a difficult operating environment, with earnings broadly in line with guidance and the dividend slightly better than expected. FY27 guidance points to another year of broadly flat earnings, leaving the investment case resting heavily on valuation, yield and the prospect that recent investment starts to generate better growth further out.
Revenue fell 1.8% to $937.4m as softer conditions across retail and media weighed on catalogue and publishing volumes, though this was offset by continued improvement in margins. Material gross profit margin increased to 51.4% from 49.3%, helping pre-AASB 16 underlying NPAT rise 3% to $52.5m. Post-AASB 16 underlying NPAT was $51.2m, down 1.7%, while statutory NPAT fell more sharply to $37.4m because of non-operating costs associated largely with the Dandenong South and Kemps Creek relocations, which IGL strips out.
Key numbers:
- Revenue: $937.4m, down 1.8%
- Pre-AASB 16 underlying NPAT: $52.5m, up 3%
- Post-AASB 16 underlying NPAT: $51.2m, down 1.7%
- Net debt: $173.2m, or 1.5x pre-AASB 16 EBITDA
- FY26 dividend:5c fully franked, ahead of guidance and up from 18c last year.
The margin performance was the strongest aspect of the result. IVE has spent heavily consolidating operations into its Kemps Creek supersite, expanding 3PL capacity and building out packaging, while also integrating acquisitions. Those initiatives should ultimately create efficiencies and broaden the revenue base, while the company is also pushing into AI-enabled services and recurring revenue opportunities.
However, the FY27 outlook is pretty ho-hum. Management expects underlying NPAT on a pre-AASB 16 basis to be broadly stable, reflecting continued economic uncertainty. The good news is that capex should fall sharply to around $26m following the recent investment cycle, which should improve free cash flow and help reduce leverage, while the dividend payout ratio is moving back toward 55–65% of underlying earnings.
This is where the stock becomes interesting. At around $2.70, IGL is trading on roughly 9x FY27 earnings with a fully franked yield north of 7% based on current consensus. Those are clearly attractive numbers, particularly if earnings can simply hold together while cash flow improves and debt comes down.
The core print and catalogue businesses remain exposed to weak macro conditions and structural pressures, while some of the newer growth initiatives – packaging, 3PL and AI-related services – still need to prove they can generate sufficient incremental earnings to offset softness elsewhere.
We don’t currently own IVE, although it remains on our Hitlist. At the current valuation, there is certainly enough yield and value to keep us interested, but with FY27 looking more like a year of consolidation than acceleration, we don’t see an obvious need to rush.
MM is mildly positive IGL ~$2.70
Add To Hit List