GQG was smacked ~20% on Wednesday after reporting ongoing large net outflows and ongoing poor performance – it’s now a $2.3bn business that has dropped out of the ASX 200.
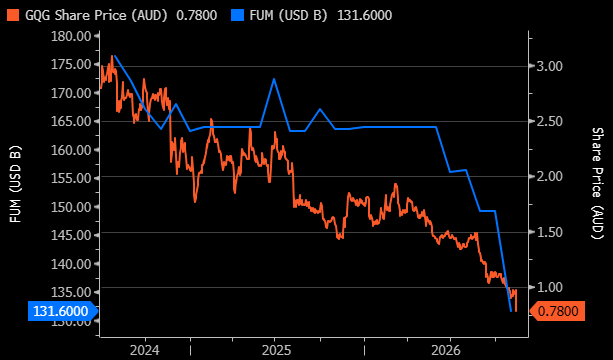
- FUM fell to $131.6bn, down from $163.7bn a year earlier.
- CIO Rajiv Jain’s mid-year pivot from AI sceptic to AI bull backfired badly in October, with GQG’s US equity fund tumbling ~10% last month.
The selloff demonstrated a lack of confidence in GQG as structural outflows and performance-driven FUM erosion from a poorly timed strategy shift combined yesterday as October’s FUM disclosure saw analysts start to downgrade the stock; more are likely in the coming days. It’s going to take more than one good month to turn this ship around, and we are glad to have cut our position last month – sometimes cutting losses can add the most value to a portfolio over time.
GQG’s revenue is almost entirely management fee-driven. The average management-fee realisation rate in 1H26 was 48.6 basis points (bps) of FUM, up slightly from 48.2 bps in 1H25. It does have some performance fees on ~3% of its FUM, but it’s clearly minimal. Hence its simple, the more FUM it loses, the less money it makes.
If we wanted to align with GQG’s pivot towards US tech, we would rather do so through a simple ETF because even if Rajiv’s is correct, it may not stem the outflows.
- We would not consider catching this falling knife as FUM outflows and poor performance continue to drive the stock lower.
MM is neutral towards GQG below 80c, at best
Add To Hit List
chart

GQG Partners (GQG) vs FUM – Source: Bloomberg
chart
GQG Partners (GQG) vs FUM – Source: Bloomberg