Hi Michael,
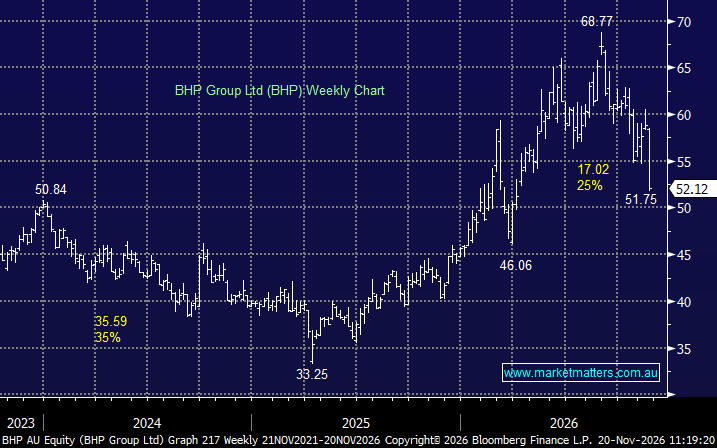
Most of your question was addressed in Friday’s report and our Alert here, where we added to our existing BHP position into weakness.
- We are looking for LME copper to find a low around US$12,000/t, only a few per cent below this week’s low. At those levels, we believe stocks such as BHP and RIO move firmly into accumulation territory.
- As we’ve highlighted in several recent notes, it may take months for the market to regain confidence in AI and, by extension, parts of the commodity complex. However, BHP’s ~5% fully franked yield makes it relatively easy to remain a patient holder.
This week has seen NVIDIA deliver a stellar result and Anthropic successfully complete the world’s largest IPO raise, yet the broader AI trade remains under significant pressure.
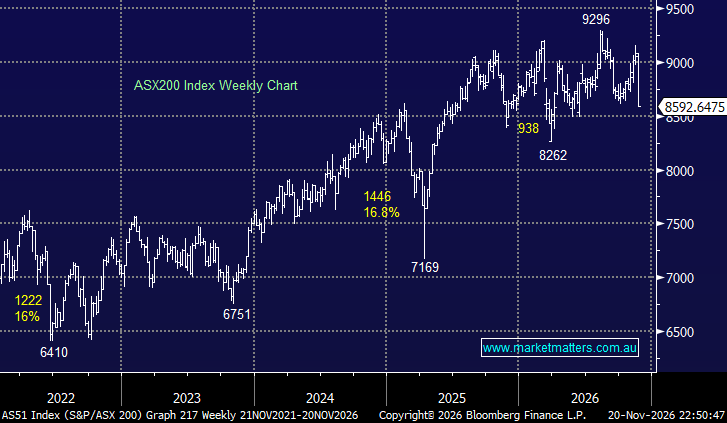
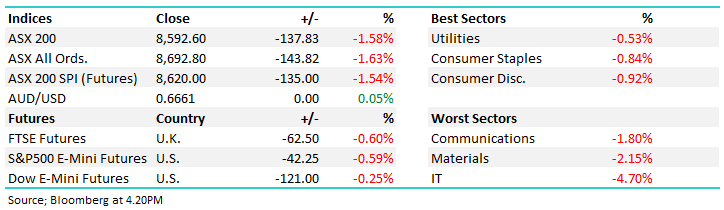
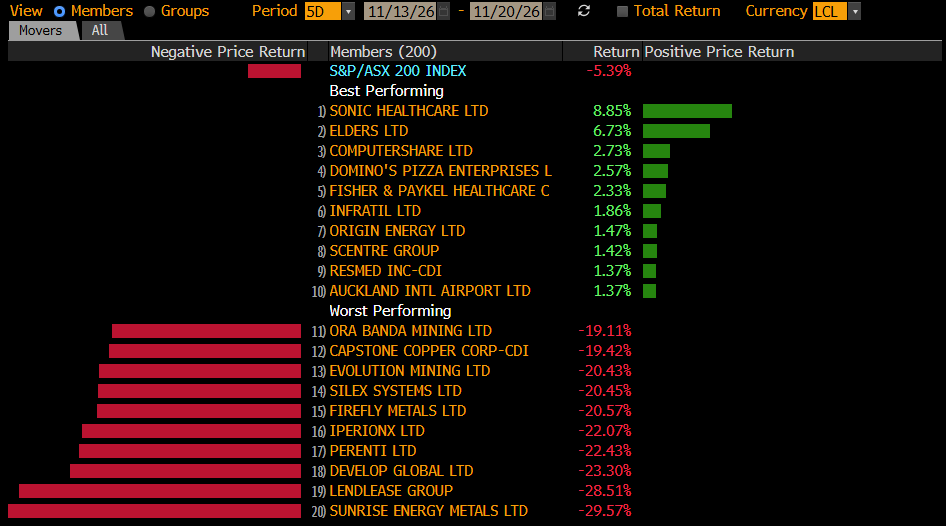
Clearly, concerns around the sustainability of the AI thematic are growing, and the moves across many parts of the equity market, particularly commodities, have been extreme. It highlights just how interconnected markets have become. With AI investment underpinning broader growth expectations, any questioning of that growth engine is prompting investors to pare back exposure to growth-sensitive assets.
We still believe the AI trade has further to run, but more importantly, we remain attracted to the supply/demand dynamics across selected commodities. Copper, for example, is important to AI infrastructure, but its applications extend well beyond technology. Supply is highly unlikely to keep pace with demand over the coming years and, if history is any guide, when that happens, prices rise. We therefore remain positive on selected areas of the commodity complex.
On GQG, unfortunately, we think they’ve switched back into technology at precisely the wrong time. They missed much of last year’s upside before materially rebuilding their exposure in the June quarter, leaving them with significant technology exposure heading into the recent sell-off.
In our view, the timing of that repositioning has been poor and has materially impacted relative performance. We expect ongoing outflows to persist for an extended period, putting further pressure on earnings and, ultimately, the dividend.
The 34% yield currently displayed by CommSec is backward-looking and should not be viewed as representative of future distributions. Given the combination of investment performance, potential outflows and earnings pressure, we expect the share price to remain under pressure for some time yet.