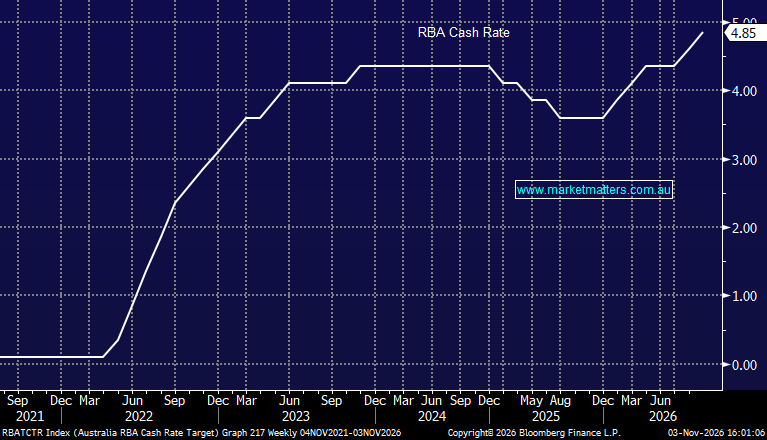
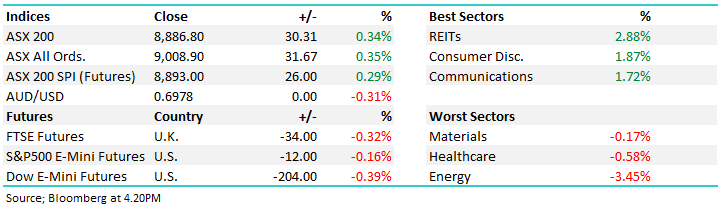
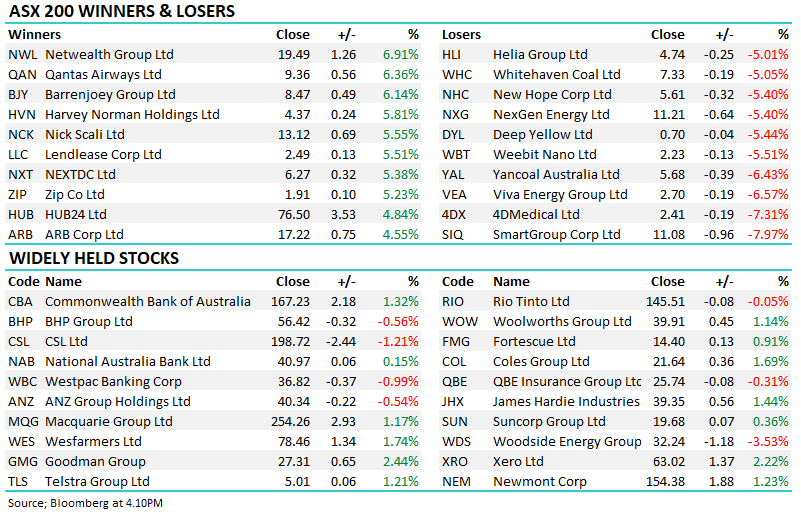
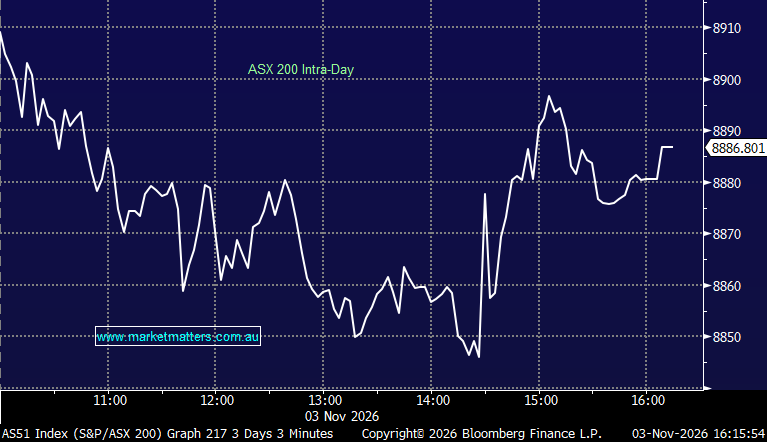
The ASX ultimately finished Melbourne Cup Day higher, but it was was struggling into the RBA decision, trading down around ~40 points, before rallying after the Bank delivered the widely expected 25bp hike. The split 6-3 vote, together with a more balanced message from Governor
Aussie shares finished lower as the market braces for another RBA rate hike whilst also digesting Friday’s sharp US tech sell-off, with weakness in banks, miners and supermarkets dragging the bourse down. A solid result from Westpac sparked divergence across the banking sector, with the remainder of the Big Four closing lower, while small caps and technology stocks showed relative resilience.
It was shaping up to be a very strong finish to October for the ASX early today, with the index up almost 1% and briefly pushing back toward 9,000 for the first time since early September. Unfortunately, the strength didn’t last. The ASX steadily gave back most of its gains through the afternoon as weakness in global technology stocks, resources and selected growth names weighed, eventually closing ~80 points below the early session highs.
The ASX posted a solid session as select rate-sensitive sectors helped the market extend gains despite a hotter local CPI print yesterday, with banks and property shares leading after Wall Street rose on the Federal Reserve’s decision to hold rates overnight. Consumer stocks remained under pressure amid softening retail updates, while Materials came off the boil slightly, with lithium names particularly soft as Chinese spodumene prices fell.
The ASX gave back much of its early advance, with a ~90pt intraday reversal after hotter-than-expected inflation data lifted rate concerns. Miners and technology shares held up well as the market continued to respond positively to the Anthropic IPO filing yesterday, while Defensive sectors lost ground, reversing some of their recent outperformance
The ASX recovered from an early decline as Anthropic’s IPO filing revived global appetite for AI-related stocks just as stronger-than-expected Chinese economic data helped light a fuse under the Materials sector.
The ASX staged a sharp intraday recovery, rallying ~85 points from its morning low to finish higher as technology, resources and property shares turned higher. The rebound followed early weakness as the market weighed the risk of higher interest rates against a busy week of Australian inflation data, US earnings and central bank decisions. Materials recovered some ground after last week’s selloff, while the major banks pared their early losses.
The ASX spent most of the session trading lower off the back of a weaker session playing out in the US, particularly Tech overnight. Banks and consumer-facing stocks provided a lift, but the modest gain masked a sharp divide across the market.
Local shares finished lower as higher oil prices and renewed rate-hike fears weighed on sentiment, with weakness across energy, materials, and consumer stocks. Despite a rebound in parts of the technology sector, concerns over data-centre funding and execution risks persisted, while a sharp retail profit warning underscored the pressure higher living costs and borrowing rates are placing on consumers.
The ASX managed to finish slightly higher today after a topsy turvy session. Early gains were pared back after RBA deputy governor Andrew Hauser warned inflation was materially worse than forecast in August, pulling the index briefly back below the 8,800, level however a push through the afternoon led by the heavyweight Financials was enough to eke out a gain.
Aussie shares finished lower as the market braces for another RBA rate hike whilst also digesting Friday’s sharp US tech sell-off, with weakness in banks, miners and supermarkets dragging the bourse down. A solid result from Westpac sparked divergence across the banking sector, with the remainder of the Big Four closing lower, while small caps and technology stocks showed relative resilience.
It was shaping up to be a very strong finish to October for the ASX early today, with the index up almost 1% and briefly pushing back toward 9,000 for the first time since early September. Unfortunately, the strength didn’t last. The ASX steadily gave back most of its gains through the afternoon as weakness in global technology stocks, resources and selected growth names weighed, eventually closing ~80 points below the early session highs.
The ASX posted a solid session as select rate-sensitive sectors helped the market extend gains despite a hotter local CPI print yesterday, with banks and property shares leading after Wall Street rose on the Federal Reserve’s decision to hold rates overnight. Consumer stocks remained under pressure amid softening retail updates, while Materials came off the boil slightly, with lithium names particularly soft as Chinese spodumene prices fell.
The ASX gave back much of its early advance, with a ~90pt intraday reversal after hotter-than-expected inflation data lifted rate concerns. Miners and technology shares held up well as the market continued to respond positively to the Anthropic IPO filing yesterday, while Defensive sectors lost ground, reversing some of their recent outperformance
The ASX recovered from an early decline as Anthropic’s IPO filing revived global appetite for AI-related stocks just as stronger-than-expected Chinese economic data helped light a fuse under the Materials sector.
The ASX staged a sharp intraday recovery, rallying ~85 points from its morning low to finish higher as technology, resources and property shares turned higher. The rebound followed early weakness as the market weighed the risk of higher interest rates against a busy week of Australian inflation data, US earnings and central bank decisions. Materials recovered some ground after last week’s selloff, while the major banks pared their early losses.
The ASX spent most of the session trading lower off the back of a weaker session playing out in the US, particularly Tech overnight. Banks and consumer-facing stocks provided a lift, but the modest gain masked a sharp divide across the market.
Local shares finished lower as higher oil prices and renewed rate-hike fears weighed on sentiment, with weakness across energy, materials, and consumer stocks. Despite a rebound in parts of the technology sector, concerns over data-centre funding and execution risks persisted, while a sharp retail profit warning underscored the pressure higher living costs and borrowing rates are placing on consumers.
The ASX managed to finish slightly higher today after a topsy turvy session. Early gains were pared back after RBA deputy governor Andrew Hauser warned inflation was materially worse than forecast in August, pulling the index briefly back below the 8,800, level however a push through the afternoon led by the heavyweight Financials was enough to eke out a gain.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
Verication email sent.
Check your email for an email from [email protected]
Subject: Your OTP for Account Access
This email will have a code you can use as your One Time Password for instant access
!
Invalid One Time Password
Please check you entered the correct info, please also note there is a 10minute time limit on the One Time Passcode
To reset your password, enter your email address
A link to create a new password will be sent to the email address you have registered to your account.
Something went wrong. Please try again in a moment.
You're trying to view member-only content
Market Matters members receive daily market reports, real-time trade alerts, full access to 5 portfolios and dynamic company data.
Choose how you'd like to proceed:
We have a range of membership options to suit your needs and budget, why not join today and get unlimited access to the premium Market Matters service.