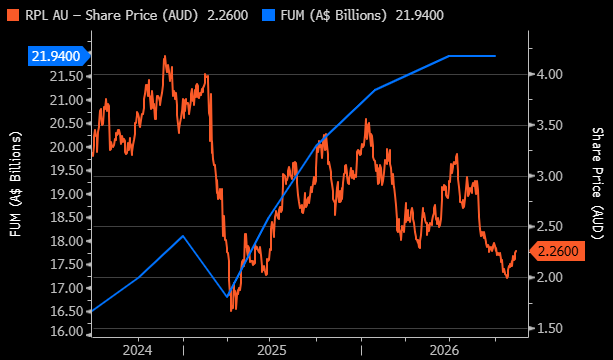
The performance of RPL has been very different to GQG as the FUM has nearly doubled over the last 3 years, a very different story despite mixed performance – RPL is still far smaller than GQG with a market cap of $940mn. We last discussed RPL in detail here, after the stock was whacked in March as its large investment in biotech Opthea went south.
Regal has evolved in a timely fashion from a high-conviction, equities-focused manager, heavily influenced by Phil King’s stock-picking ability, into a broader alternatives platform, more akin (on a much smaller scale) to a Blackstone-style model. The timing of this move from a single lead PM model to a collection of specialist investment teams has been far better than its play on Opthea, with Phil King’s retirement in June next year and succession planning well advanced.
Through a combination of organic growth and acquisitions, the business now spans multiple strategies:
- Long/short equities (still core), Private markets & venture, Real assets & natural resources, credit & income strategies plus special situations / event-driven investing
As a business, there’s certainly a better spread of risk than with GQG, but it still all comes down to returns over time, and recently, these have been very underwhelming i.e. their Atlantic Fund was down 35.7% in October alone, while the Tactical Opportunities Fund was off 20.5% and their generally well regarded Small Companies Strategy fell another 9.4%.
Regal’s fee model is fundamentally different from GQG’s; it is a dual-revenue business with meaningful performance fees, reflecting its alternative/hedge fund DNA. Regal’s fee model is richer but more volatile than GQG’s; the ~1.08% management fee rate is more than double GQG’s ~49 bps, and performance fees add a further ~1%+ in strong years. However, the higher cost base of running a multi-strategy alternatives platform means net margins are lower and more variable.
Regal’s profitability is meaningfully exposed to fund performance; a bad year for its hedge funds directly compresses earnings.
- We like Regal, but they need to turn around performance. FUM tends to be sticky after periods of weakness because they generally bounce back hard, but if weakness in returns persist, outflows will become reality. For now, we are in watch mode around performance and FUM. If we start to see outflows, the position will be cut.
MM is long bullish towards RPL below $2.30 (for now)
Add To Hit List
chart

Regal Partners Ltd (RPL) vs. FUM – Source: Bloomberg
chart
Regal Partners Ltd (RPL) vs. FUM – Source: Bloomberg